


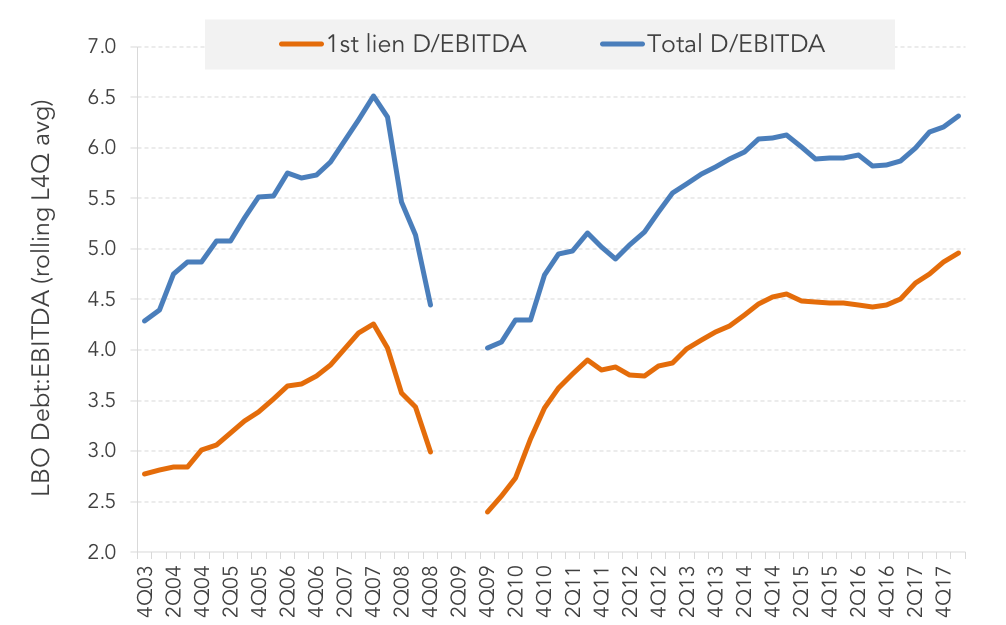
Debt to EBITDA levels on LBO deals spanning the entire market (including broadly syndicated and institutional middle market loans) are currently averaging 6.3 times when looking on a rolling last four quarter basis. This would make it the highest post-crisis average and second only to 4Q07’s average of 6.5 times. As competition for deals has increased, demand has overheated, causing leverage on LBO deals to increase. In fact, the rolling last four quarter average has now increased for seven consecutive quarters dating back to 3Q16. Average first-lien leverage has increased as well, with the rolling average increasing to 4.96 times so far this quarter, an all-time high. First-lien debt has taken up a larger share of the LBO capital structure post-crisis compared to pre-crisis when the highest average peaked at 4.25 times in 4Q07. So far this quarter there has been a handful of issuers with LBO loans that have pushed leverage higher. Deals for PetVet, Pro Mach, Convergint Technologies, FeeCo, Safe Fleet and MedRisk all have debt to EBITDA seven times or higher.
Contact: David Puchowski
David.Puchowski@thomsonreuters.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
