
Markit Recap – 5/21/2018
Has contagion returned to the eurozone?
Bismarck said politics was the art of the possible. Holders of sovereign bonds issued by eurozone peripherals will be hoping this aphorism applies to Italy’s incoming government.
A populist coalition formed of the anti-establishment Five Star Movement and the right-wing League, which looks set to form a government, seemed far-fetched immediately after the inconclusive election result in March. The two parties are in many respects unlikely bedfellows, though they share similar views on immigration and, most importantly, the EU.
The coalition has proposed a political novice, Giuseppe Conte, as prime minister. Doubts over his qualifications aside, the appointment of the finance minister is perhaps more important. Paolo Savona, an experienced economist with eurosceptic views, has been put forward as the coalition’s preferred candidate. This marked the latest in a series of moves that have roiled the fixed income markets.
A theoretical objection to the euro is one thing, but practical policies that could soon worsen Italy’s already dire finances and place it on a collision course with the EU is an altogether different prospect. The coalition has outlined an economic programme of spending increases and tax cuts that would increase Italy’s debt burden, not to mention flagrantly flout EU fiscal rules.
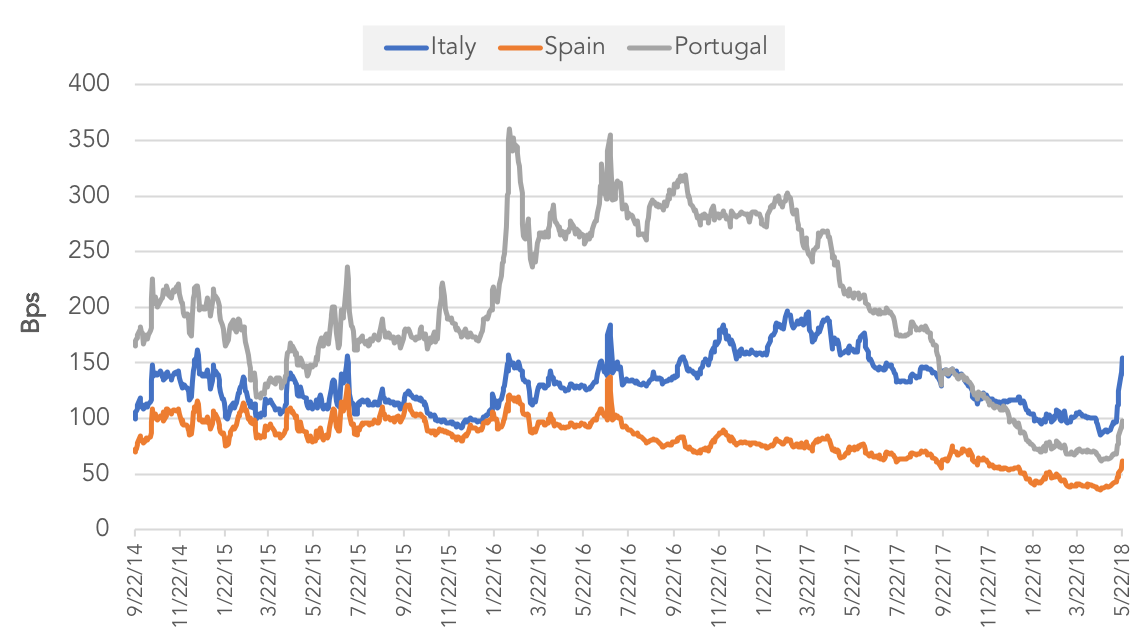
Unsurprisingly, this has been received badly by the credit markets. A Five Star/League government was viewed as a long shot both before and after the election, hence its impending formation has taken investors by surprise. CDS spreads were little moved in early March, the five-year hovering around the 100bps level. But since a populist government became probable spreads have widened sharply, breaching the 150bps level for the first time since last July. The anti-euro rhetoric has also had a knock-on effect elsewhere in the periphery, with Spain and Portugal’s spreads widening. Contagion, all but banished by Mario Draghi and the ECB, appears to be back.
Or is it? The recent bout of credit deterioration is certainly significant, but needs to be placed in a historical context. Italy’s spreads are still some way off the near 200bps levels reached in Q1 2017, when France was the main source of political risk. Spain and Portugal have both rallied considerably and are nowhere near losing the gains they made during this period. Talk of contagion, while not dismissed lightly, seems to be premature.
If the coalition manages to assuage the concerns of the Italian president and form a government, they may find Bismarck’s words as relevant as ever. A thin majority will make it difficult to pass domestic legislation, never mind take on the might of the EU. There may well be a case for looser fiscal policy in the eurozone – despite the objection of 154 German economists – but it seems unlikely that the EU would risk losing credibility in a face-off with a populist government, especially one with a 130% debt/GDP ratio. Short-term spread action is destined to be volatile given the plethora of uncertainty, and opens up a number of opportunities for relative value strategies. Market participants will be looking at CDS-bond basis, ISDA basis and the difference between iTraxx Europe and Senior Financials. We will be looking at these strategies in more detail over the coming weeks.
Contact: Gavan Nolan
Gavan.Nolan@ihsmarkit.com
Latest news
Direct lending M&A declines QoQ and YoY except in upper middle market
M&A activity declined 12% in the third quarter of 2026 to 296 deals, from 336 recorded in the second quarter.