



The private equity industry has matured quite a bit over the years. The most visible marker is the handful of firms that have gone public, despite the public market’s difficulty in valuing the complex, variable cash flows that are inseparable from the PE model. But every firm earns management fees, and publicly traded ones are thought to lean heavily on those fees as a way of goosing their own share prices. One way to boost management fees is to raise bigger funds, and, if possible, more big funds than they otherwise would raise. Higher AUM means more recurring revenue for shareholders. To critics, that means public PE firms are incentivized to “maximize short-term returns at the expense of long-term growth.” Larry Fink made that remark—echoed by many—though it should be pointed out that Blackstone gave Fink a boost when he got BlackRock off the ground, way back in 1988. Can’t we say that both firms prioritized long-term growth in their own ways?
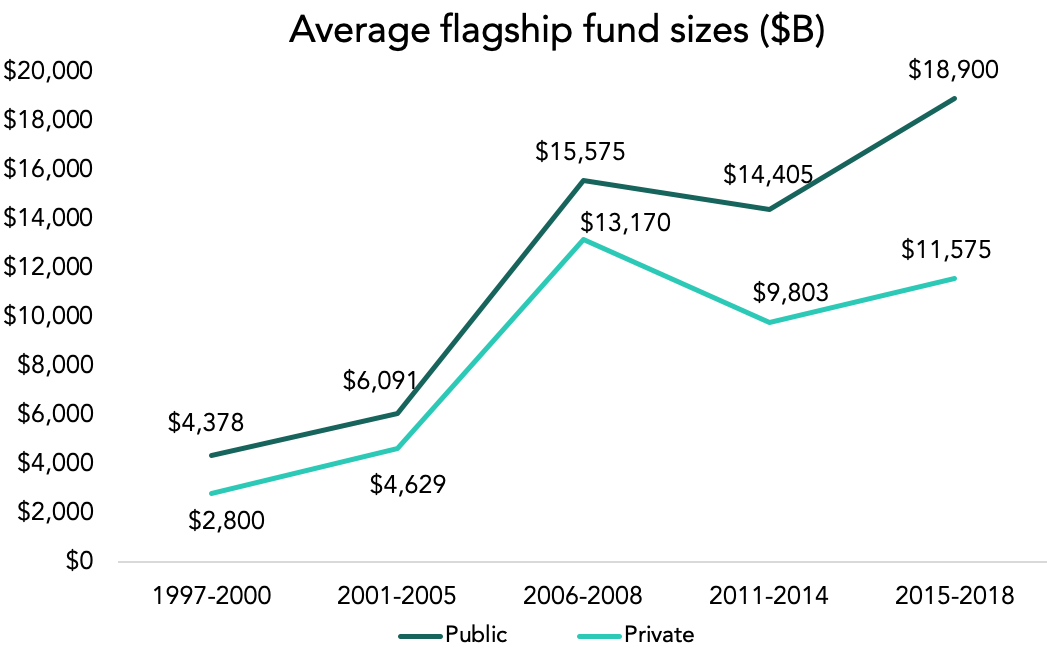
Á la Fink, do publicly traded PEGs look to boost short-term profits more than their private counterparts? In an upcoming analyst note, we compared a cohort of public firms (Apollo, Blackstone, Carlyle and KKR) to four still-private firms with similarly sized flagship funds (Advent, Bain, TPG and Warburg Pincus). When we compared pooled horizon IRRs for both buckets, we actually found higher returns at the 10-year and 15-year marks, and significantly higher returns at the 3-year mark. In a sense, we can say both sides have a point. Short-term returns are much higher for public PEGs (about 4 percentage points), but the longer term returns are also higher. The four private firms, collectively, did boast better TVPIs on average, likely a result of longer fund lives. We also found the four public firms have been returning capital at a quicker pace of late, despite their drawdown rates declining across the board. Perhaps the most visible difference between the two is how they reacted following the financial crisis. It should be noted that only one of them (Blackstone) went public before the crash, with Carlyle being the last to IPO in 2012. Still, the four firms that did go public were more consistent in their fundraising in the aftermath, and their flagship funds today are larger than they were pre-crisis. The same can’t be said (on average) on the private side. They all used to be discussed in the same breath ten years ago, but the now-public firms are starting to distance themselves from those that opted to stay private.



Latest news

European Mid-Market Direct Lending Margins Face Steady Compression Since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026, reaching an average of 553bps over reference rates, up from 542bps in the first quarter.

US Leveraged Loan Issuance Rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.