



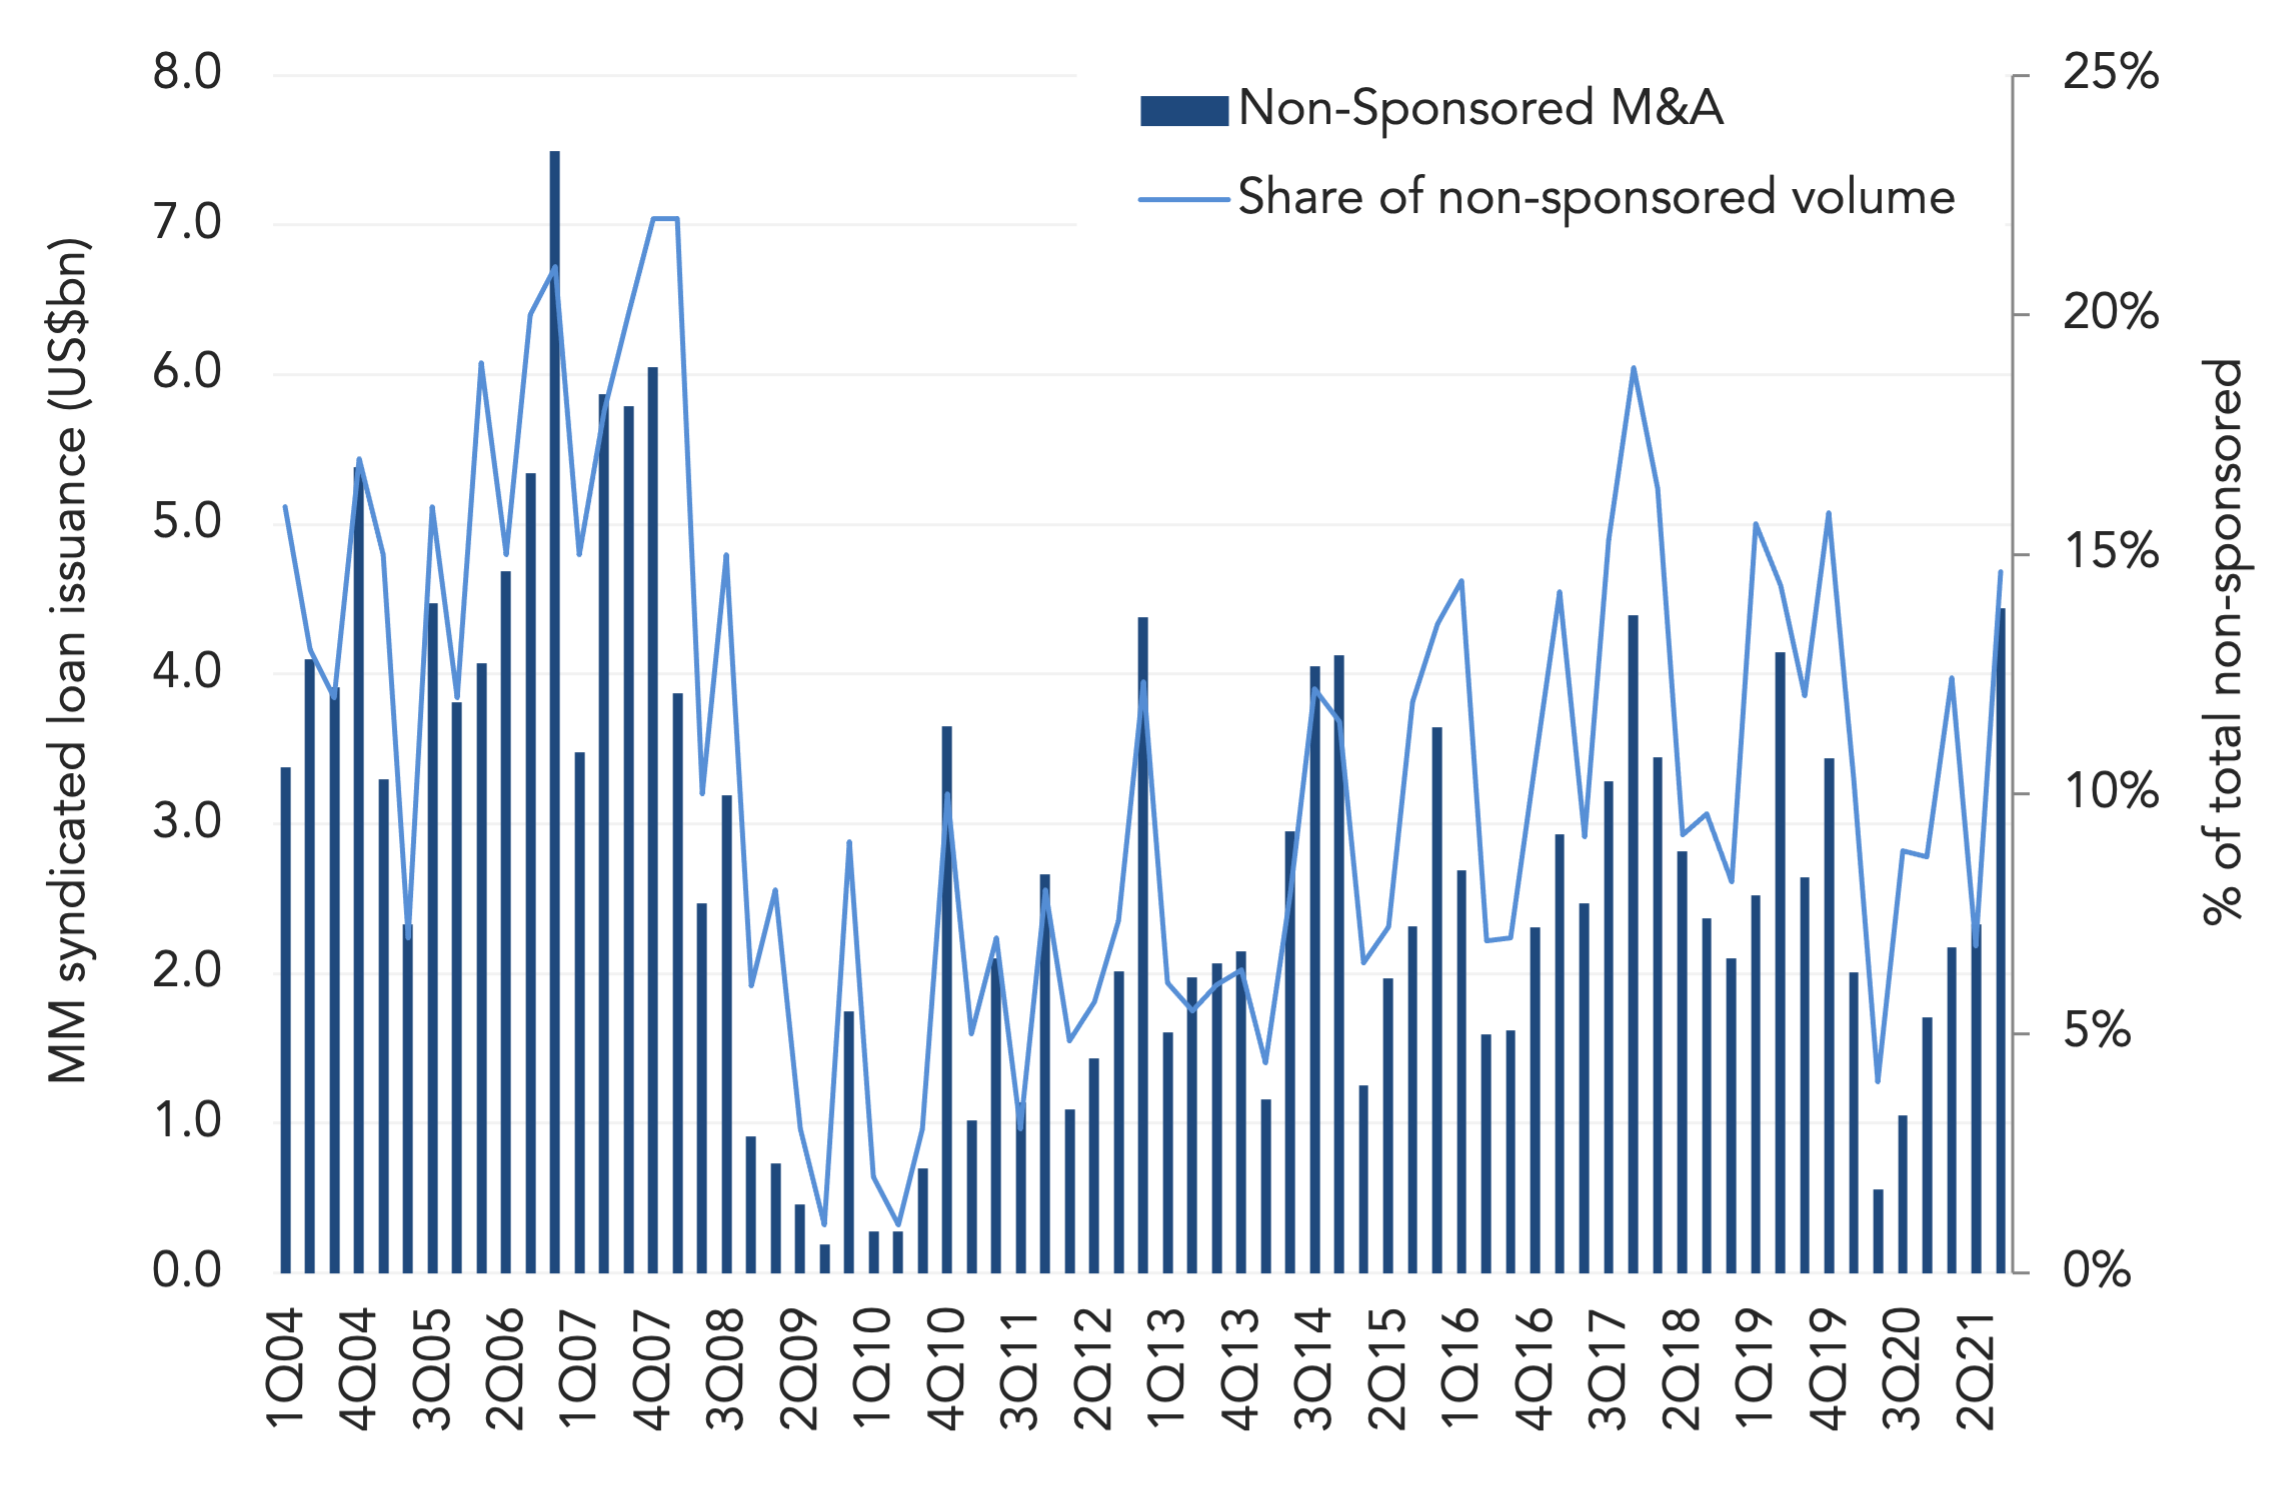
The non-sponsored middle market added another strong quarter to the books. While issuance was slightly down from 2Q21, it was a very busy summer with total volume of US$30.3bn in 3Q21. This was the highest level for a third quarter since 2014.
Moreover, new money lending hit its highest quarterly level since 2006. US$4.44bn of new money lending came from M&A activity, just above 4Q17’s US$4.39bn, which represented the highest post-financial crisis level. Half of the banks that responded to Refinitiv LPC’s 3Q21 lender survey, said that increased M&A kept them busy in 3Q21, up from 36% in 2Q21.
However, very high purchase price multiples, competition from sponsors and cautious business owners are still factors hindering M&A activity in the space. While bankers say that they are seeing increased activity, they are very far from “knocking it out of the park” and competition for deals remains very aggressive.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
