


Despite some inflation effects being felt, the overall picture is rosy for those operating in the market.
A new report from investment banking advisory firm Lincoln International highlights some of the trends from a strong year for deals in Europe in 2021.
One area for concern in previous Lincoln reports was that of covenant headroom, which measures the amount of room for manouevre before companies breach their covenants. This headroom was down to just 6 percent in the consumer sector in Europe in the fourth quarter of 2020 but had risen to a more comfortable level of 19 percent by the end of last year. This was on the back of equity injections and improved performance. In the other four sectors covered, headroom was ranging between 28 percent and 39 percent by the year end.
The report also gives a strong indication of portfolio companies’ improved operating performance. In the first quarter of 2020, some 20 percent of European valuations were at less than 90 percent of par according to fair value as companies experienced stress during the pandemic. By the end of last year, this had fallen to just 5 percent with the average valuation at 97.8 percent of par (the same as for the previous quarter).
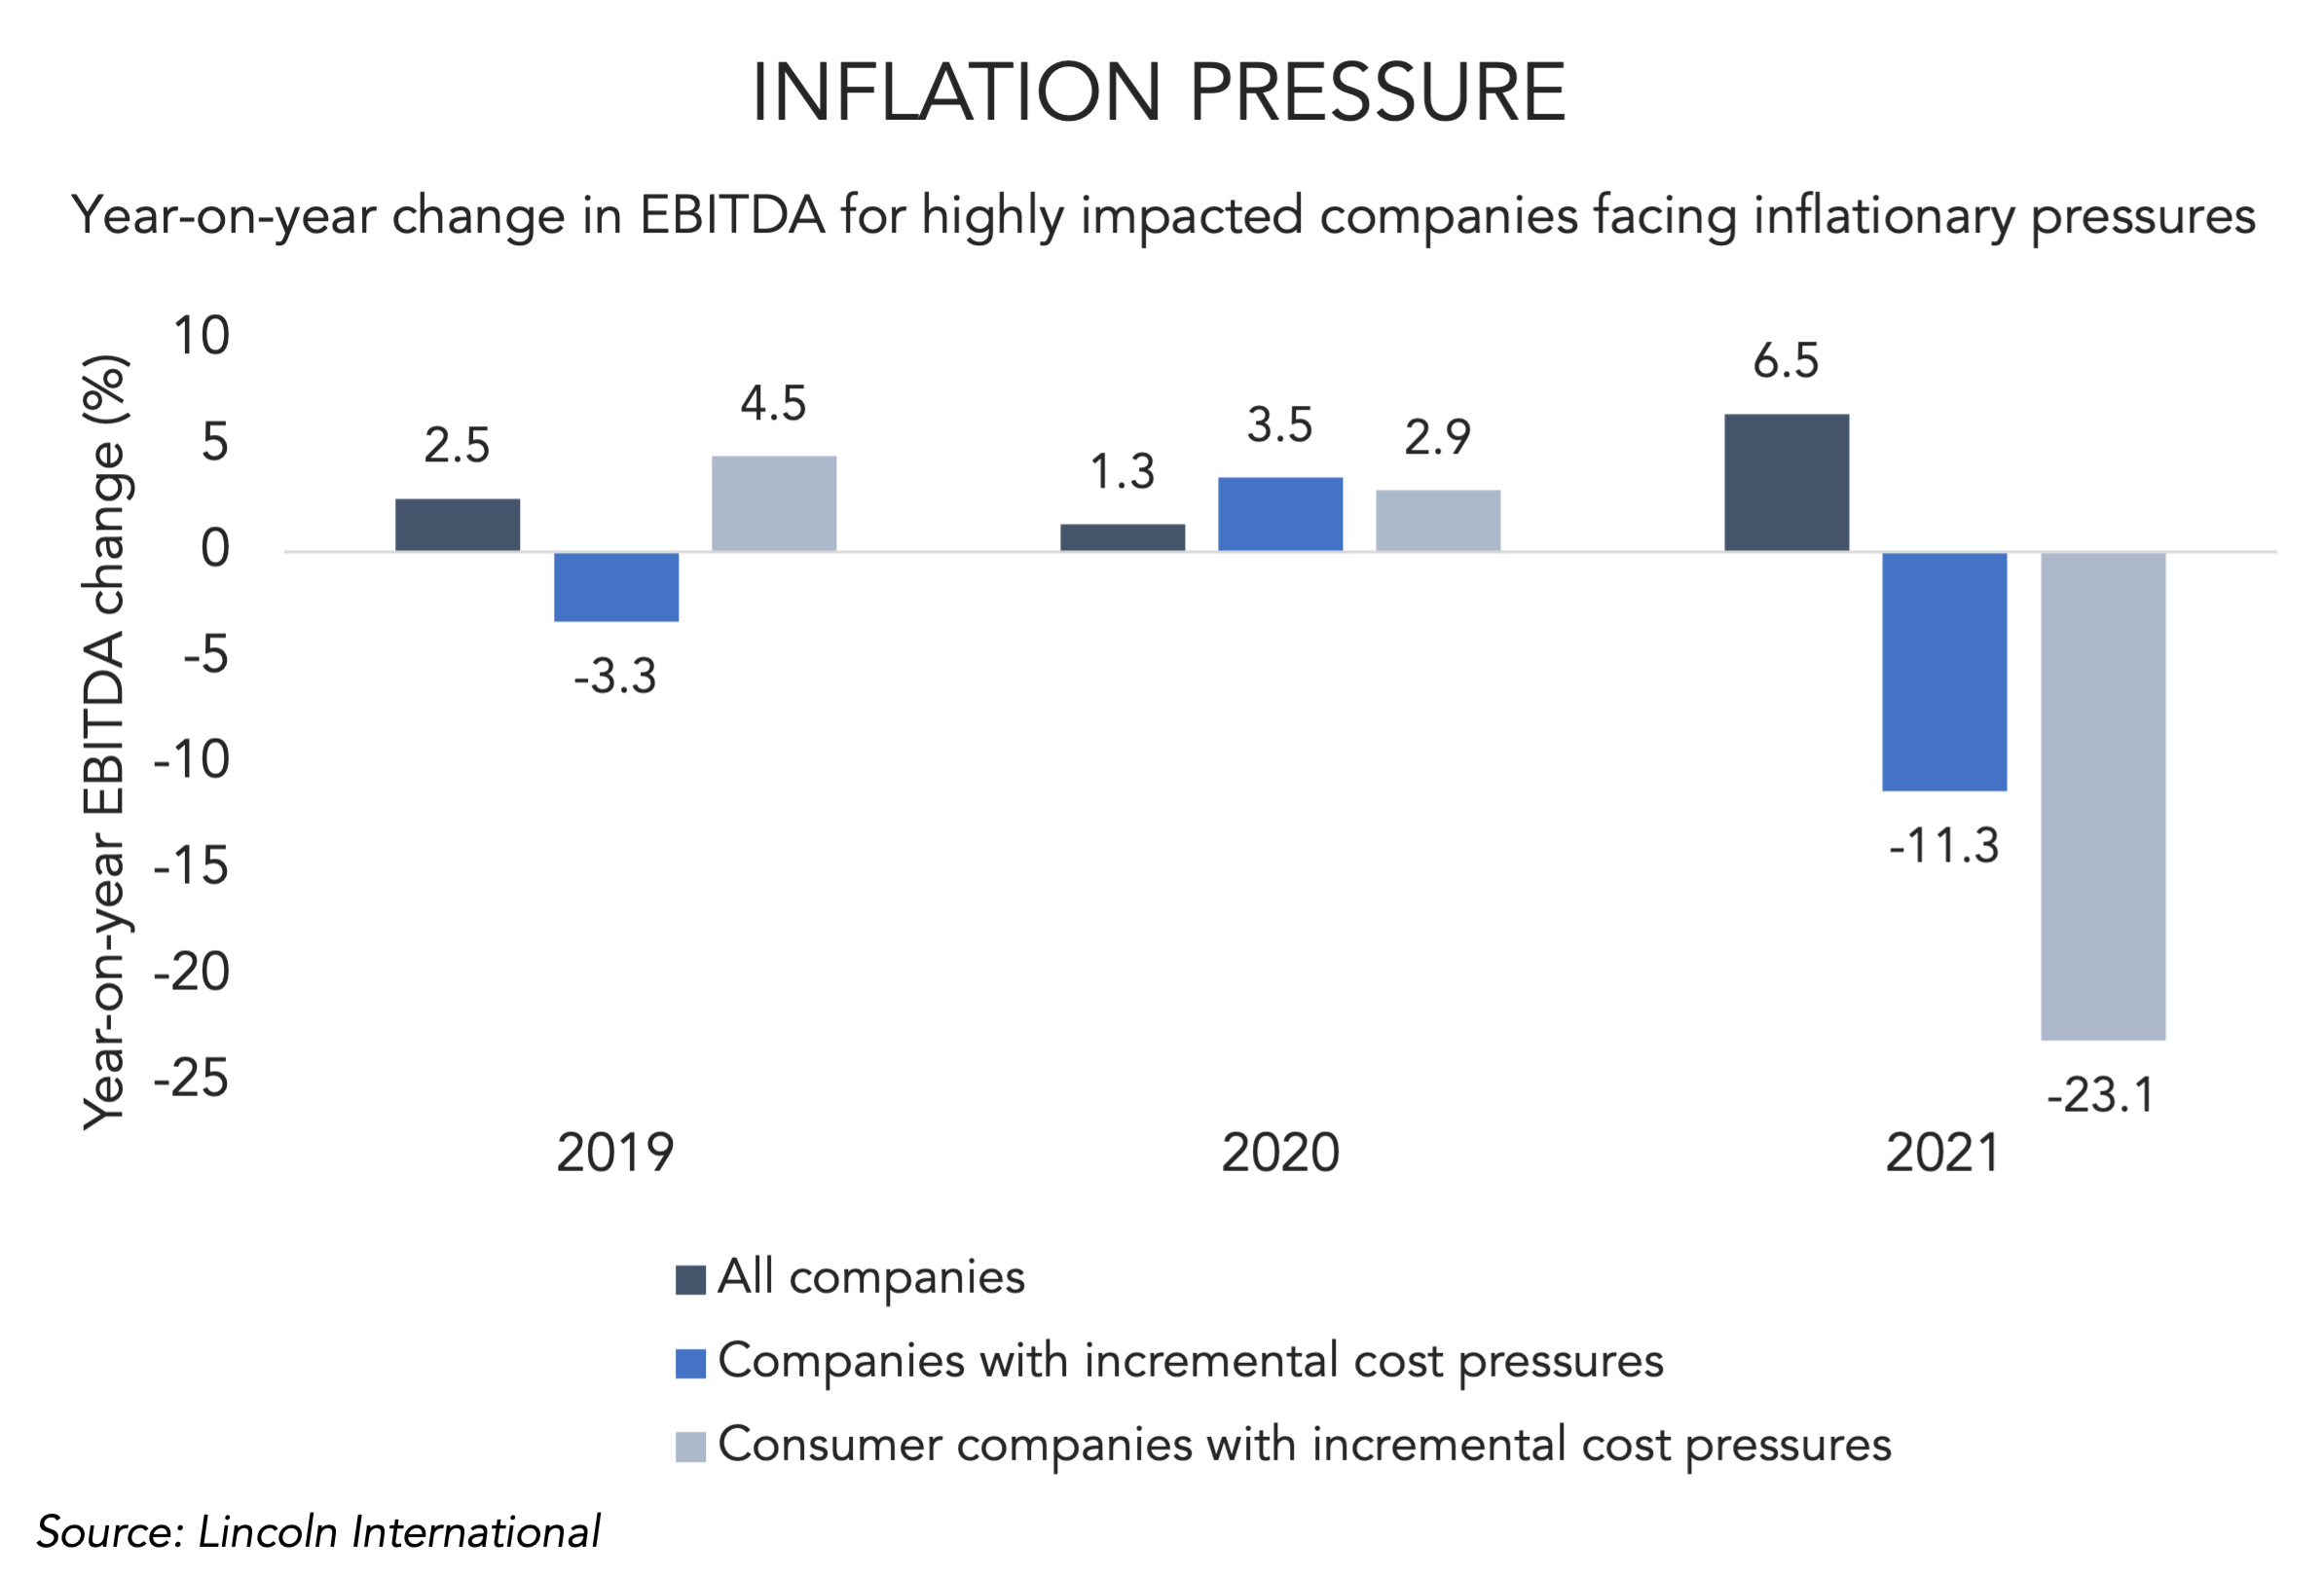
However, in a period of higher inflation, it’s perhaps unsurprising that some cost pressures are becoming apparent (see chart above). While the vast majority of companies in the study (843) saw EBITDA increase by an average 6.5 percent in 2021, 32 companies saw an average fall of 11.3 percent. Of these 32, 14 were consumer-focused companies which saw an average fall of 23.1 percent.
The overall picture is undoubtedly of a resilient European market, despite fears expressed in some quarters around the level of competition, apparent weakness of some deal structures and the amount of leverage. “Performance appears to be aligning with valuations and this looks sustainable assuming inflation doesn’t bite too hard into performance going forward,” says Richard Olson, Lincoln’s managing director in the UK and European valuations and opinions group.
(Past performance is no guarantee of future results.)




Latest news

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…