


A new study suggests its time for portfolio allocators to make some changes in the face of economic headwinds.
A recent piece of analysis from KKR suggests that the classic 60/40 stocks/bonds portfolio construction model may have had its day in the face of a challenging new environment. The model needs to find a way of incorporating alternative assets, the firm argues.
In a way, it seems like something of an uphill argument. As KKR admits: “In today’s world of heightened uncertainty in the global capital markets, the natural inclination for an asset allocator might be to go back to what has worked or seemed ‘safe’ in the past.” And what’s the safe impulse? None other than the traditional 60/40 mix.
Moreover, up to now, the performance of the traditional approach has been strong. Quoting Bloomberg data, the paper reveals that the 60/40 portfolio has delivered 10-year and three-year returns of 11.1 percent and 17.5 percent, respectively. Nothing much there to alarm portfolio allocators.
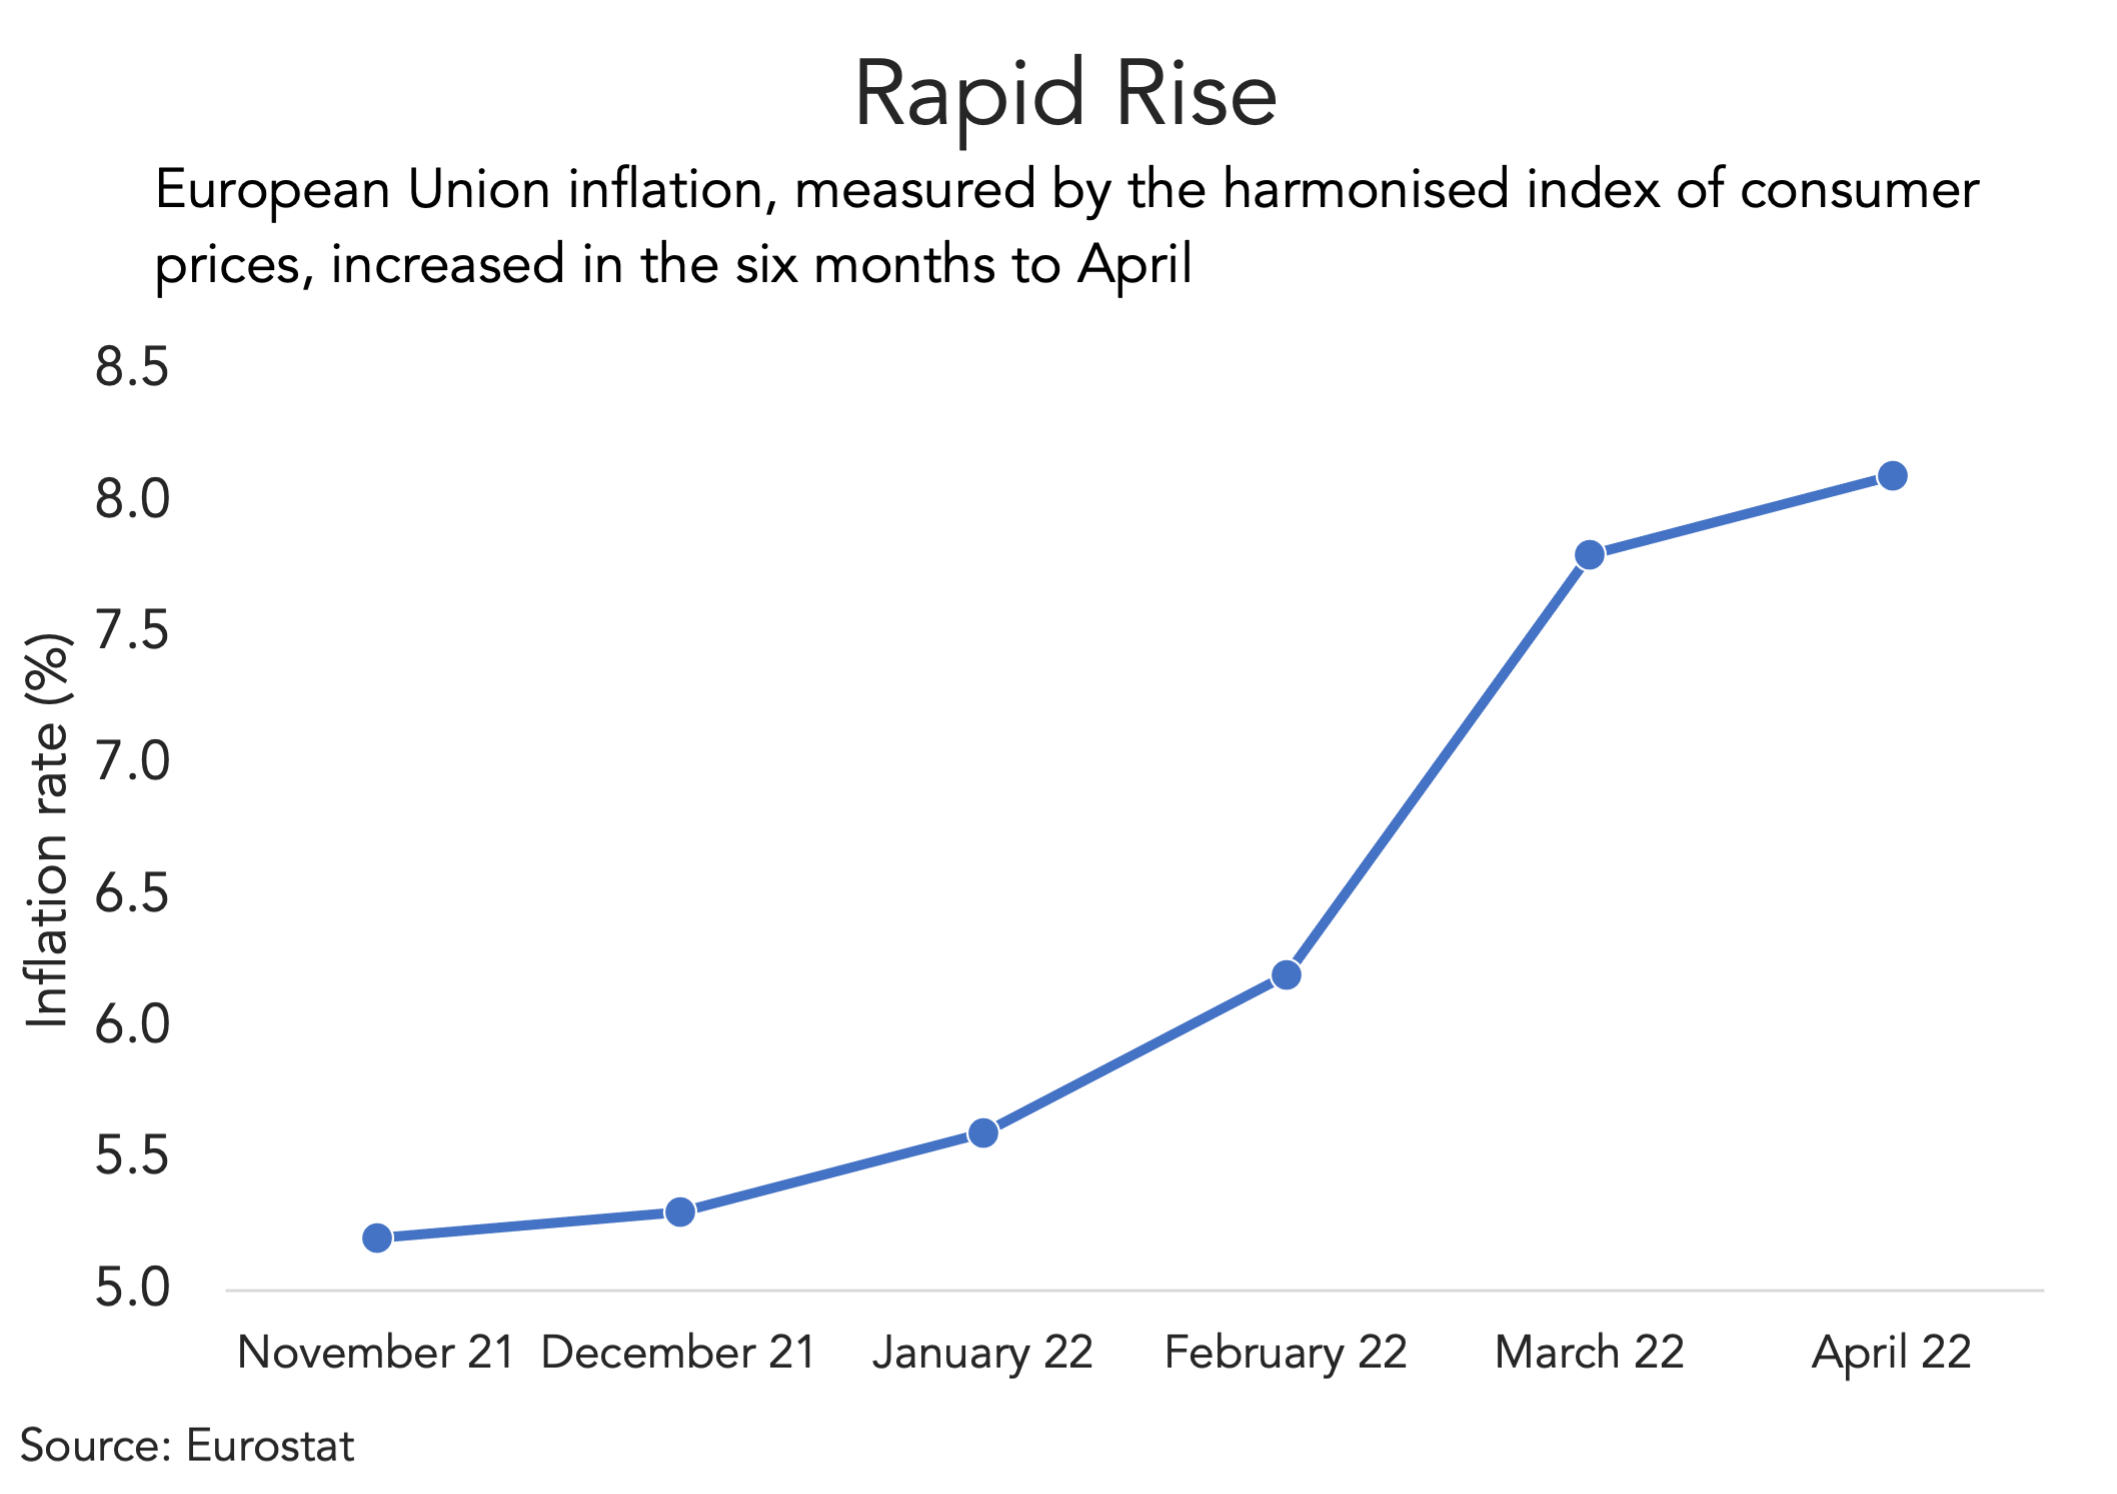
So why change? Perhaps because the past holds few clues to the future. Beset by rising interest rates, higher levels of inflation (see chart showing the trend in Europe, above), slower economic growth and heightened geopolitical risk, we have a new situation that KKR describes as one of “regime change”. It believes that 60/40 returns will be lower going forward as bonds “no longer serve as shock absorbers or diversifiers when paired with equities”.
The good news is that this means more alternative assets. KKR advocates something akin to a 40/30/30 model, in which 20 percent is taken away from the traditional equities component and given to private infrastructure and private real estate, while 10 percent is taken from the traditional bonds component and handed to private credit.
“It is not business as usual in the investment management business and now is the time for all investors to revisit their asset allocation game plan on a prospective basis,” says the paper, authored by senior executive Henry McVey. For alternative asset fundraisers, that may be uplifting news in uncertain times.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
