



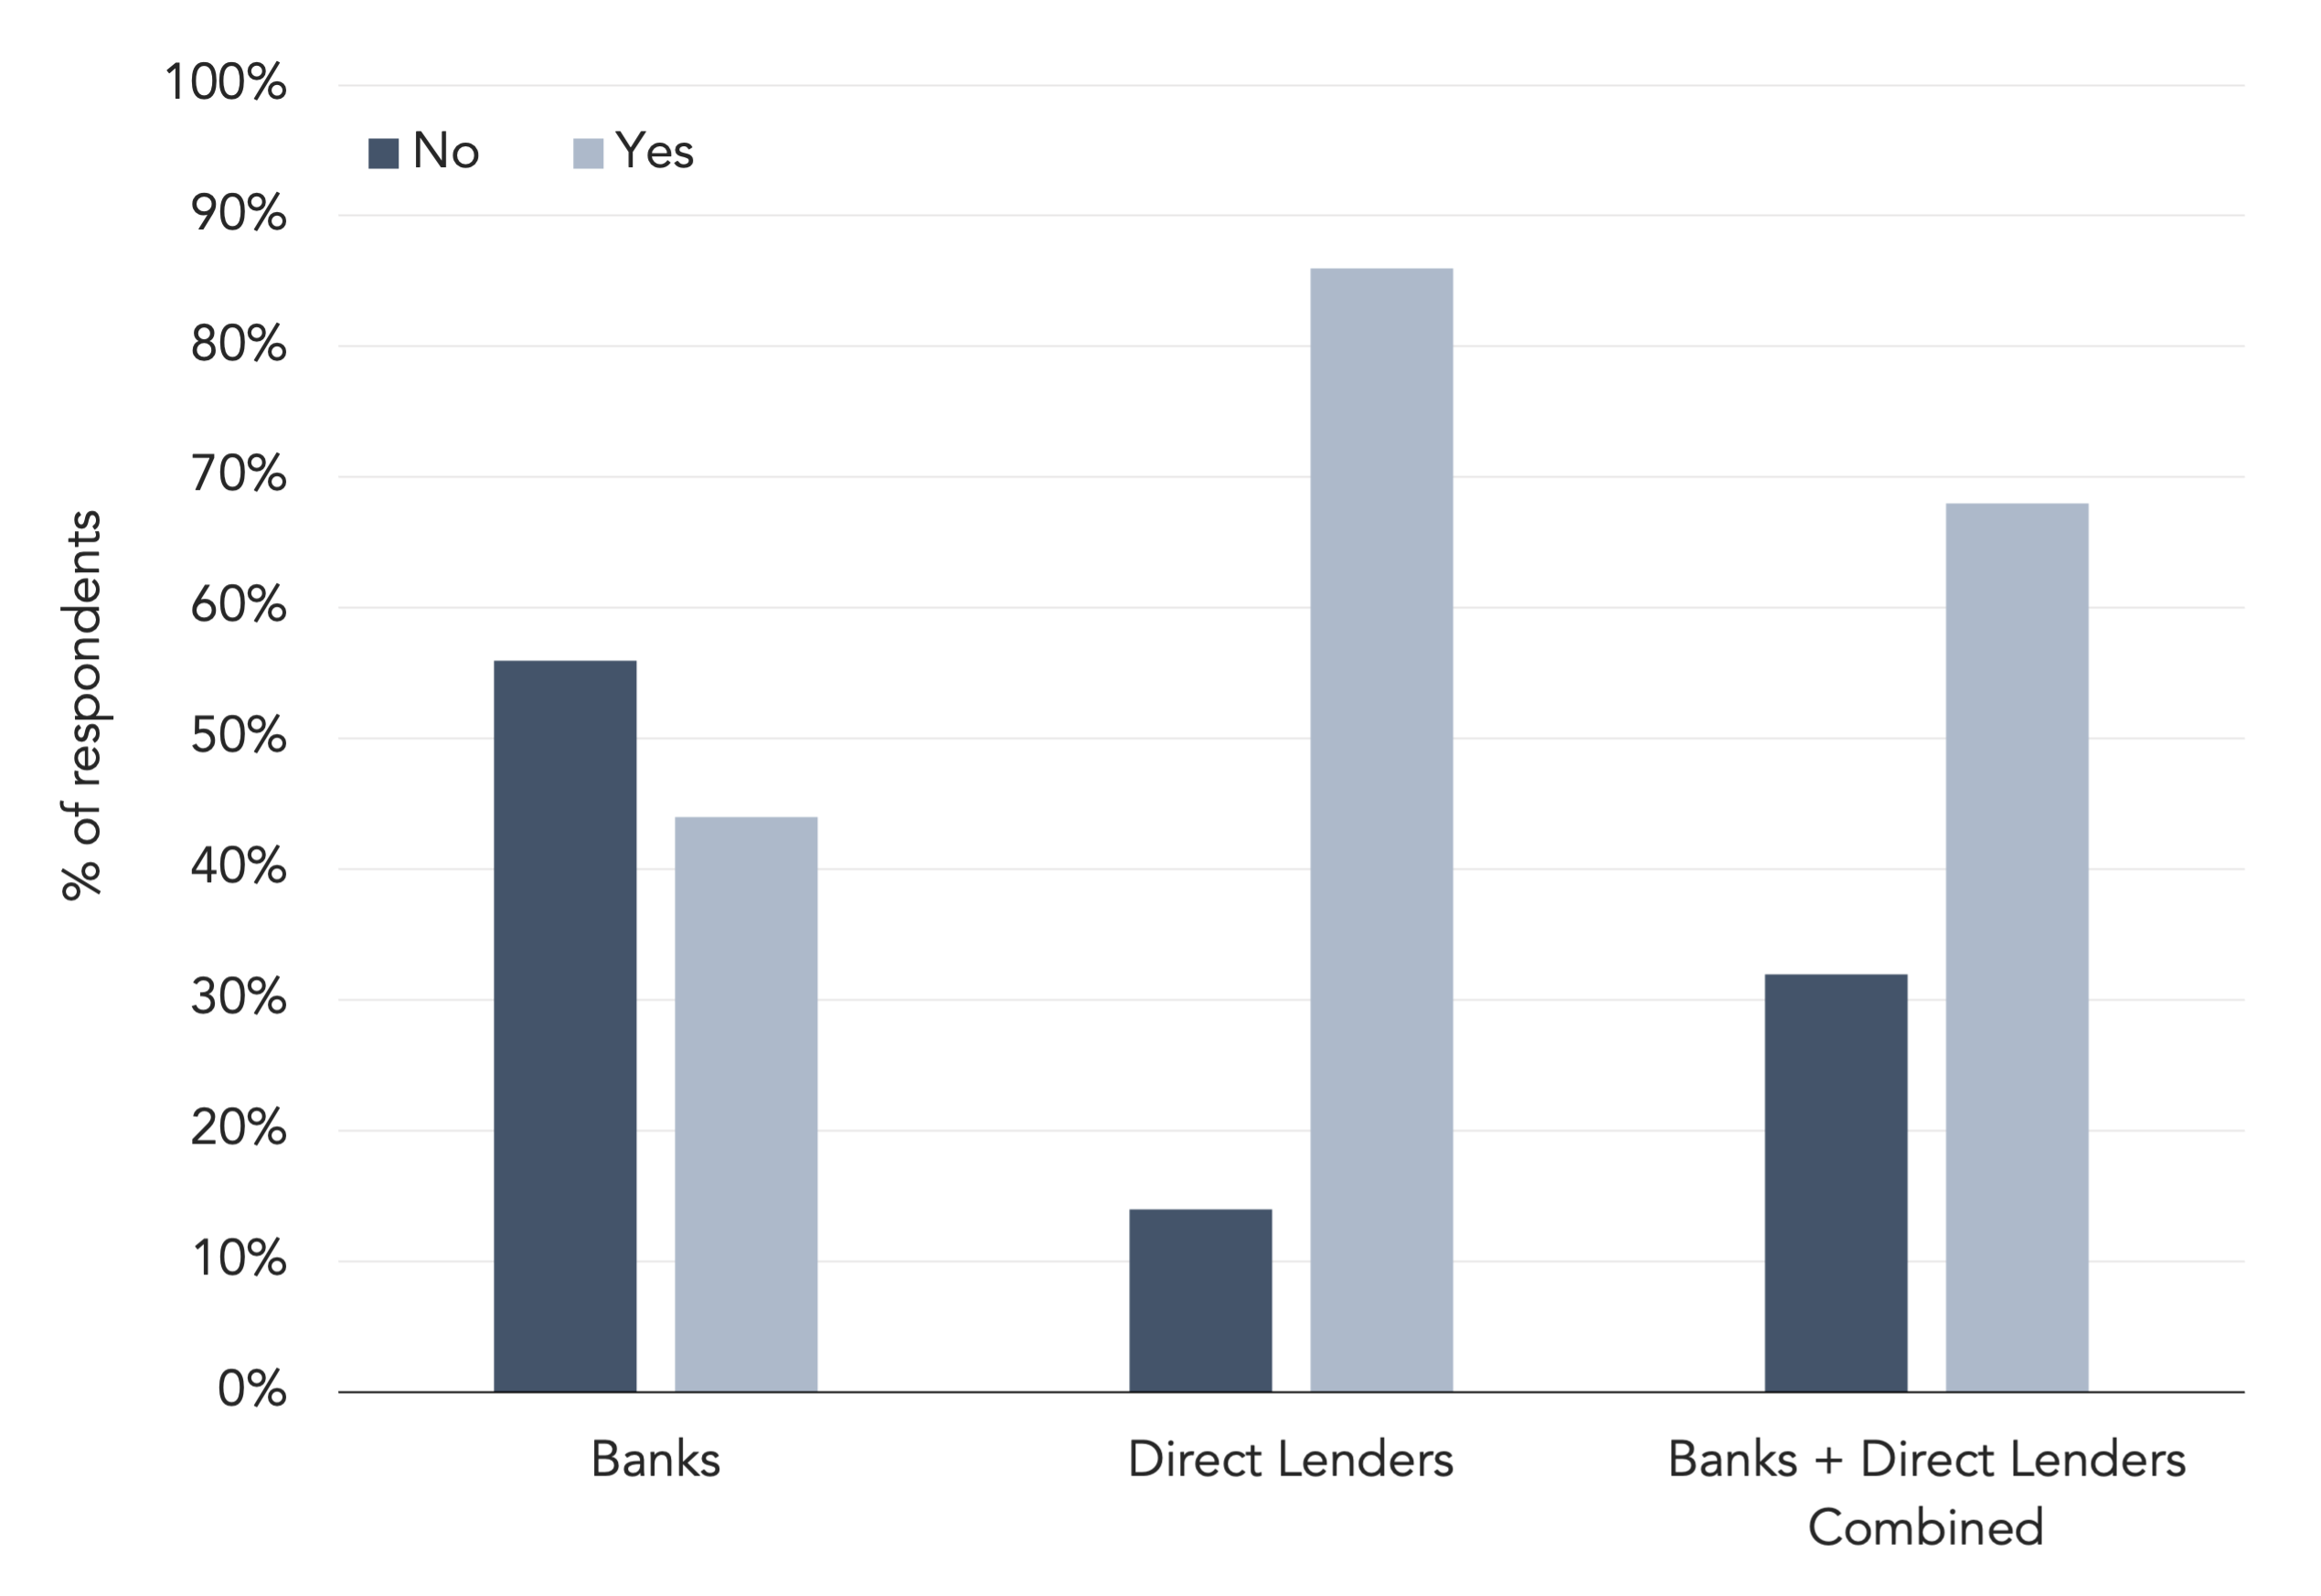
The direct lending market continues to be a popular go-to option at a time when the syndicated loan market has seen lower volumes due to heightened levels of volatility. Refinitiv LPC recently polled US middle market lenders, asking them: were you able to lend as much as you wanted to in 3Q22? Despite the pullback in the broadly syndicated market, a large 86% majority of direct lender respondents answered yes, they were able to lend as much as they wanted to this quarter. Factors given for direct lending deal activity in 3Q22 included: “dislocation in public markets,” “more attractive assets given more reasonable terms” and “larger lender groups due to lower hold sizes.” Meanwhile, a 56% majority of middle market bank respondents answered they were not able to lend as much as they wanted to in 3Q22. Most of the bank lenders cited the volatility and macroeconomic outlook as the main reason they were not able to reach their targets in 3Q22.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
