


Loan pricing tightens amid record demand from CLOs and transition away from LIBOR
Source: Debtwire Par
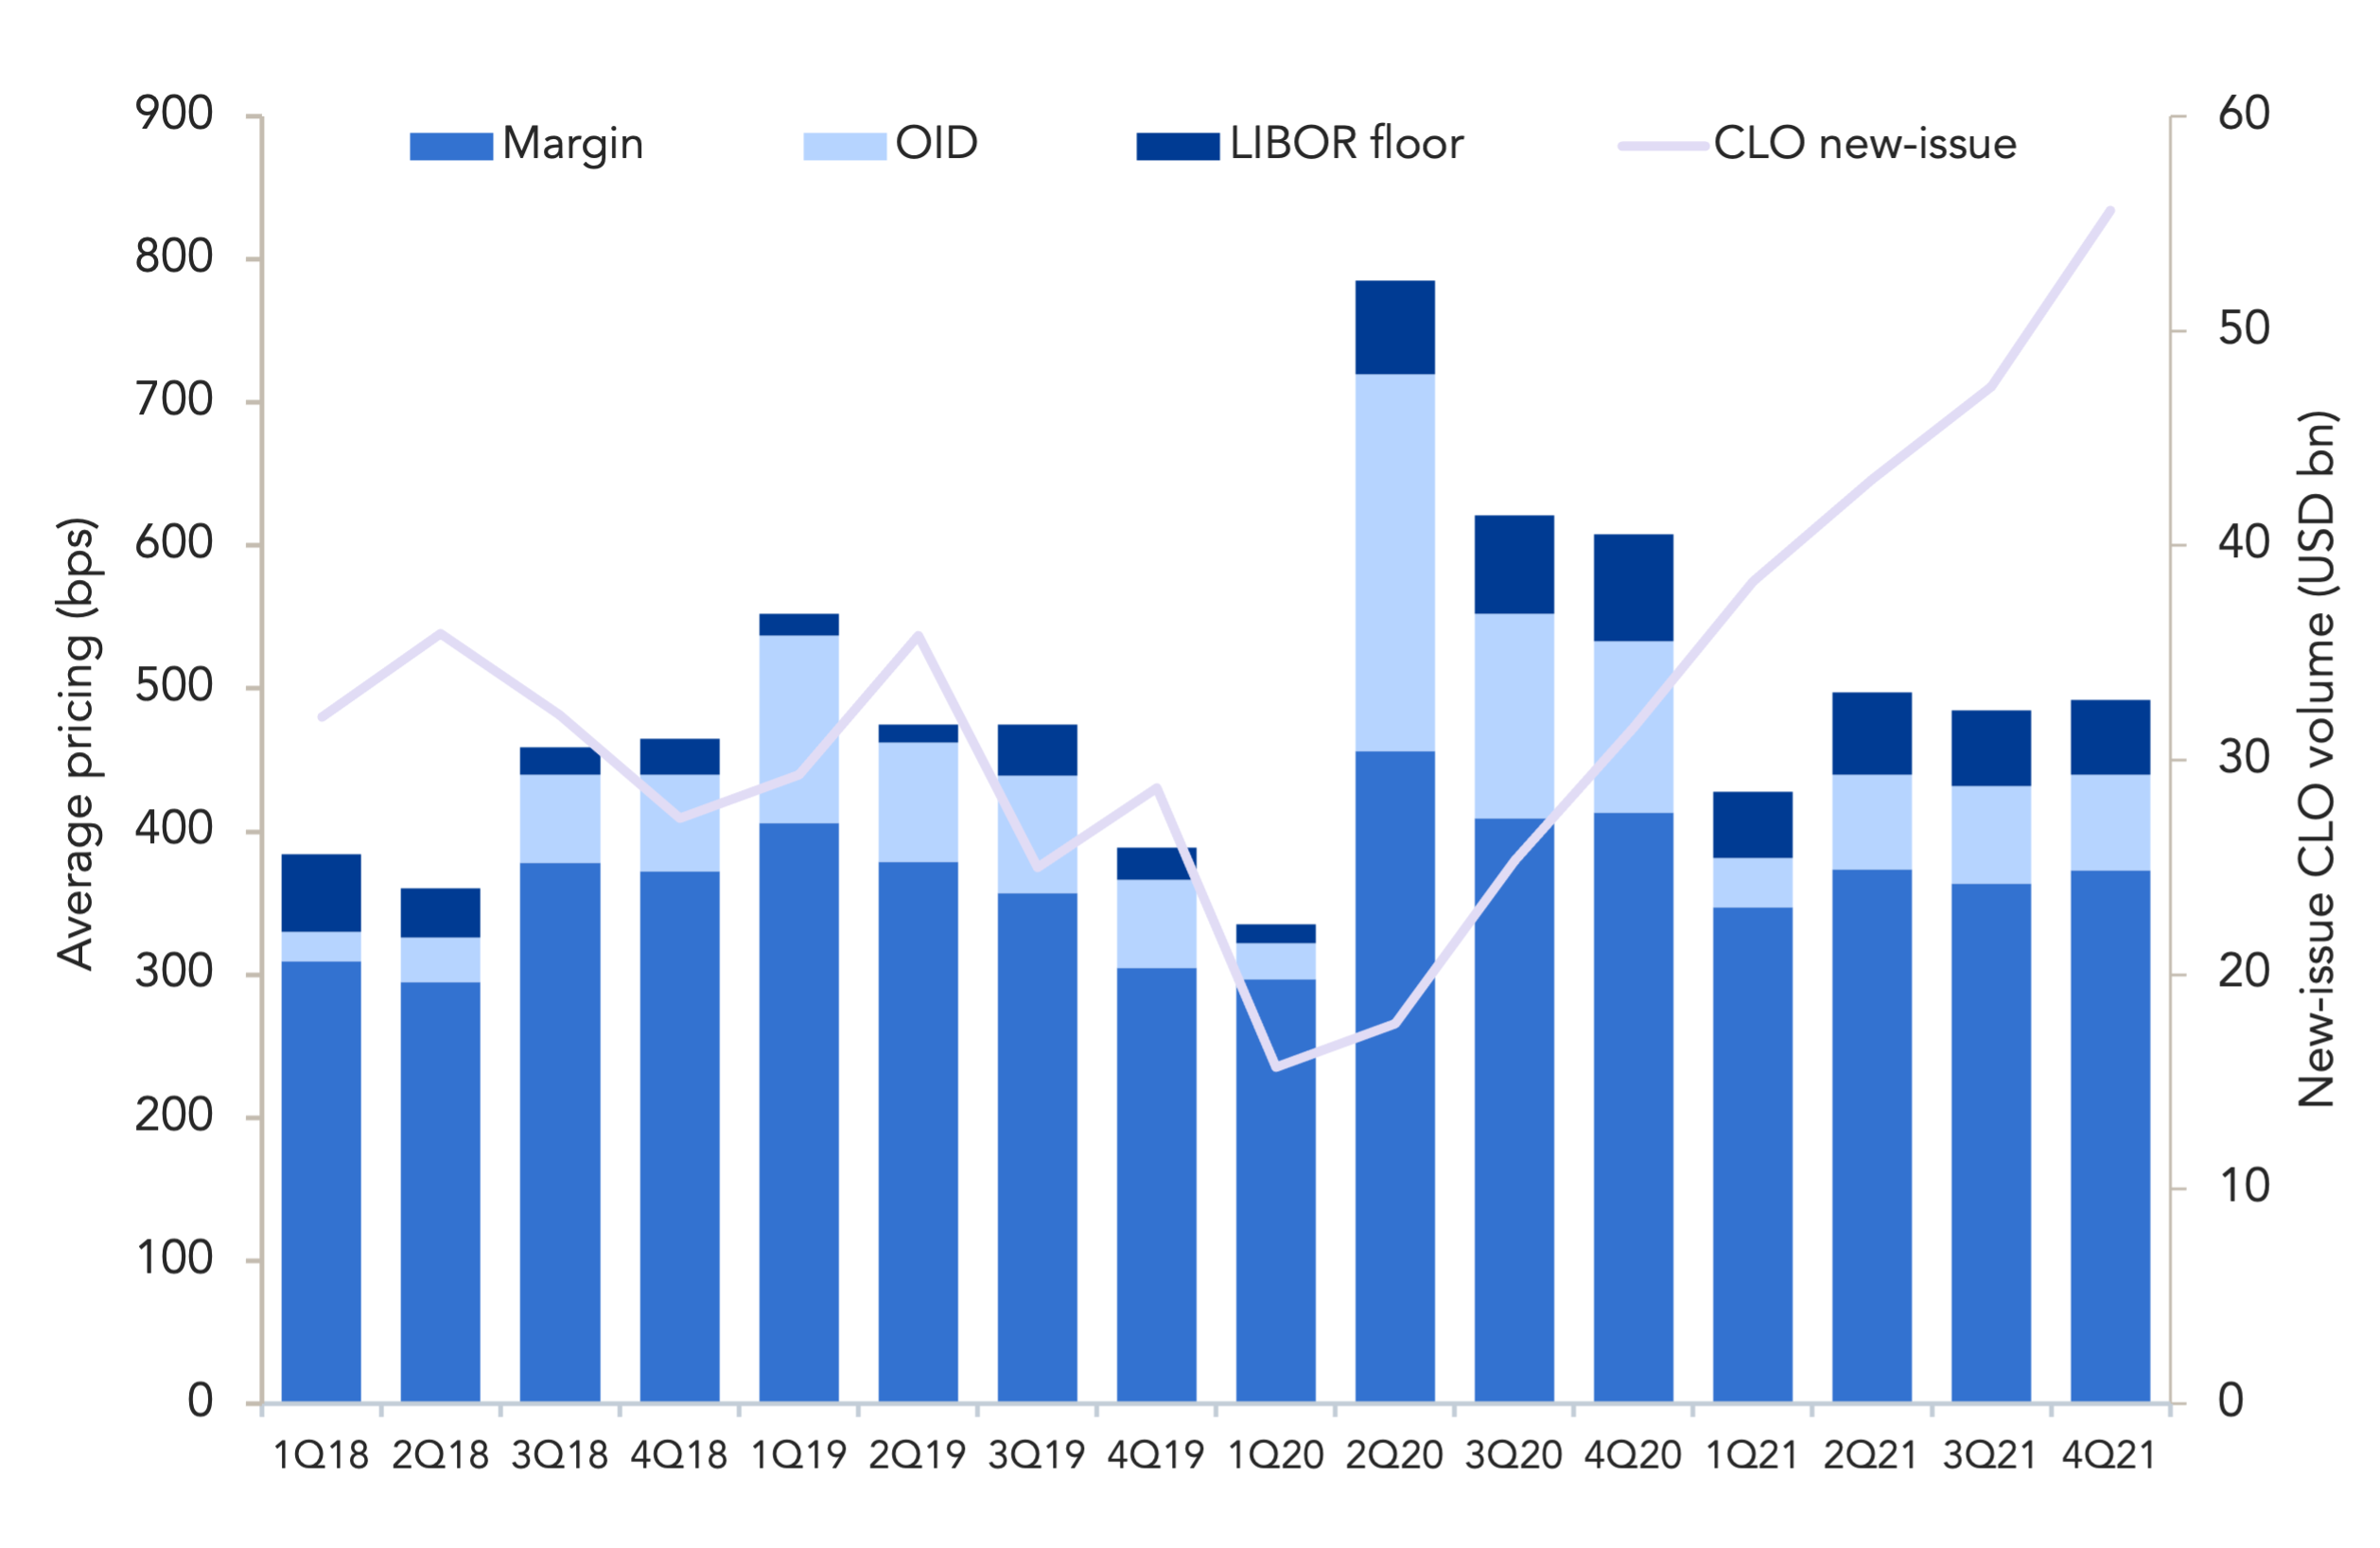
With the transition from LIBOR to SOFR (Secured Overnight Financing Rate) beginning to play out towards the end of the year, pricing dynamics led to a sharp tightening in loan yields from previous years. While the average margin on first lien institutional loans stands at 362bps for the year, on par with the 373bps level seen last year, the average yield has fallen to just 4.31% from 5.10%.
Compared to 2020, when LIBOR averaged 65bps, the 2021 average fell to just 16bps. As a result, LIBOR floors became more relevant in 2021, with the share of loans with a 0% floor decreasing to 20% from 49% in 2020. 50bps floors (42%) and 75bps floors (32%) have been the most common this year.
At the same time, average OID’s (original issue discounts) fell to an average of 55bps from 91bps in 2020. The cumulative effect was a significant tightening in overall loan yields. Further illustrating the accommodative lending environment was that loans priced tighter than initially guided at a significantly higher proportion than widening, with 218 tranches worth USD 196.3bn tightening from talk versus 81 tranches valued at USD 47.8bn flexing wider on the year.
Voracious demand from CLO’s certainly contributed to the low pricing environment – with record setting CLO issuance this year, competition for yield among investors has been steep. With approximately USD 184bn in new-issue (up 104%), USD 112bn refinancings (up 427%) and USD 126bn in resets (up 1087%), CLO creation saw a record year.
(Past performance is no guarantee of future results.)



Latest news
Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.8% as of…

Low August U.S. defaults reflects seasonal slowdown as market concern loans build
U.S. leveraged loan and high-yield default rates were unchanged in August 2026 at 3.9% and 2.8%, respectively, as seasonal conditions limited default activity, Fitch Ratings says.