


Source: Debtwire Par
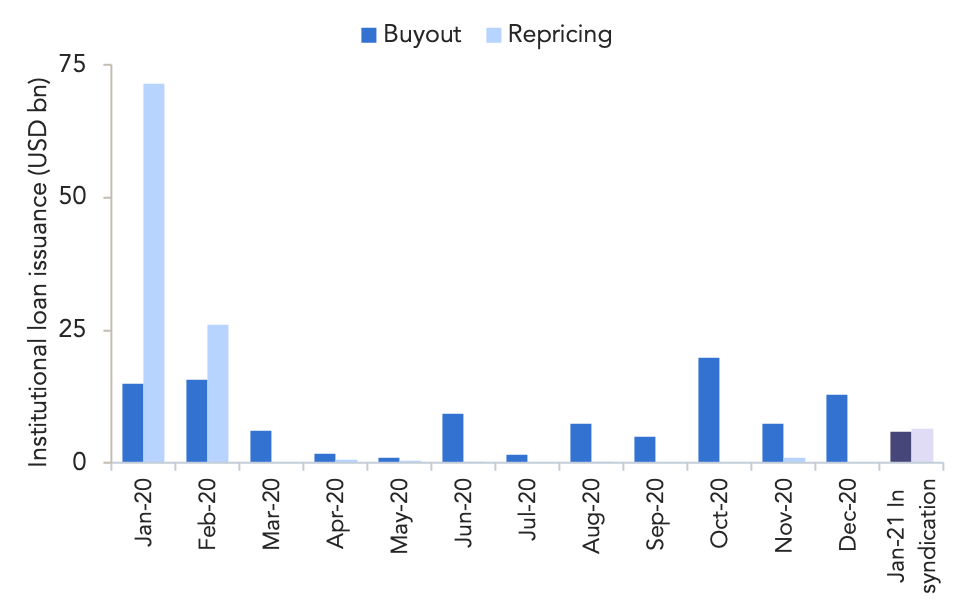
Institutional loans backing buyout activity climbed to USD 40.2bn in 4Q20 from just USD 13.8bn in 3Q20. Despite the late-year increase in deal flow, LBO institutional loan issuance ended the year at USD 103bn, down from the USD 119bn posted in 2019. Loan portfolio managers point to the drop in multi-billion dollar buyout financings in 2020 compared to prior years – there were 24 LBO financings with an institutional loan component greater than USD 1bn compared to 31 in 2019. On a more positive note, the number of USD 1bn-plus deals rebounded in 4Q20, reaching the highest level since 1Q20 and finishing the year on par with pre-pandemic levels seen in 2019.
This trend is continuing in early 2021, as the syndicated institutional loan pipeline currently includes over USD 5.9bn in buyouts across eight deals. Of these transactions, two fall into the billion-plus category, though both represent sponsor-to-sponsor transactions.
Truck Hero is currently in market with a USD 1.55bn TLB due 2028, which will support the company’s buyout by a private equity consortium led by L Catterton, with existing shareholders maintaining a stake. Meanwhile, PrimeSource is seeking a USD 1.095bn TLB due 2028 to fund Clearlake’s acquisition of the company from Platinum Equity and subsequent merger with Dimora Brands.
Repricing deals have made a return, representing USD 6.5bn of the loans currently in syndication after disappearing from the market as the coronavirus (COVID-19) pandemic struck in early 2020. In fact, the current pipeline of repricing deals exceeds the total loan repricing volume recorded in the March to December 2020 timeframe. That said, it is still eclipsed by the huge USD 97.6bn recorded in January and February of last year.
Ultimate Kronos Group leads the way, with a USD 2.945bn TLB repricing working its way through the market. The company plans to reduce pricing on the LIBOR+ 400bps (75bps floor) facility maturing in 2026 to L+ 325bps. Iridium Communications is similarly repricing a USD 1.638bn TLB due 2026. The Deutsche Bank-led effort is talked at L+ 275bps-300bps with a 99.75 OID, down from current pricing of L+ 375bps.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
