


Source: Debtwire Par
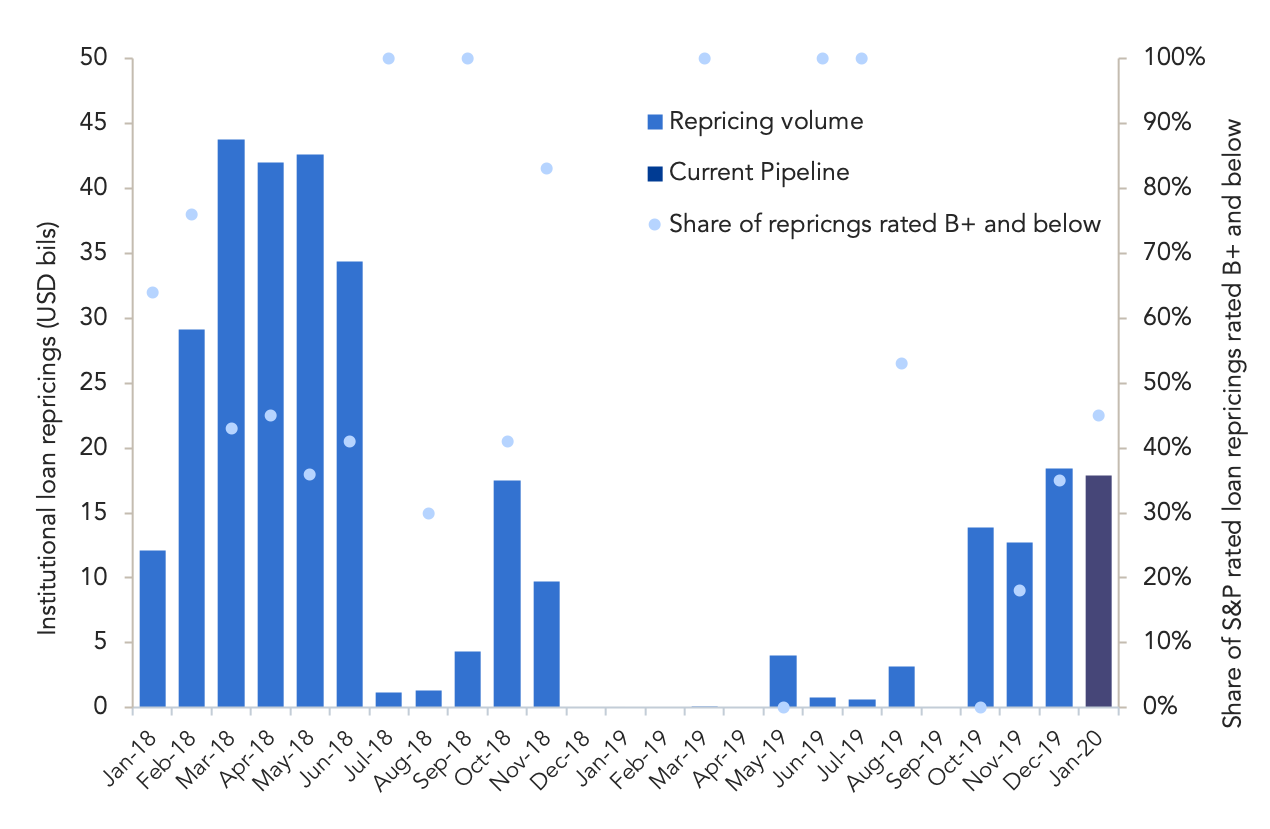
Institutional loan repricings have continued their hot streak into 2020, with USD 17.9bn of repricings in the syndicated loan pipeline as of January 15. This represents roughly half of all institutional loans currently in the syndication phase. 2019 was a light year for loan repricings, registering just USD 54bn compared to the USD 238bn recorded in 2018. Of that figure, 4Q19 accounted for USD 45bn, significantly outpacing repricing volume through the 1-3Q19 period.
Notably, there has been a shift towards single-B rated names testing the market for repricing potential so far in 2020. At the onset of the recent pick-up in repricing activity in October 2019, it was BB rated loans that dominated and they often repriced to the L+175bps area, reflective of investor appetite for higher quality credits at the time.
In contrast, four single-B loans accounting for 45% of pipeline repricing volume are now in syndication, including B+/B1 rated LifePoint Health (USD 3.55bn TLB talked at L+ 400bps), B/B1 rated Kindred at Home (USD 2.54bn TLB talked at L+ 325bps), B+/B1 rated Whatabrands (USD 1.33bn TLB talked at L+ 275bps-300bps) and B+/Ba2 rated Avantor (USD 677 TLB talked at L+ 250bps). Buysiders have attributed this growing share of single-B repricings to pricing dispersion in this rating category and a lack of new money deal flow.
Contact: Vincent Daigger



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.