


Source: Debtwire Par
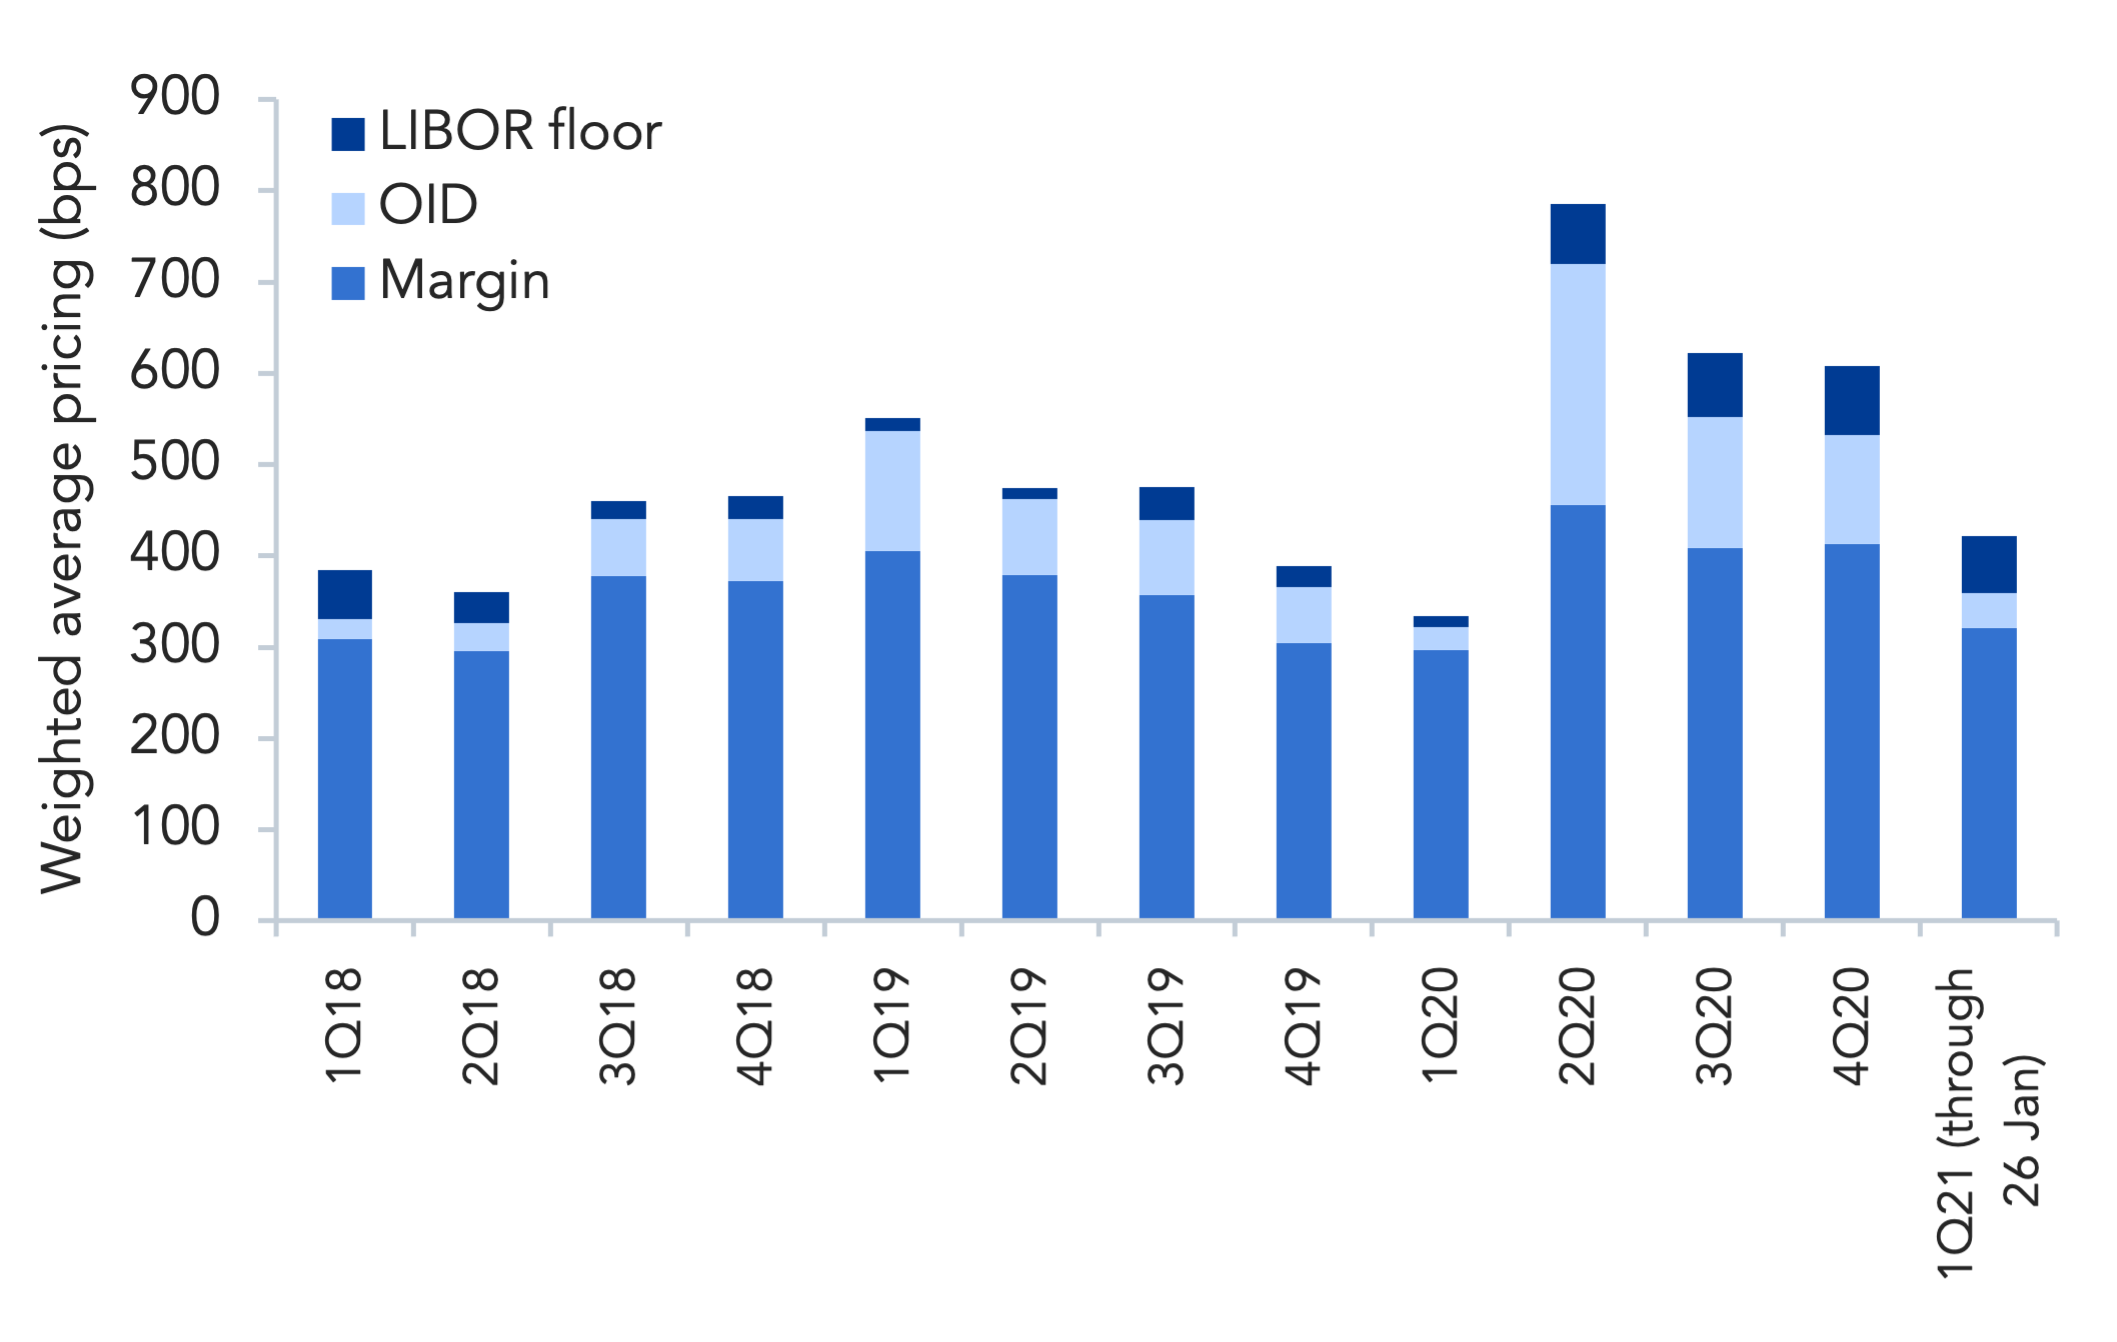
Strong demand for loans has pushed pricing sharply tighter in January, with the first-lien institutional benchmark hitting its lowest level since 1Q20. So far this month, margins have averaged Libor+320 bps, down from L+ 413bps in 4Q20. Original issue discounts (OIDs) have also posted a pronounced tightening, with the discount declining to 39bps on average from 120bps in 4Q20. The trend of lower pricing is a theme across the ratings spectrum and reflects technical pressures and the recent risk-on environment across the financial markets.
The technical backdrop in the market has prompted borrowers to opportunistically cut pricing on their loans. In turn, there has been a surge in repricing activity this month, with over USD 10bn of institutional loan repricing in January and another USD 20bn-plus currently in syndication.
On the demand side, the CLO market has started the new year brightly, with USD 5.3bn pricing across 12 deals. On top of this, loan mutual funds & ETFs have turned the corner and posted inflows in recent weeks, pulling in over USD 2bn in the first three weeks of this year.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.