


Source: Debtwire Par
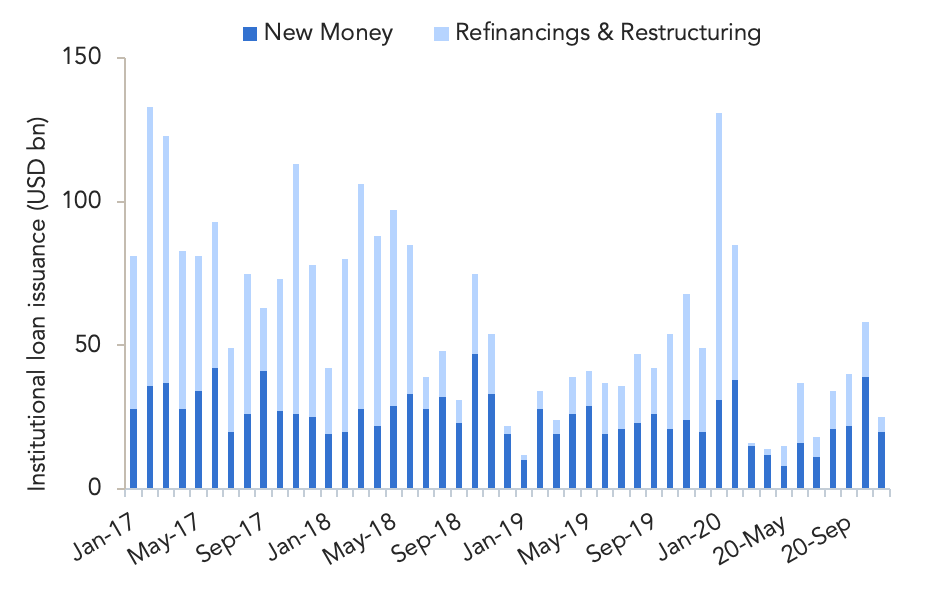
Institutional loan issuance dropped off in November, recording just USD 25.4bn this month, down 56% from the October figure. The month got off to a slow start thanks to uncertainty surrounding the US presidential election, registering just USD 5.8bn through 9 November, when Pfizer announced optimistic test results surrounding its experimental coronavirus (COVID-19) vaccine. The news, followed by several other positive vaccine test results, have since led to a rebound in lending, and significant secondary market price appreciation.
In the three-week span following Pfizer’s announcement, institutional loan issuance ticked up to USD 19.6bn, bringing the year-to-date figure to roughly USD 475bn, a 9% improvement over the year-ago level. Another positive sign for the market was the percentage of deals issued for new money purposes. While total new money lending has fallen from USD 39.2bn in October to USD 20.1bn in November, the proportion of deals issued for new money purposes increased to 80% in November from 65% in the previous month. The November figure is driven primarily by M&A transactions (USD 9.2bn) and buyout deals (USD 5.4bn), while dividend recap volume has tapered off to USD 4.1bn.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…