


Source: Xtract Research
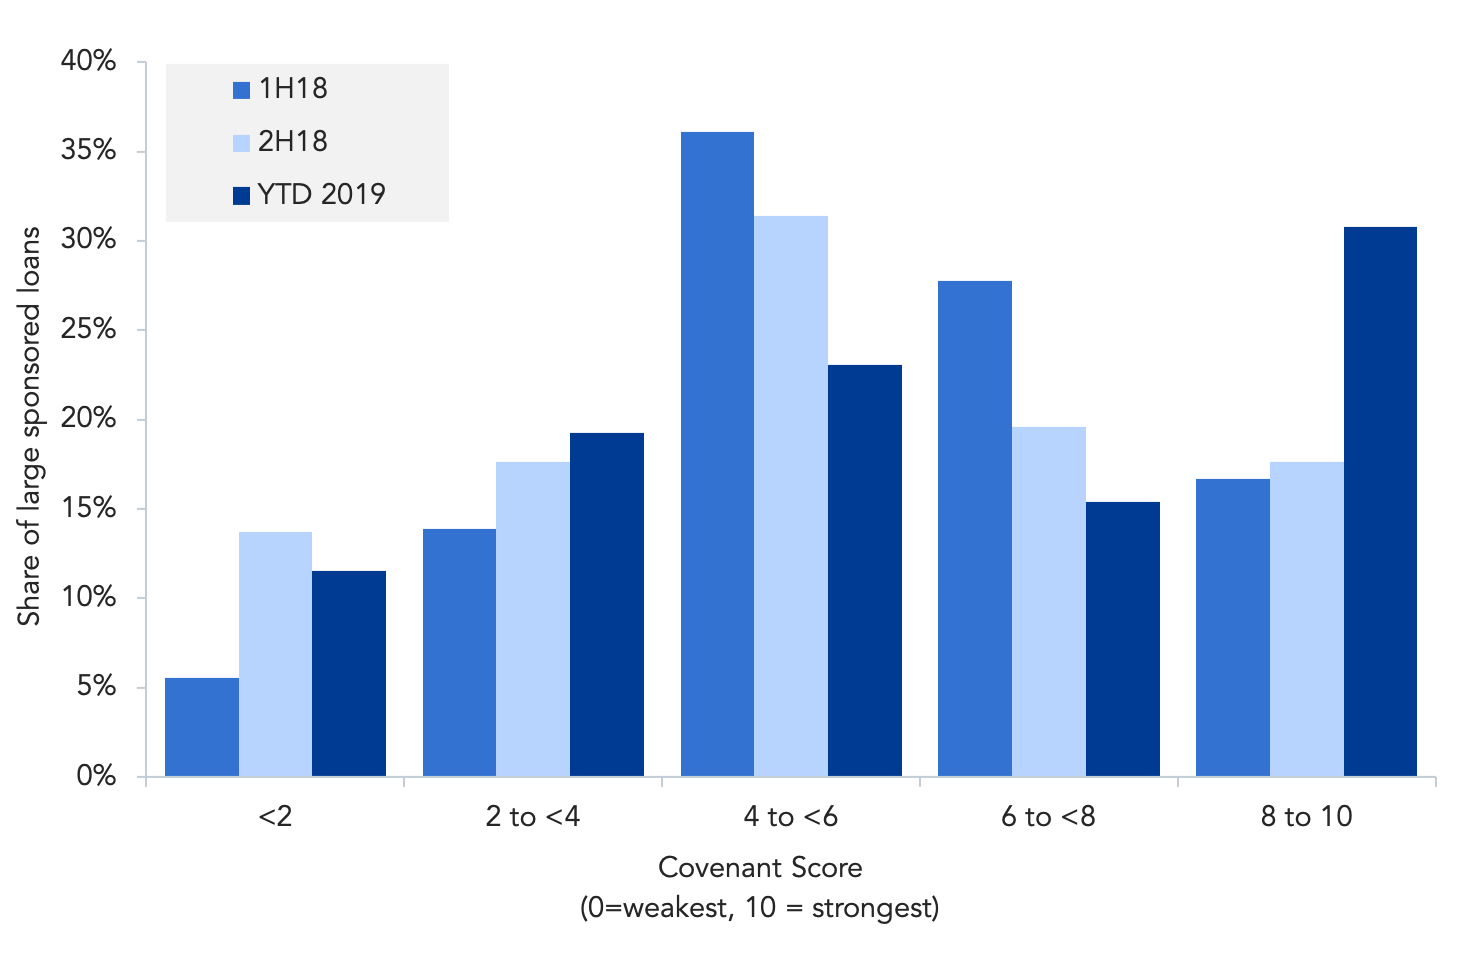
While loan covenant protections remain extremely weak by historical standards, some comfort for lenders is that they have shown relative improvement so far in 2019. Looking at Xtract Research’s new Covenant Scores (which rank leveraged loan covenant protections from 0-10, with 0 being the weakest possible covenant package and 10 being the strongest), the share of large sponsored deals with a score in the 8 and above category has climbed to 31% from 18% in 2H18 and 17% in 1H18. Examples of improved covenant provisions include: the decrease in the number of loans with uncapped EBITDA addbacks to 41% in 1Q19 from 69% in 1Q18; the increase in the number of loans with a maintenance financial covenant (23%); and a dramatic reversal in a borrower’s ability to invest on an unlimited basis in non-guarantor restricted subsidiaries, a permission now found in 36% of agreements, down from approximately 50% in the preceding two quarters.
But it’s by no means a major reversal, as the share of deals at the weaker end of the covenant spectrum (score <=4) still accounts for a hefty 31% of deals this year. This reflects that sponsors are still able to push the envelope on transactions that lenders find attractive and gain attractive terms.
Despite the relative improvement in covenant scores on large sponsored deals (opening EBITDA >=USD 100m), their average score of 5.4 in year-to-date 2019 reflects weaker covenant protections than those found in smaller sponsored deals (opening EBITDA <USD 100m), which have an average score of 6.1, and non-sponsored deals, which have an even better score of 6.9.
Digging deeper, the relative improvement in covenant scores this year can be seen across the spectrum of deals and terms but is often credit specific. In addition, it’s also reflective of deals in the upper middle market having trouble getting top tier aggressive terms.
Contact: Colm (CJ) Doherty



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.