


Source: Debtwire Par, Markit
Primary market pricing has jumped to its highest point since the coronavirus (COVID-19) pandemic sent shockwaves through the financial system in 2020, as inflation risks and ongoing uncertainty stemming from the war in Ukraine demand higher yields for investors willing to take on the additional risks. At 428 basis points (bps) in March, average margins on first-lien institutional term loans are at their highest mark since the 438bps average back in November 2020. Throughout 2021, borrowers had access to relatively cheap capital, as yield-starved investors were willing to accept lower payouts to put dry powder to work, helping drive issuance.
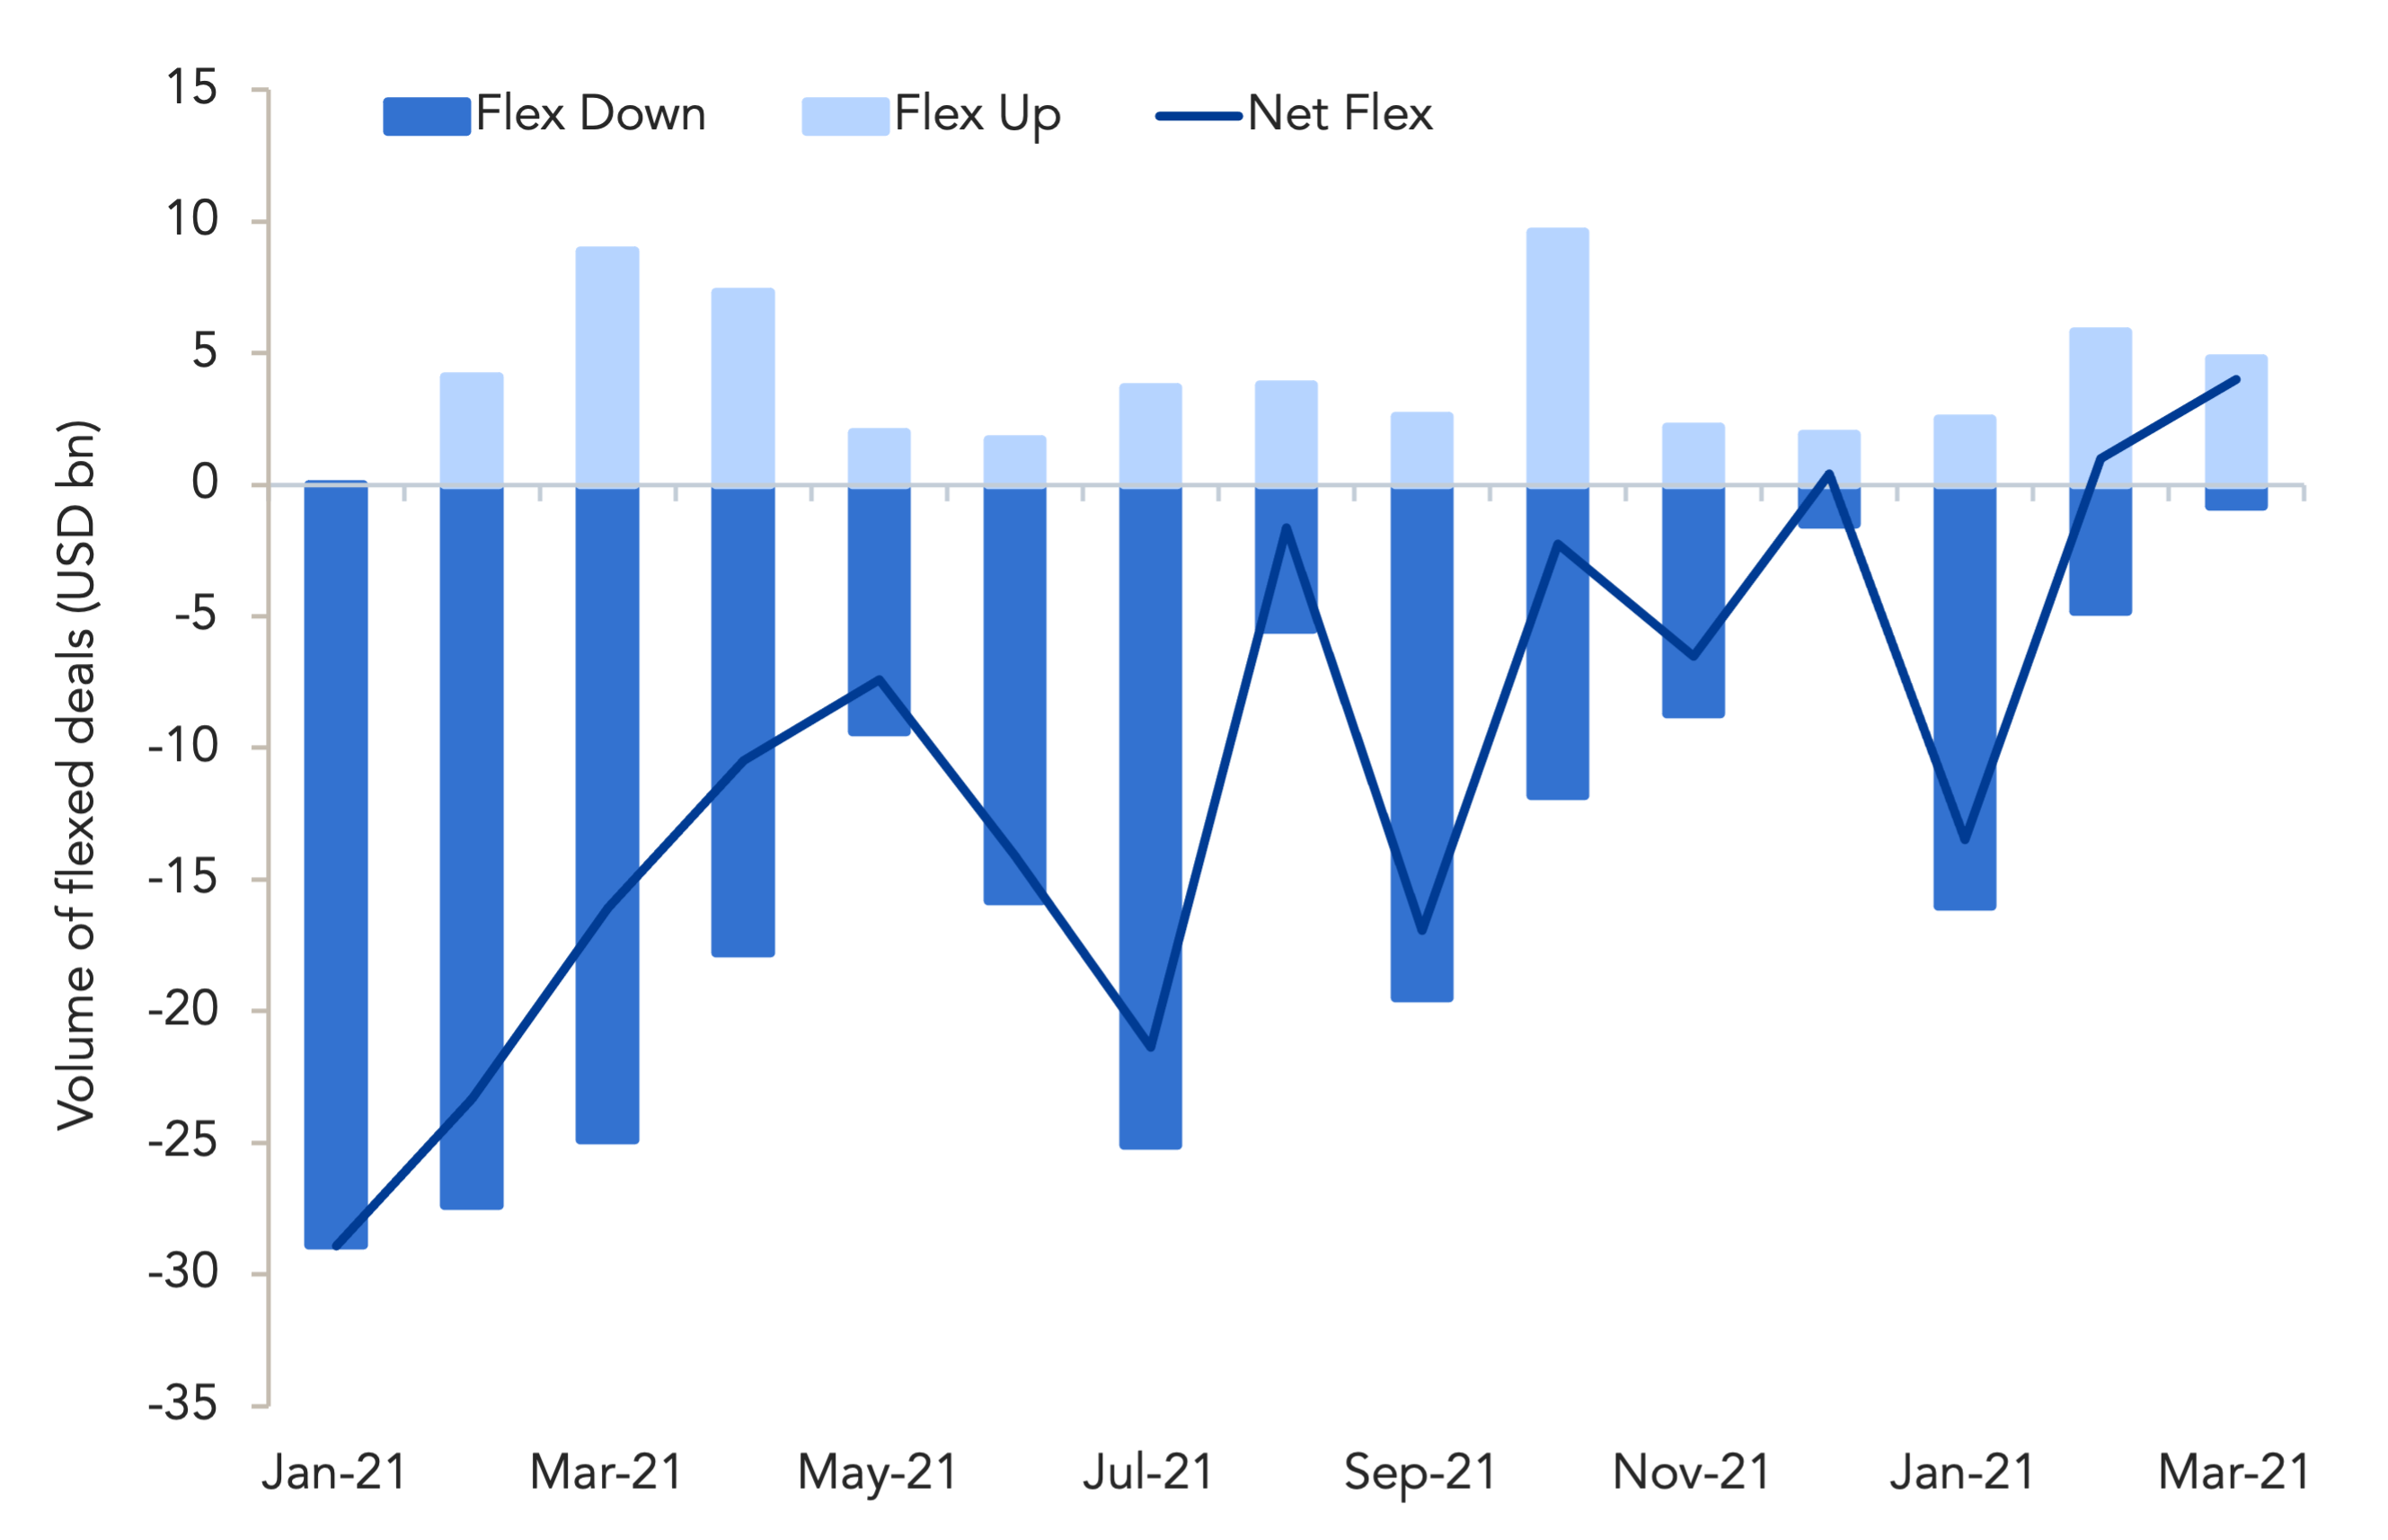
Indicative of the tougher pricing environment, more tranches flexed pricing wider in February (eight tranches worth USD 5.3bn) than tightened pricing (five tranches for USD 4.8bn). In March, 12 tranches worth USD 4.8bn have seen pricing finalize wide of initial talk, while just two borrowers (USD 0.8bn) have been able to negotiate tighter pricing during syndication. Indeed, some processes have been drawn out of late, as borrowers and lenders sort out appropriate pricing during this period of heightened volatility.
Communications firm Viasat priced a USD 700m TLB due 2029 75bps wide of initial talk at SOFR+ 450bps (50bps floor) and a 98 OID. Allocations, which were originally expected by 17 February, were not finalized until 24 February after pricing was adjusted. Weber-Stephens Products similarly moved pricing out 50bps from talk to price its USD 250m incremental loan at SOFR+ 425bps (75bps floor) and a 97.5 OID.
Average discounts offered on new loan issuance rocketed to an average of 189bps in March, as borrowers offer investors incentives to lend during presently high levels of inflation and uncertainty. Covis Pharma priced a USD 595m TLB at a 90 OID following a drawn-out syndication process that saw investors negotiate a significant discount following concerns over the company’s product concentration. More recently, SPX Flow wasforced to offer a discount of 95.5 on its USD 1.61bn TLB due 2029 to support its acquisition by Lone Star Funds.
(Past performance is no guarantee of future results.)



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…