


First lien loan pricing spikes in June in tandem with secondary market collapse
Source: Markit, BofA US HY Index
To open the year, loans were bid at an average price of 97.78, with approximately 20% of loans bid in the par-plus range. As inflation numbers started coming in hot, and as the war in Ukraine erupted on 24 February, bids slid more than 6 points to only 91.48, with barely 1% of loans trading at par or better. This is the lowest level of trading for loans since August 2020, when the market was still recovering from lockdowns imposed during the onset of the coronavirus (COVID-19) pandemic.
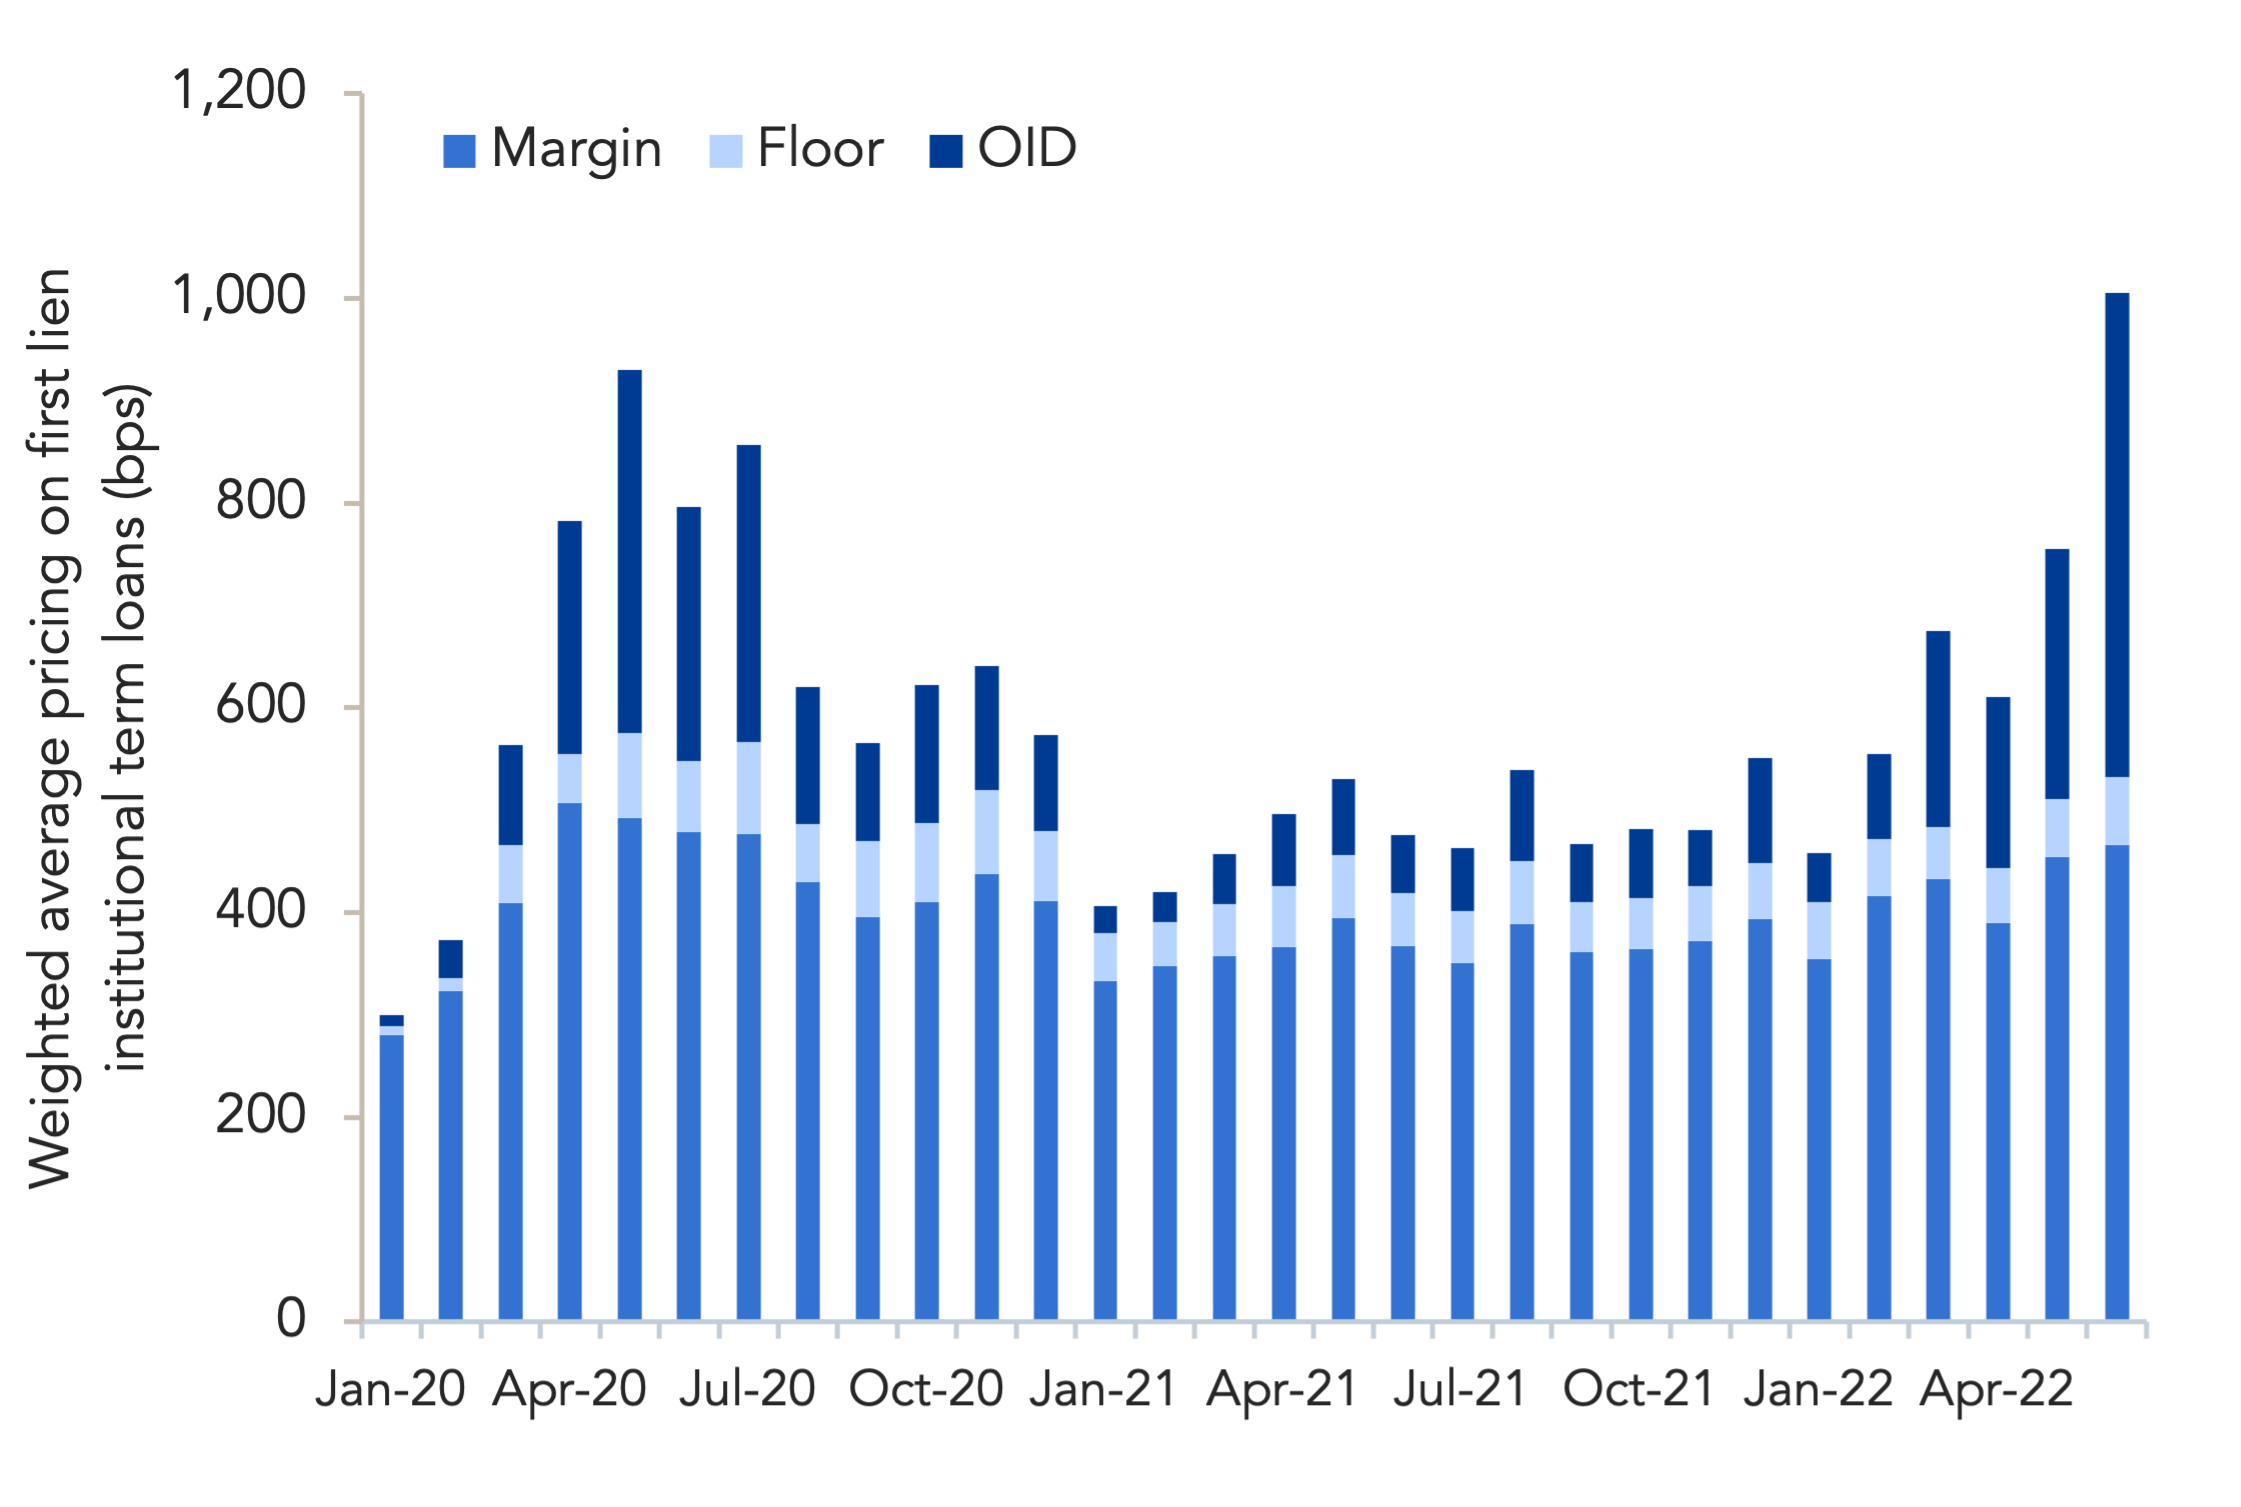
Issuers willing to brave the primary market have been faced with a steep pricing environment in order to get deals across the finish line. Margins on first lien institutional loans have widened to 466 basis points (bps) in June from only 355bps in January, as lenders demand increased compensation for taking on risk in such a market. Almost all new loan issuance in June came from borrowers rated single B.
One of the most striking connections between the loan primary and secondary market can be seen in the sharp widening of average original issue discounts (OIDs) over the course of the year. In January, discounts averaged only 48bps, as most new loans were issued at a price of around 99.52. In June, the average discount jumped to 473bps, with the average issue price of new loans plummeting to 95.27 in tandem with the collapse in secondary pricing.
Material Handling Systems (MHS) issued its USD 1.47bn term loan B (TLB) to support the company’s acquisition of Fortna Inc at a margin of SOFR+ 550bps and an OID of 89.5 for a whopping 1,050bps discount. In fact, the loan was upsized during syndication to account for the flexed discount. Issuers such as Avaya chose a different route, opting to pay lenders a 10-point upfront fee to compensate for potential losses in the secondary market as prices remain in flux. The company’s USD 350m TLB was issued at S+ 1,000bps and par, a steep price to pay to refinance upcoming debt.
The seemingly extreme discounts being offered on new debt are not preventing loans from trading off in the current secondary market climate, however. Even loans like that of MHS have seen bids come in low of issue, with pricing currently falling to around 88.5.
(Past performance is no guarantee of future results.)



Latest news
Behind the Scenes
Climbing toward the average is a very different story than surpassing it.

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…
Private Credit Defaults 101: Now Streaming
Every big theatrical release eventually makes its way to streaming. It gives people who missed it in theaters a chance to catch up, and lets those who saw it go back for a second look at what they missed the first time.