


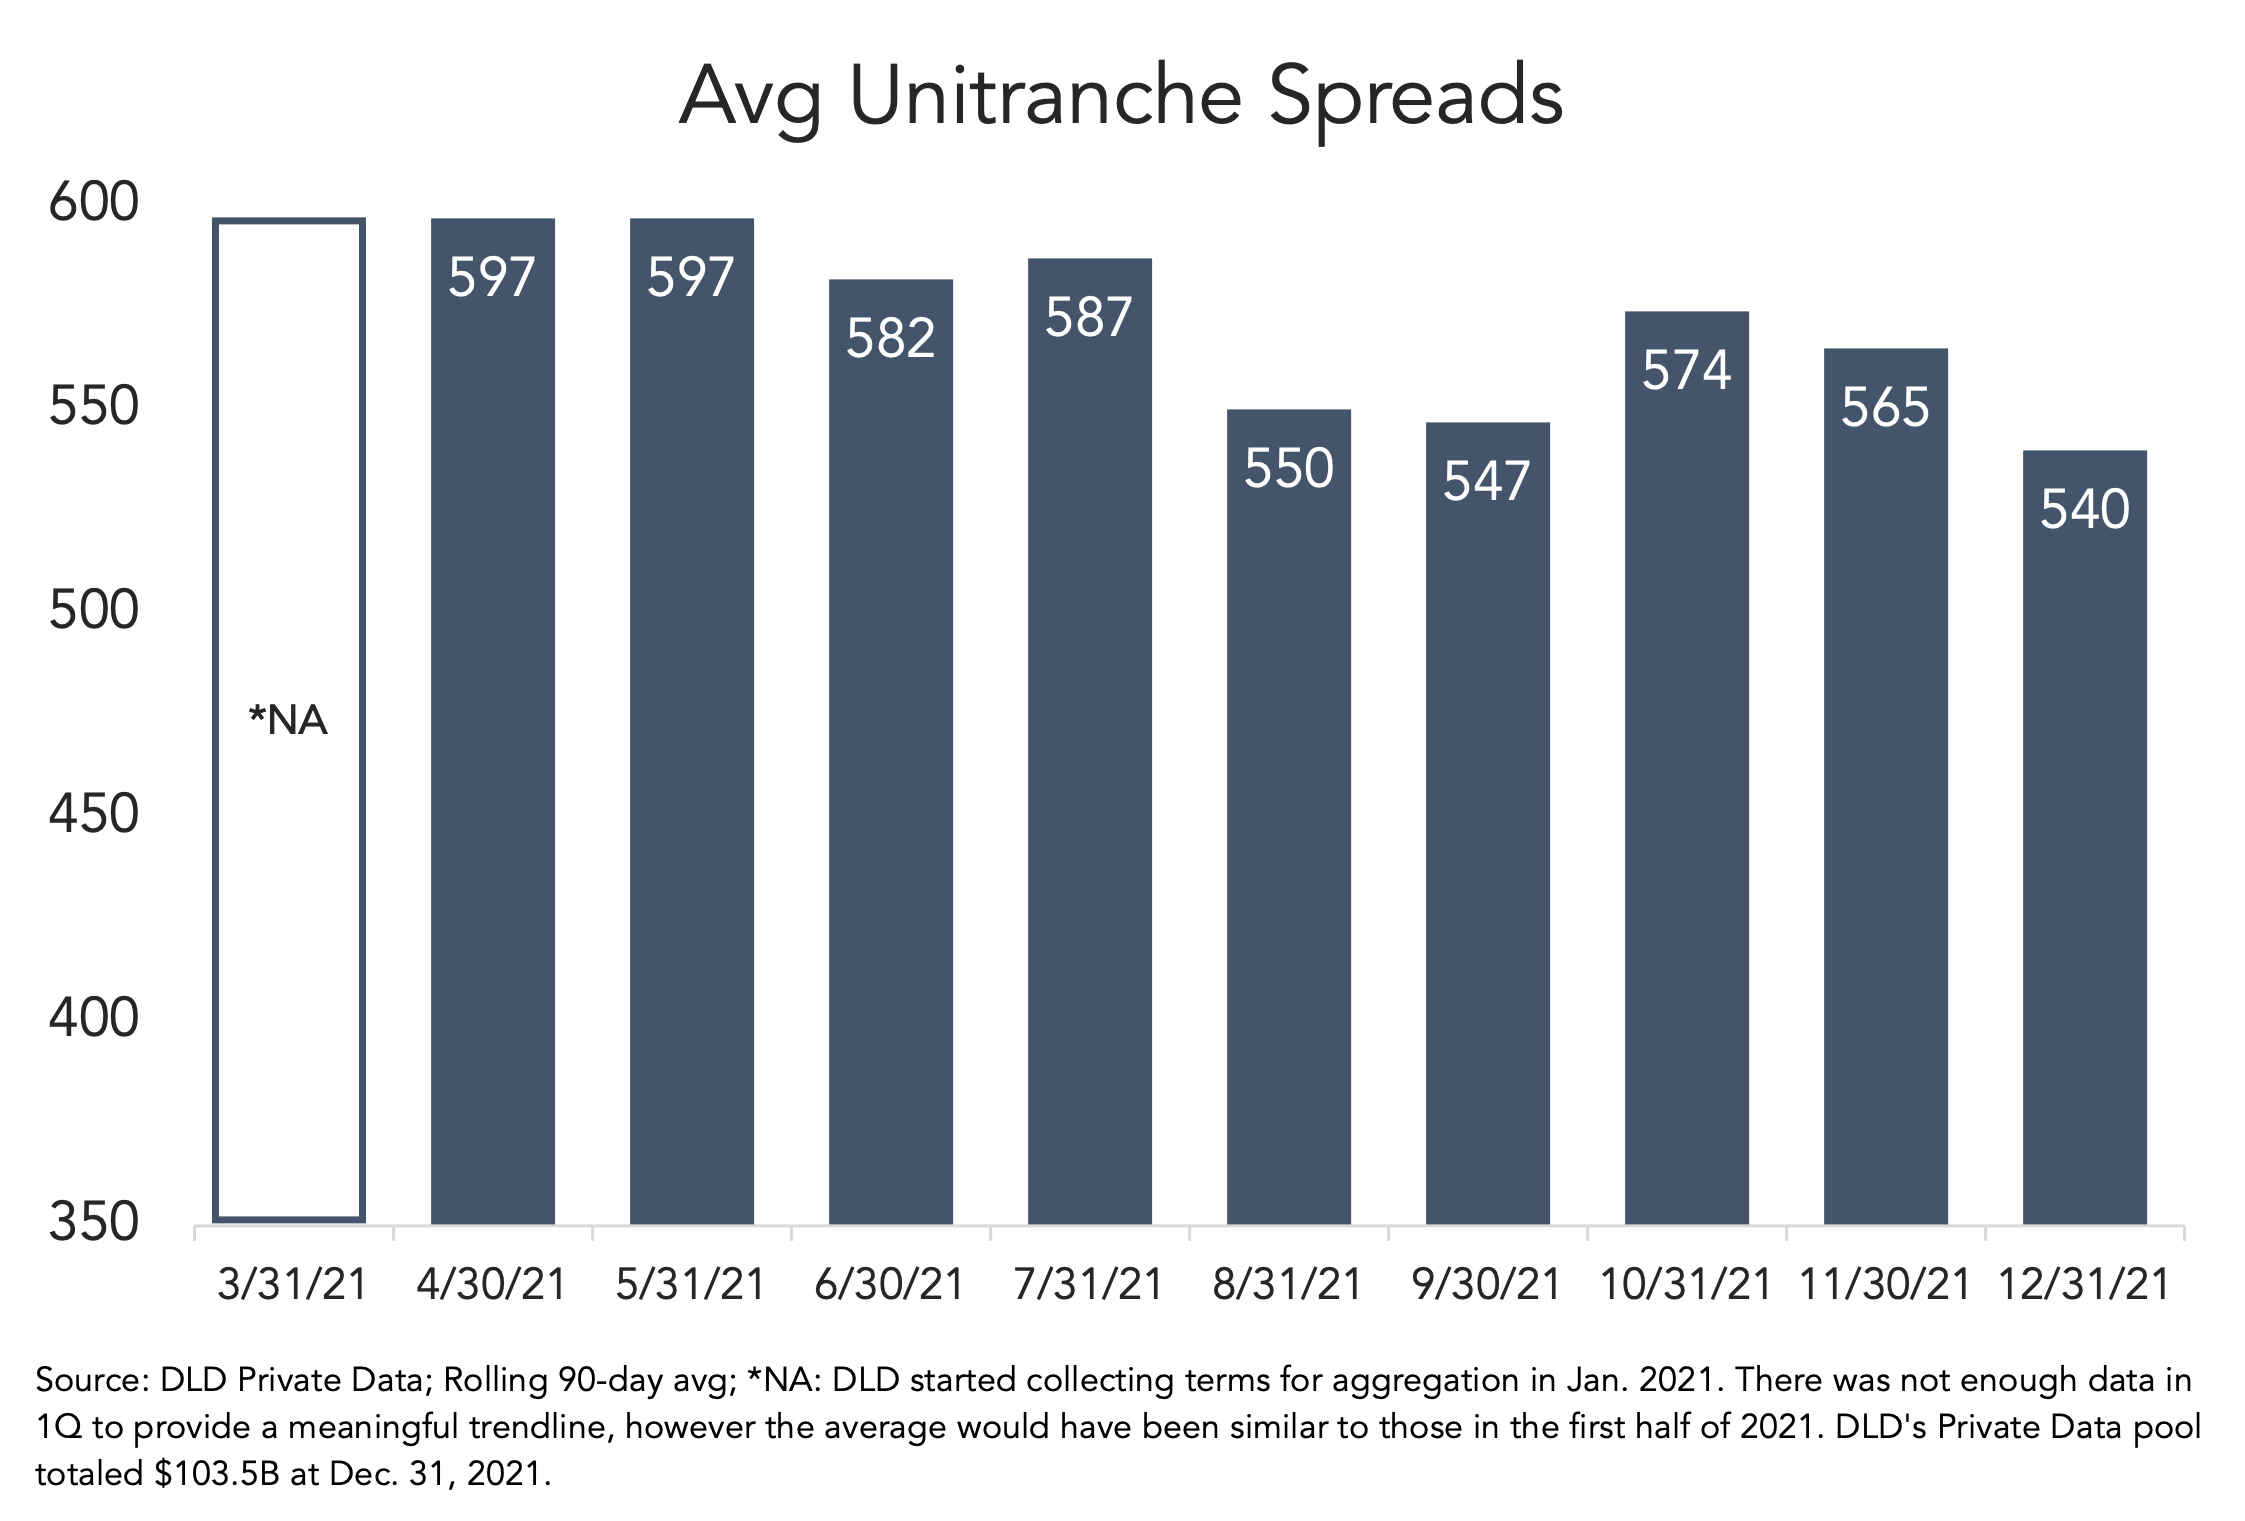
Competition moved unitranche spreads 25 bps lower in December to an average of L+540, a monthly low in 2021, despite the stabilizing effect heavy volume in the fourth quarter had on pricing for smaller borrowers and non-unitranche LBO financing. The decline dropped all-in yields to 6.7%, also a monthly low last year.
Return requirements should keep pricing from slipping much further, especially as looming interest rate hikes will bump funding costs.
DLD’s pool of unitranche loans consistently averaged about $50 million in EBITDA last year, the larger end of the middle market. Like a sliding scale, the private market’s reaction to movement in liquid credit tends to decline in tandem with borrower size, yet competition is affecting that convention. Today’s direct lending market is more crowded than before and grown exponentially since 2015.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…