


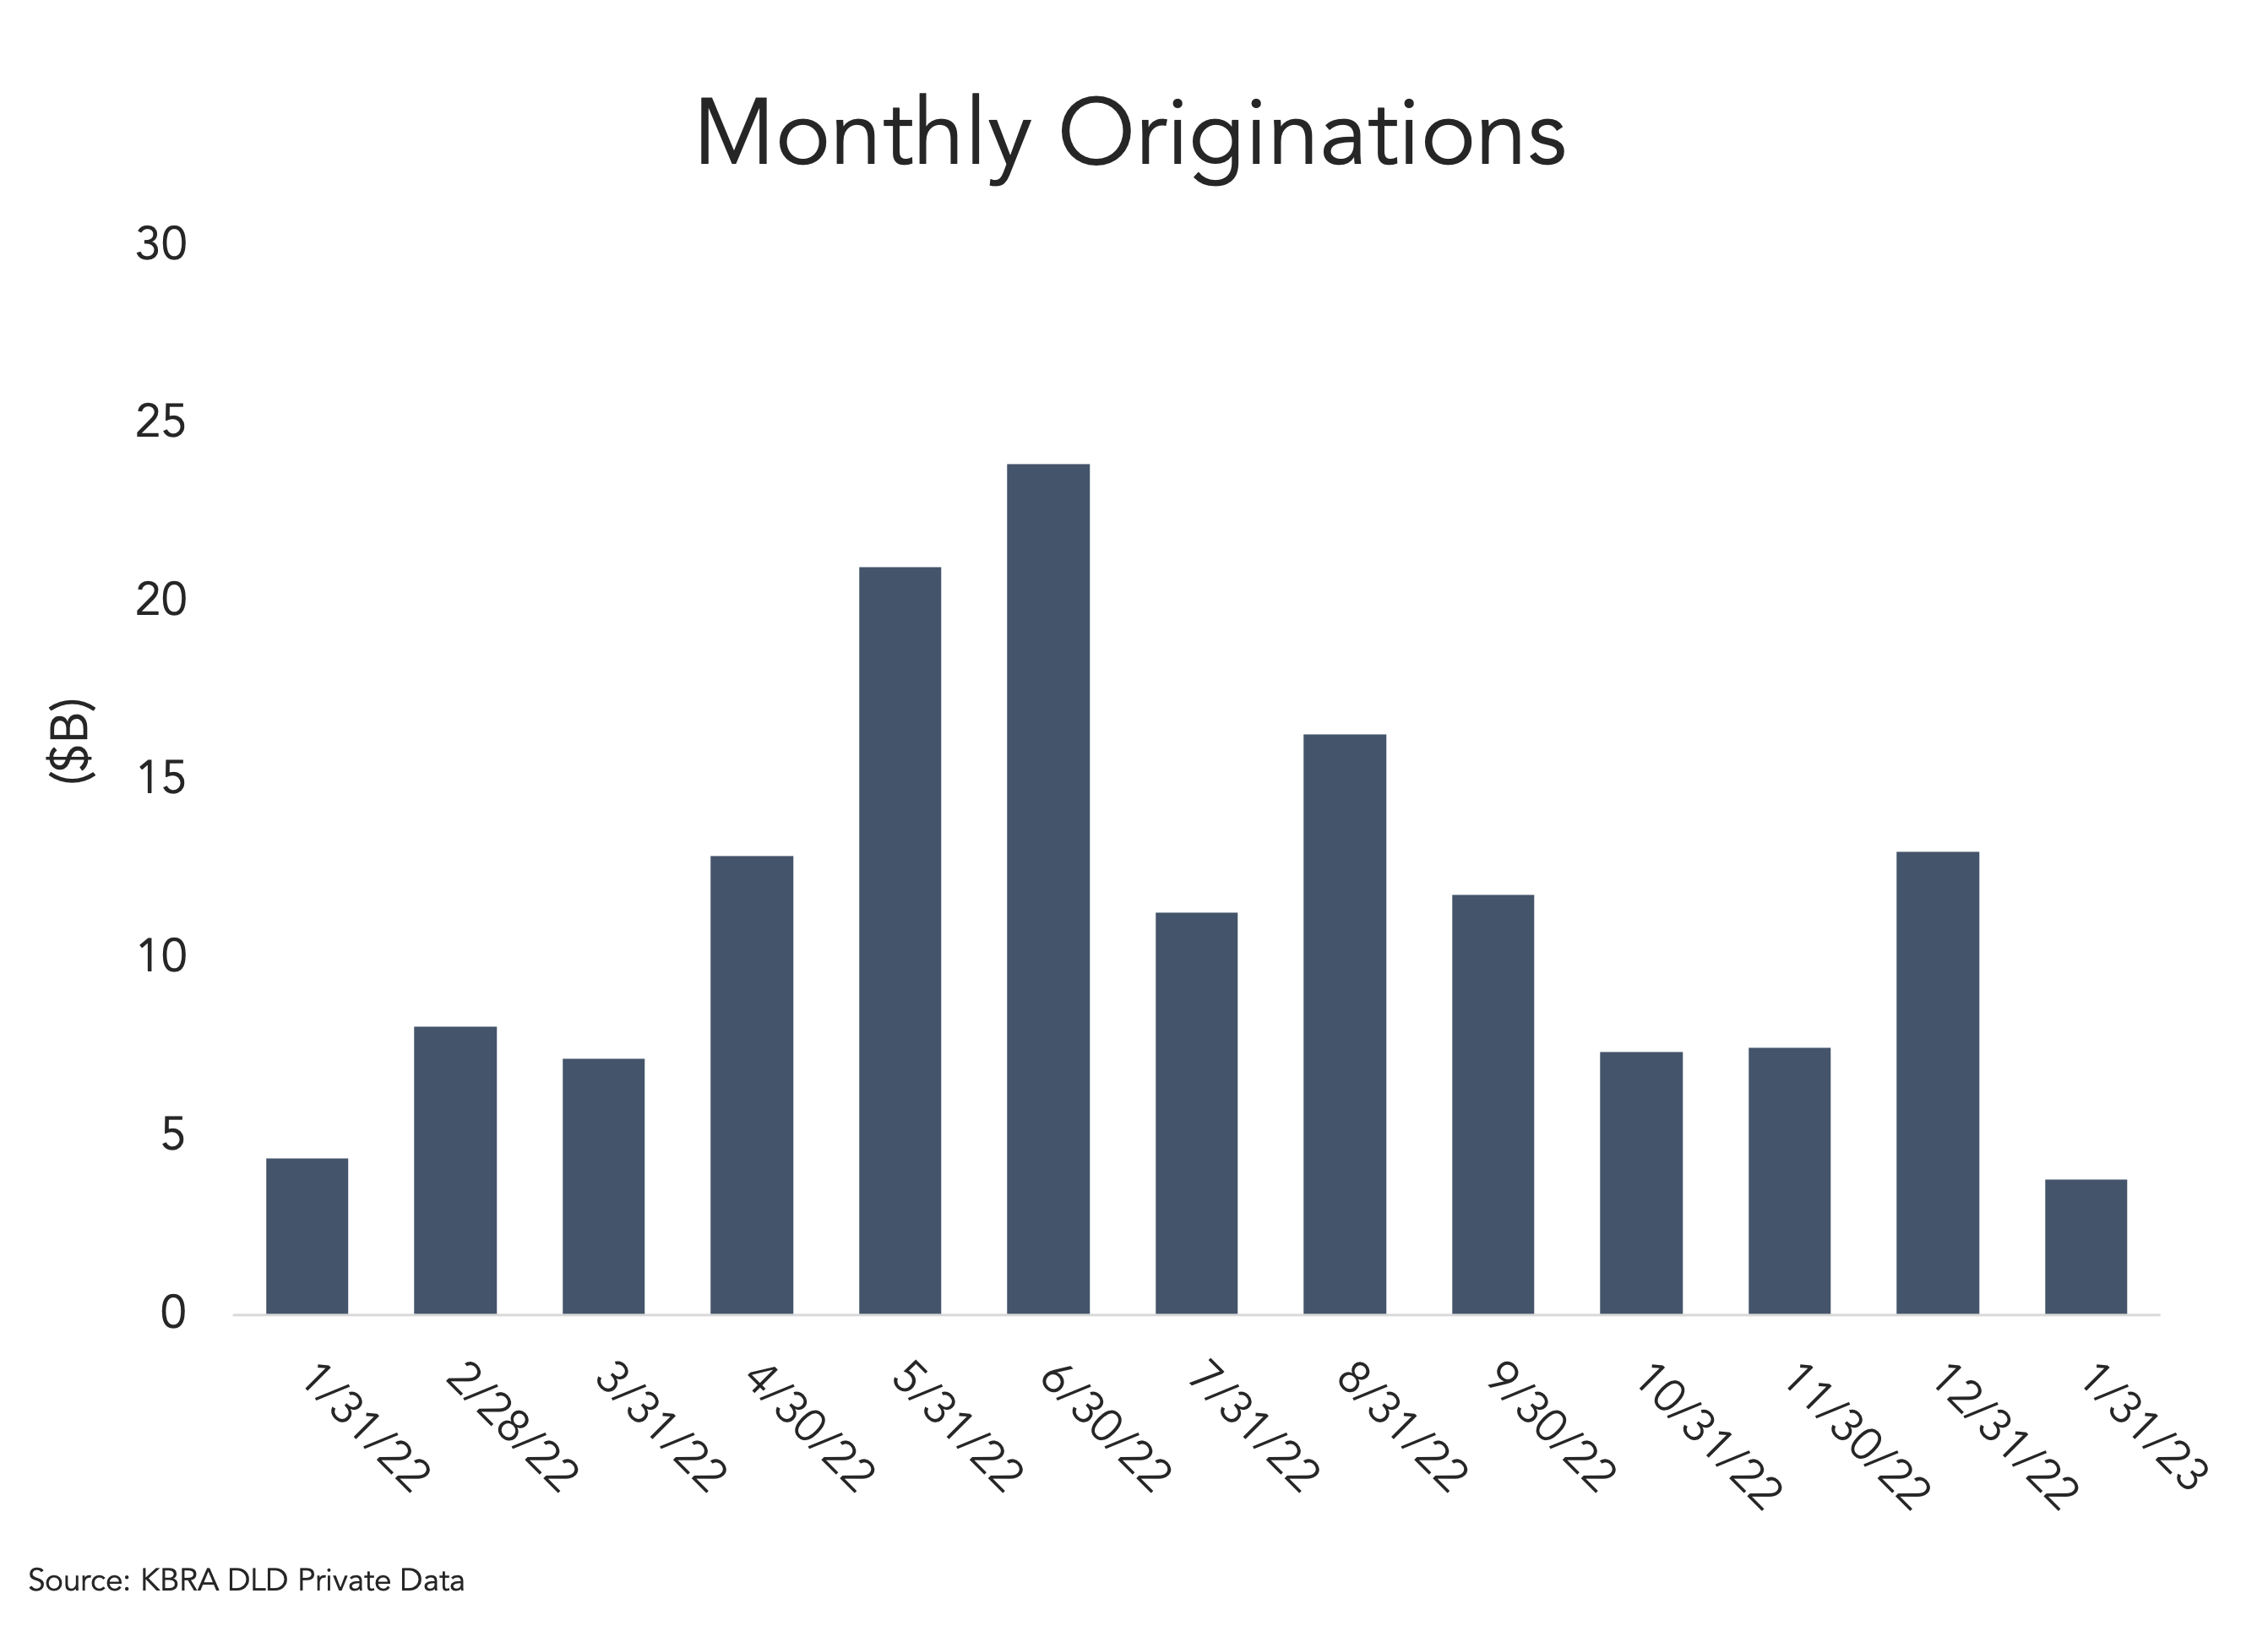
KBRA DLD tracked $3.8 billion in new-issue volume last month across sponsored, U.S. borrowers. Managers said new business felt slower than usual for the start of the year, and indeed, the tally in our Private Data set was down 14% from January 2022. The slide is mild, however, compared to the year-over-year nosedive across the syndicated market last month.
It’s true that middle market and private lending lag broader financing trends, which means February and March may show declining volume as well. Movement in the private market is typically tighter, however.
It’s also true that volatility continues to bring expansion to the U.S. direct lending market, which is estimated at over $1 trillion in size. Annual volume in our Private Data set finished 2022 up 30% as liquid credit markets posted their worst year in over a decade. Direct lenders are positioned to increase their market share again in 2023, even if the M&A machine sputters. Managers remain open for new business; the syndicated market is still licking wounds.
Add-on financing led the new issues in our January set, taking a 58% share versus 41% for buyouts. January was the first month that add-ons outpaced LBOs since September 2022.
Add-ons are an easier play for sponsors this quarter, mainly for three reasons: 1) borrowing costs are nearly 12%, 2) sellers remain resistant to lower valuations, and 3) economic uncertainty lingers over inflation, additional rate hikes and political friction.
M&A has started to resurface this month with mid-sized financing, including a $630 million loan to support a take-private transaction in the industrial services space. The private credit has four titled agents and includes a $100 million delayed-draw facility.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
