



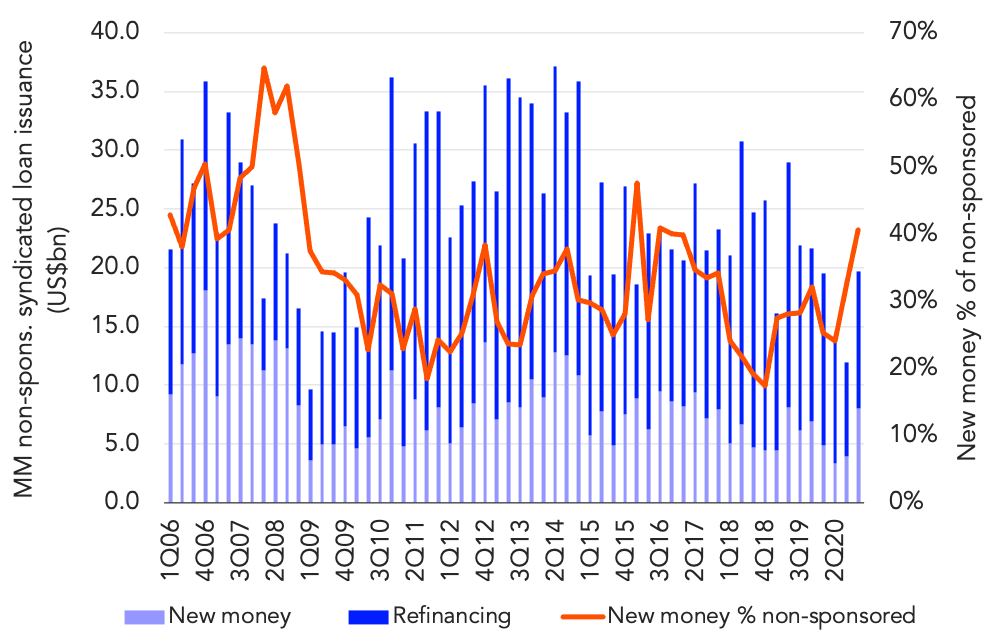
Non sponsored syndicated loan volume bounced back to total US$19.7bn in 4Q20, the highest quarterly level since 4Q19. In the last couple of years, the non-sponsored middle market had been chugging along, as corporate issuers were cautious about undertaking any expansion plans.
However, in the months leading to the pandemic, bankers that focus on the space had seen their pipelines building, but then COVID-19 hit, and issuers retrenched. For most of 2Q20 and 3Q20, bankers were in virtual meetings with clients figuring out what the impact was going to be on their businesses and looking for ways to mitigate the risks. But in 4Q20 bankers were back to lending.
New money lending reached its highest level since 2Q19 at US$8bn, but only US$1.7bn of this total backed M&A activity. The market snapped back to the same pre-Covid dynamic – too much liquidity and limited opportunities especially on the M&A front. In turn, competition was back, and terms loosened once again.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.