



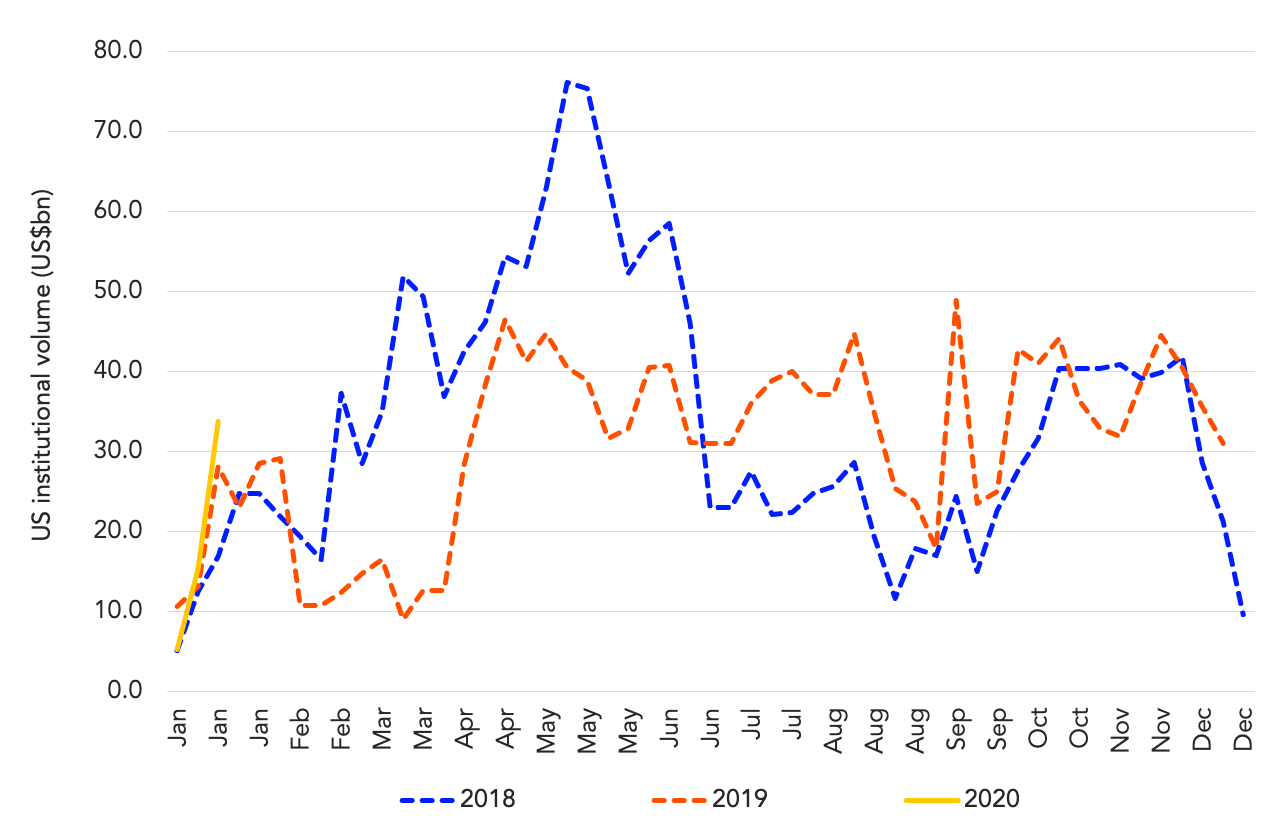
The US institutional loan pipeline improved to the US$34bn area last week, its highest January level in the past two years. Market sentiment has improved sharply from a few months ago, particularly for lower-rated issuers. In the secondary market, the B2/B3 cohort of names closed last Friday with an average bid of 97.2, the highest level since last May. Meanwhile, the LPC 100, Refinitiv LPC’s grouping of the largest most liquid names in the secondary market, also improved substantially to the 99.2 level, the highest since June 2017. This improved secondary market sentiment has helped attitudes shift in the primary market. Last week seven deals reverse flexed in favor of issuers, including four issuers rated either B2 or B3. One of those deals was for B2 rated issuer Presidio, which came to market with a US$625m term loan B partially backing its buyout from BC Partners. The loan ended up flexing down 100bp, the largest spread-tighten flex since October 2018.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…