


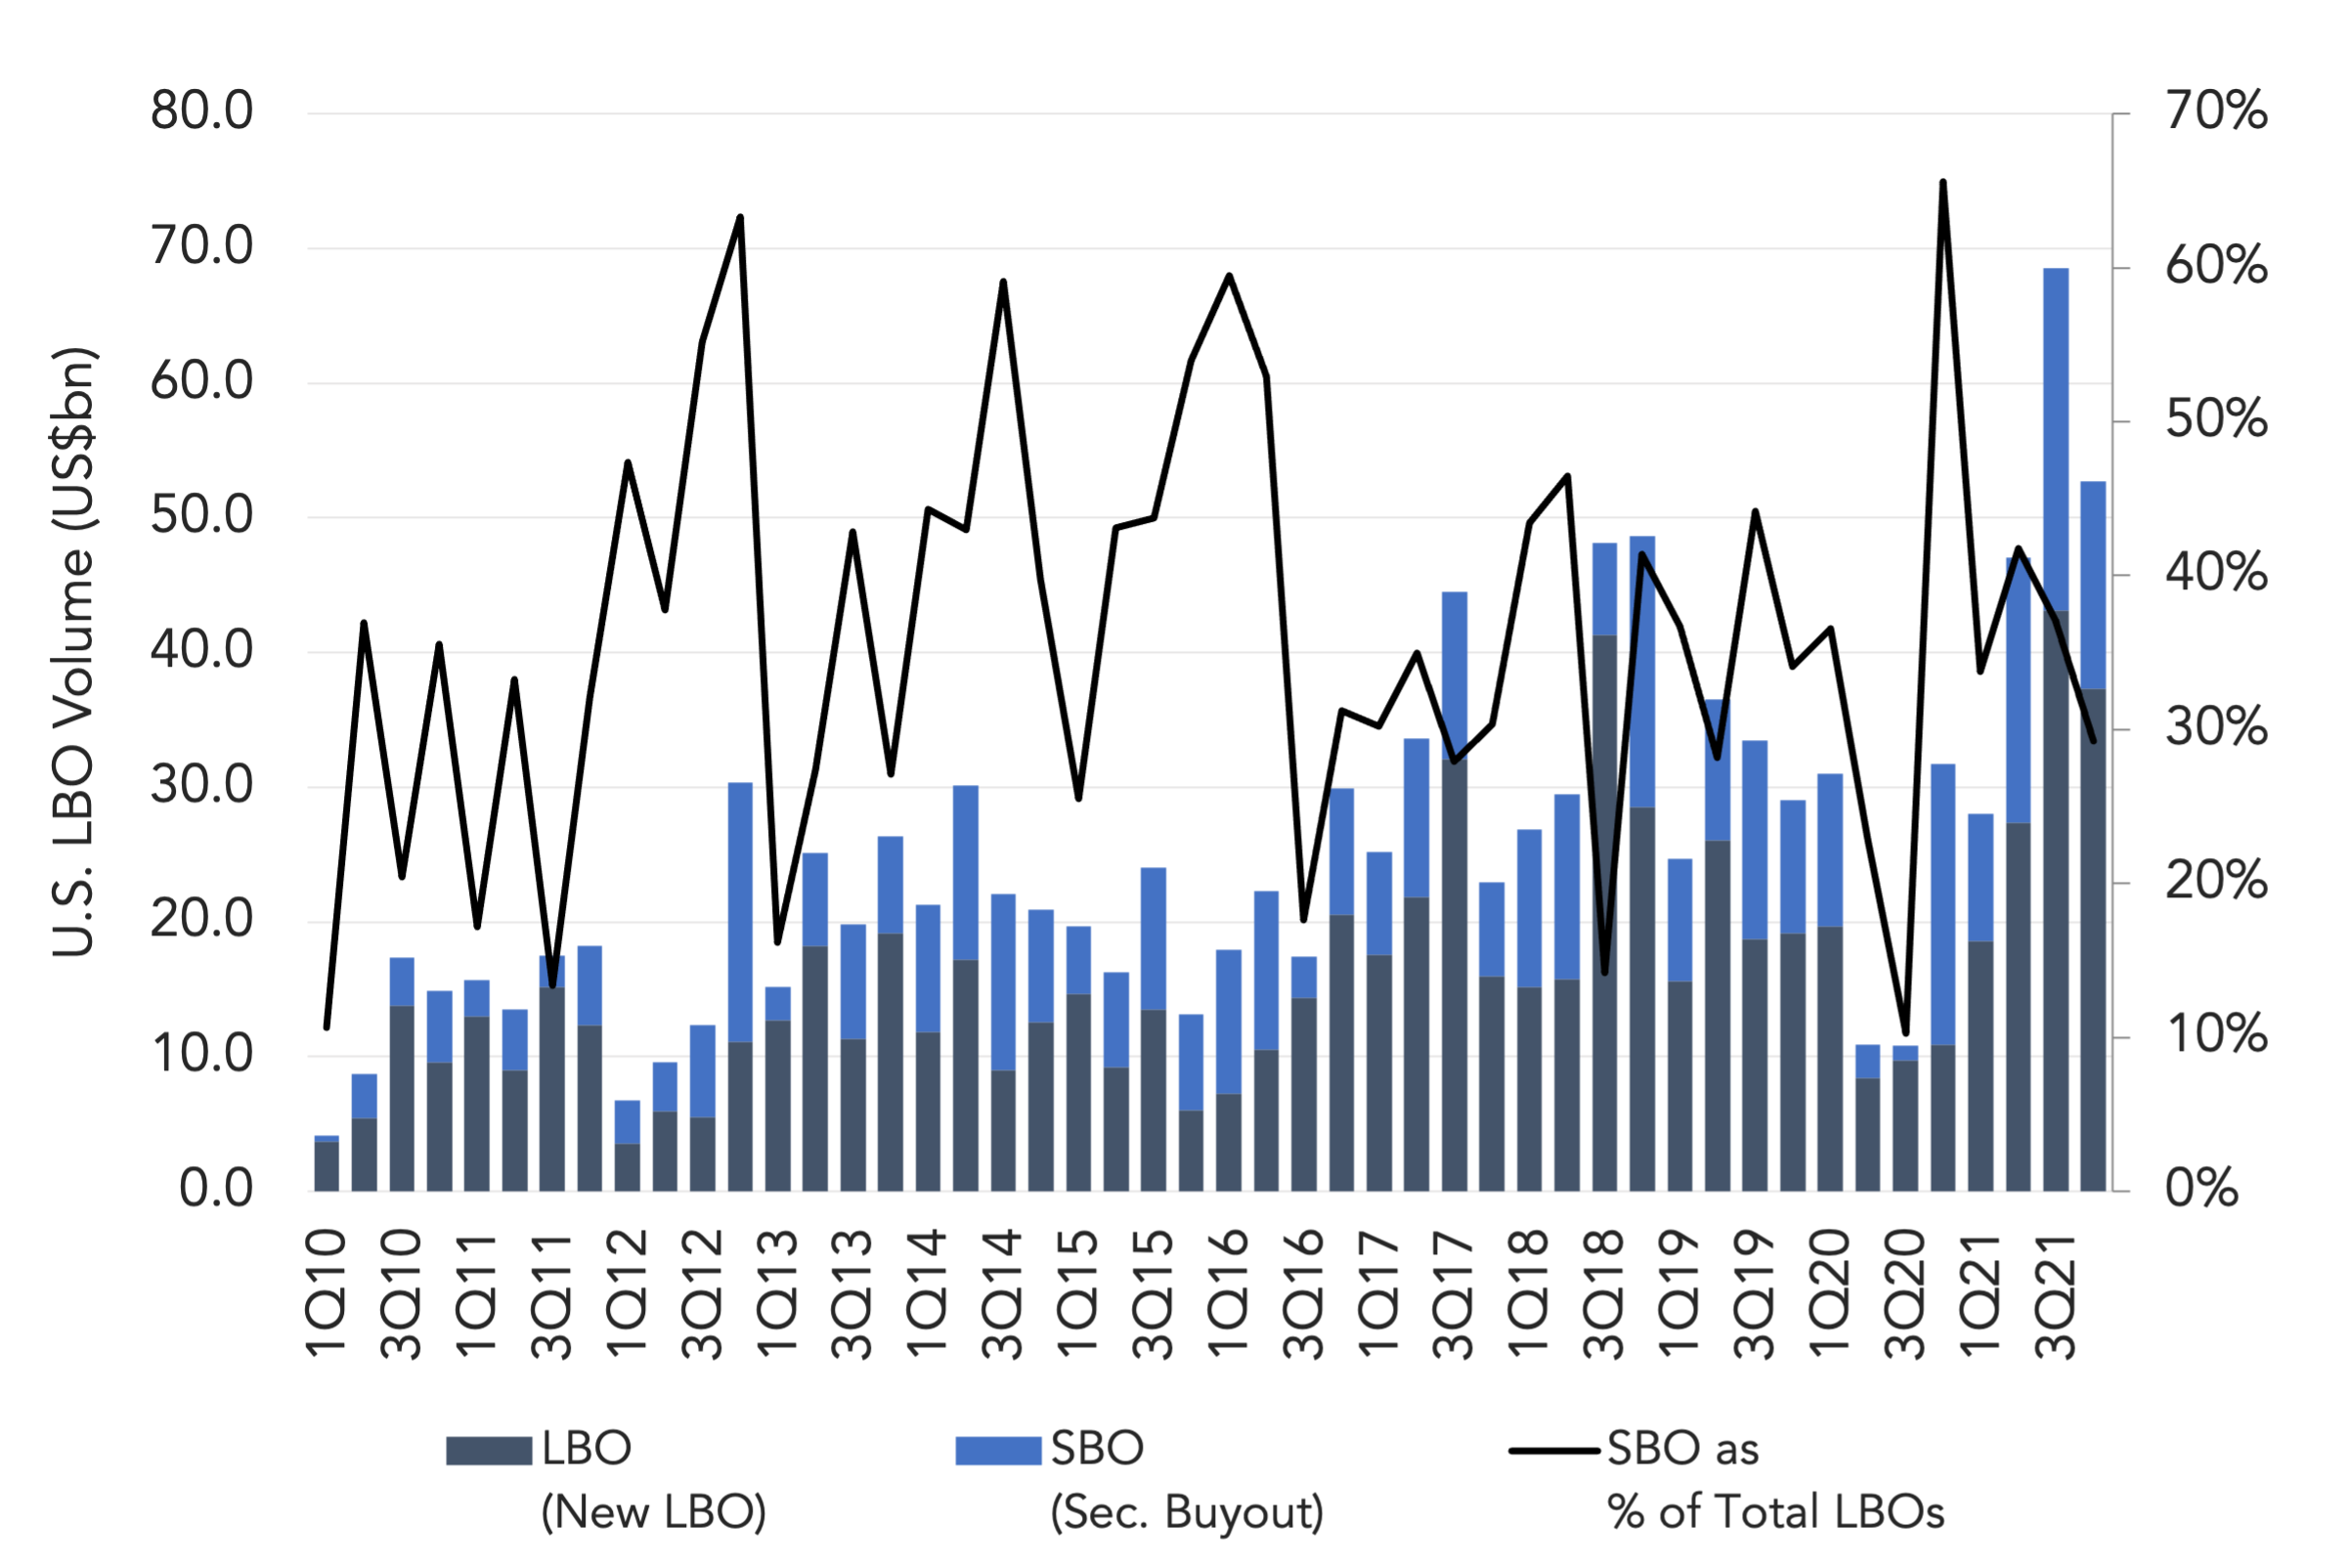
Private equity sponsors actively tapped the loan market in 2021 to back over US$196bn in buyout activity, the second highest total on record and just behind 2007’s historic totals north of US$200bn. More significantly, over US$126bn or 64% of total issuance represented new, “take private” financings, up from less than US$49bn or 59% of 2020 levels. Secondary buyouts between sponsors were also up nearly two times year ago levels at US$70bn to set a new record. Volumes increased quarter over quarter through the first three quarters of 2021 as sponsors sought to put large pools of cash to work in what was an increasingly competitive , low interest rate environment. By 4Q21, the pipeline slowed as the market grappled with transition away from Libor and worked to wrap up deals amid signs of pandemic burnout.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
