


3Q20 MM sponsored loan issuance picks up from 2Q20’s low, but still quite anemic

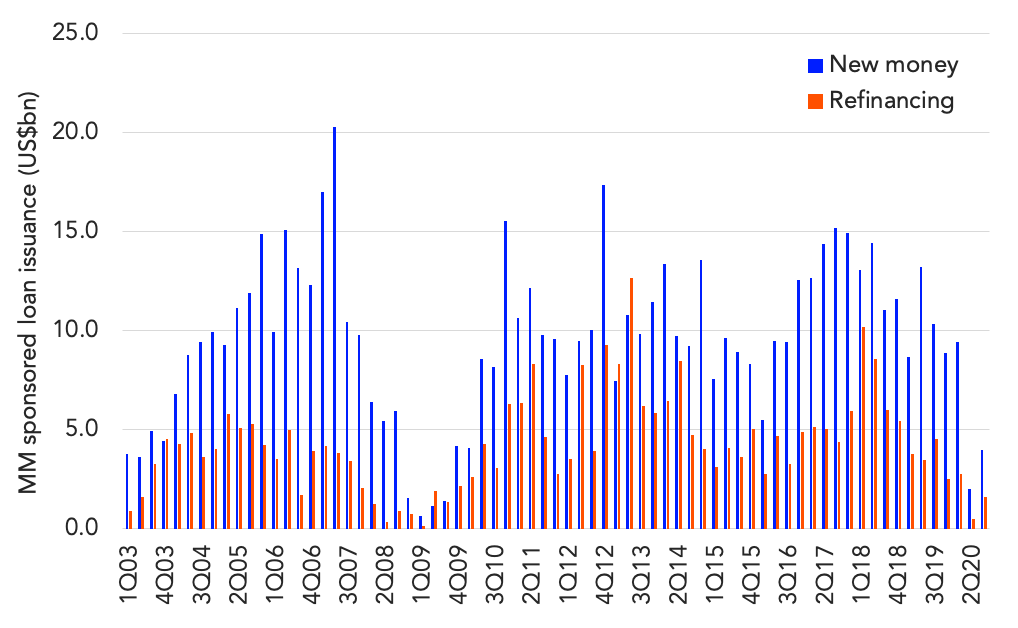
Sponsor-backed middle market volume showed a pick up in 3Q20 to US$5.6bn, up 120% from 2Q20’s post credit crisis low. But volume was still quite dire and over 62% behind 3Q19’s level. While pricing has been tightening dramatically month after month, refinancing activity remained few and far between with most loans trading below par and spreads still elevated relative to pre-COVID levels.
The average spread on MM sponsored deals to hit the institutional loan market in 3Q20 was 562bps, up from 520bps in 2Q20. But with strong demand from loan investors aching for assets, PE shops did tap the syndicated market for dividend recaps. In fact, dividend recap issuance of US$1.4bn comprised 25% of total activity, the highest market share seen post credit crisis.
For most M&A transactions, private equity shops continued to bypass the syndicated market in 3Q20 and head straight towards direct lending executions to avoid ratings and to eliminate flex risk. The syndicated loan market only saw 10 middle market LBO deals hit in the quarter resulting in a mere US$1.1bn of volume. Lenders and sponsors are hopeful for a more robust 4Q20 as PE shops try to close deals before the election and before any potential COVID volatility returns.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…