



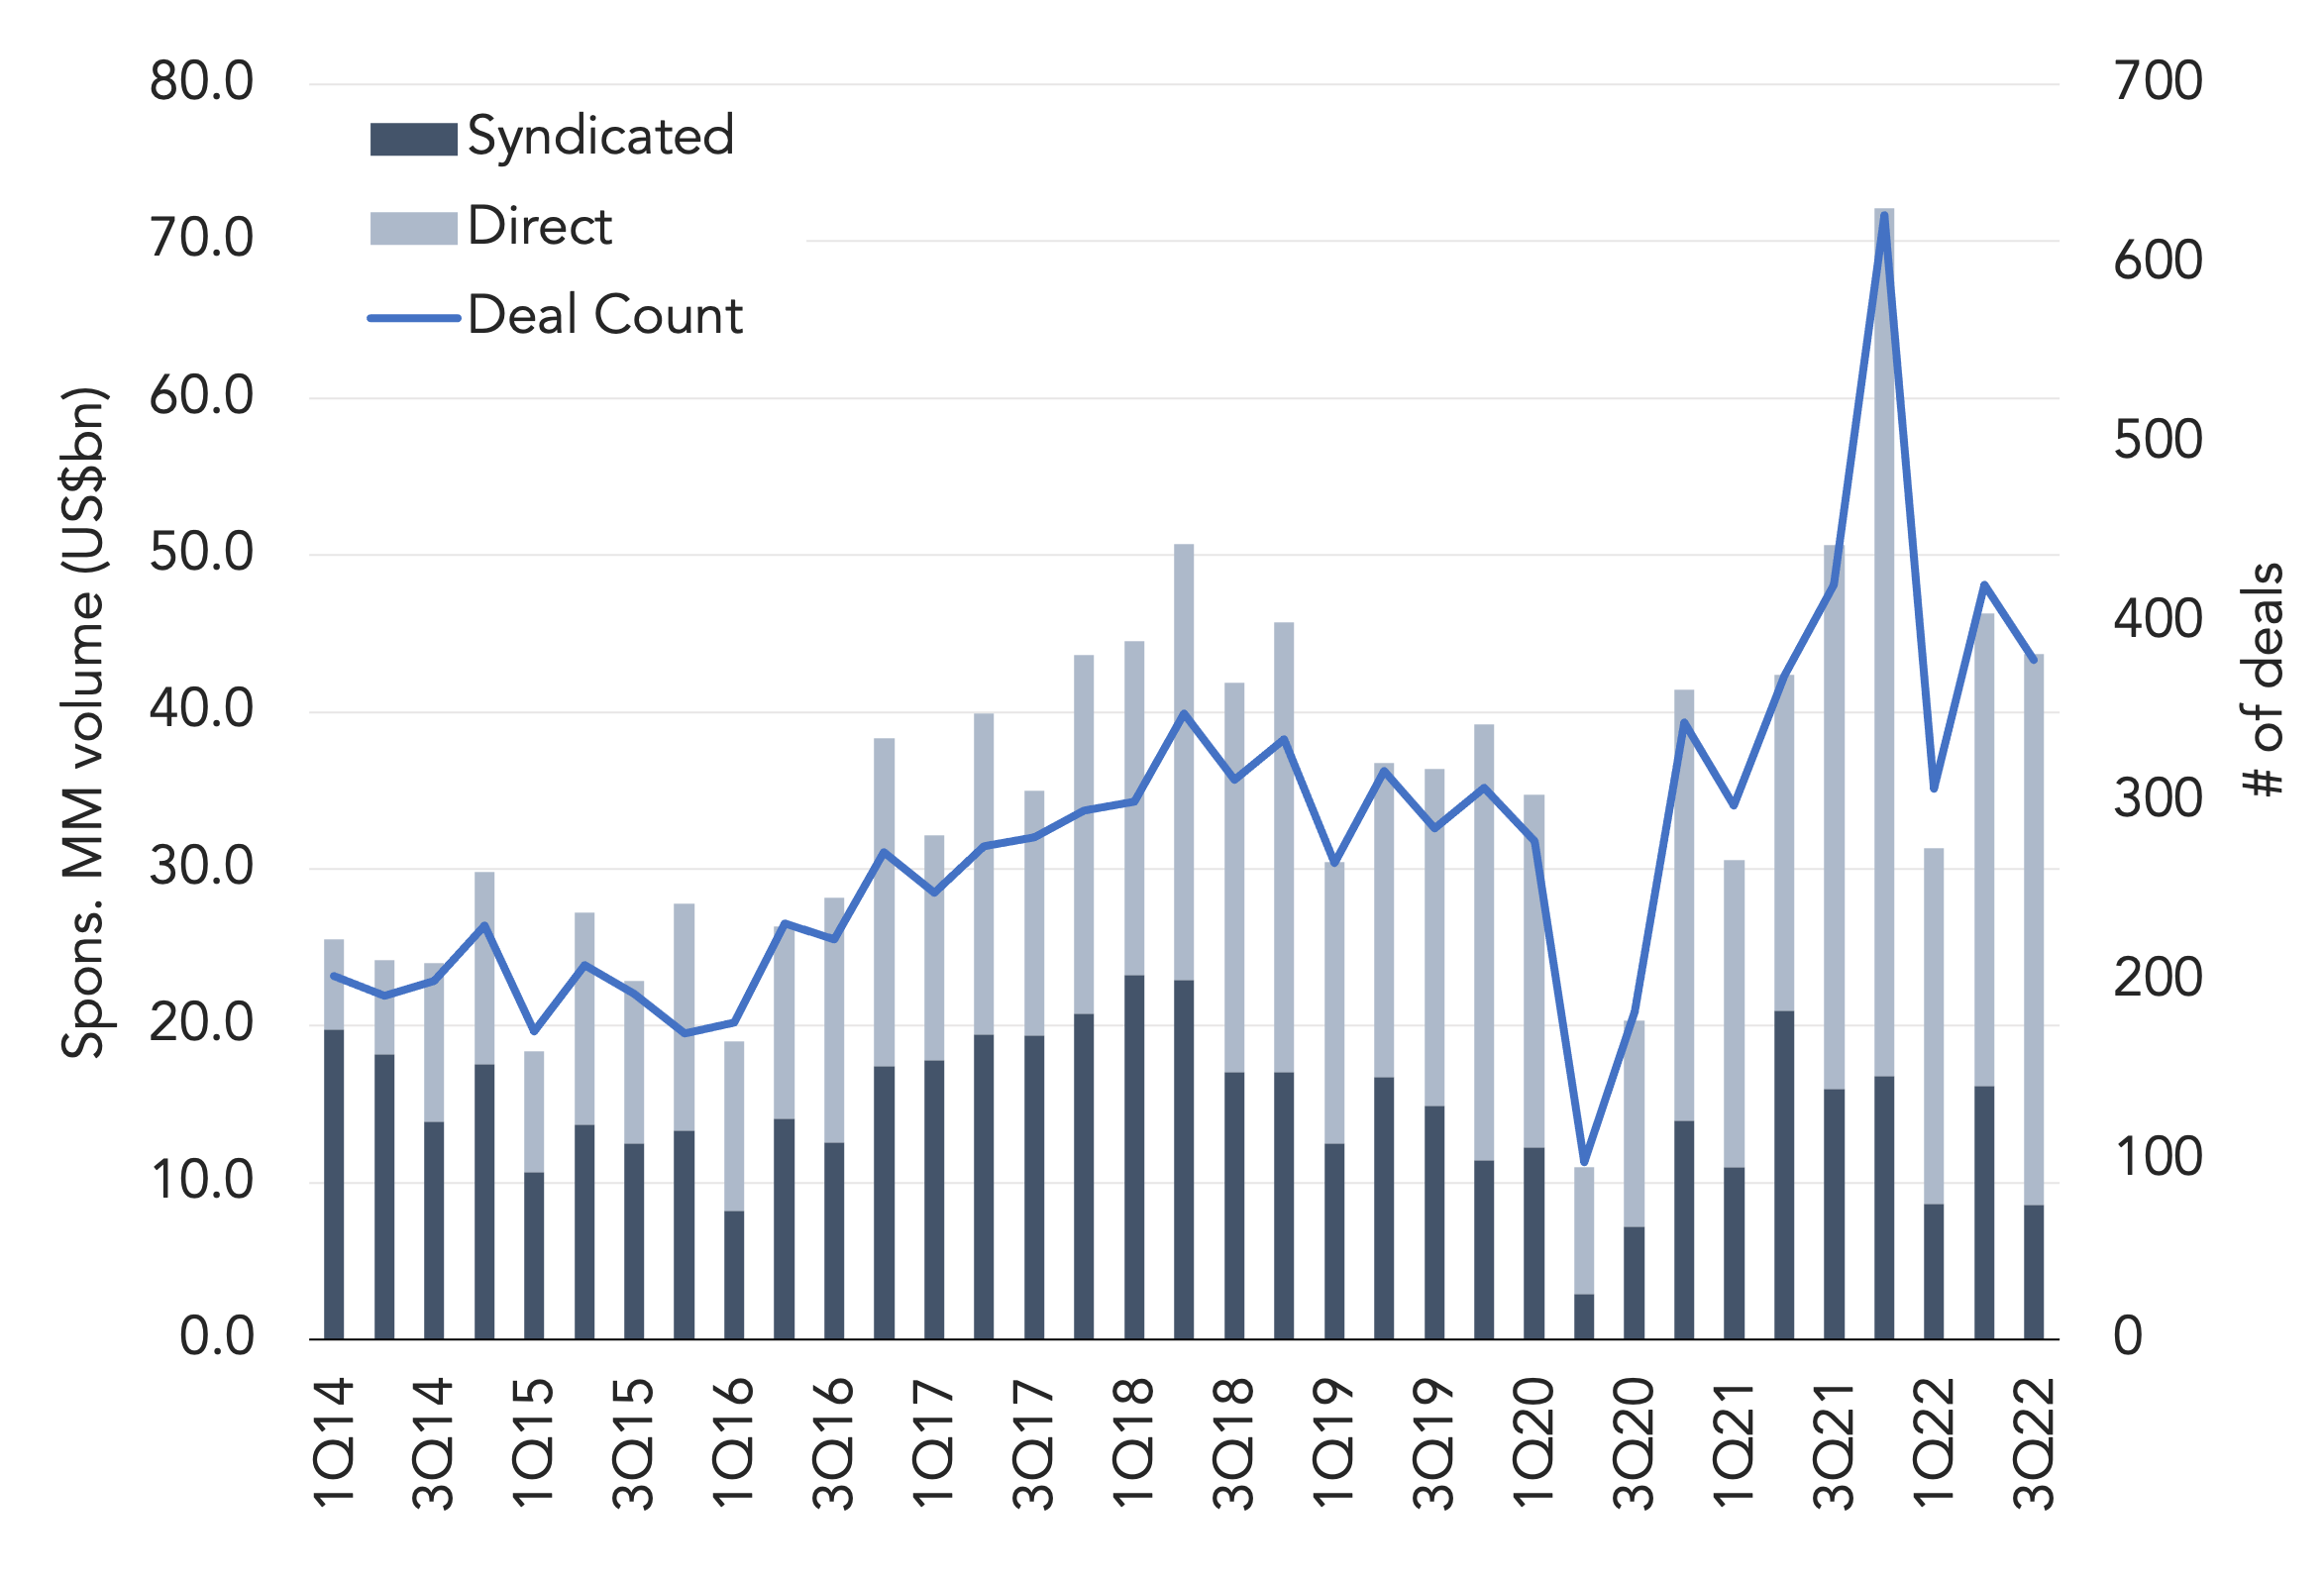
Last quarter, there was US$35.1bn of US sponsored middle market direct lending volume, 17% higher than 2Q22’s levels and the most since 4Q21’s record US$55bn level. The direct lending market remained quite busy in 3Q22, in contrast to the broadly syndicated market which slowed down significantly due to broader market uncertainty about the macroeconomic picture. 3Q22’s US$35.1bn direct lending total was over four times higher than syndicated sponsored middle market volume level of US$8.6bn, which declined 47% from the prior quarter. Through the first three quarters of the year, US sponsored middle market direct lending volume has now outpaced the syndicated side by 2.6 times, the largest share ever. While 3Q22 proved to be another solid quarter for private credit, some direct lenders have said 4Q22 could be more challenging for deal flow. “I think 4Q will be slower,” noted one lower middle market direct lender. “It doesn’t feel like there’s a ton of energy in the market to transact right now.”
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
