



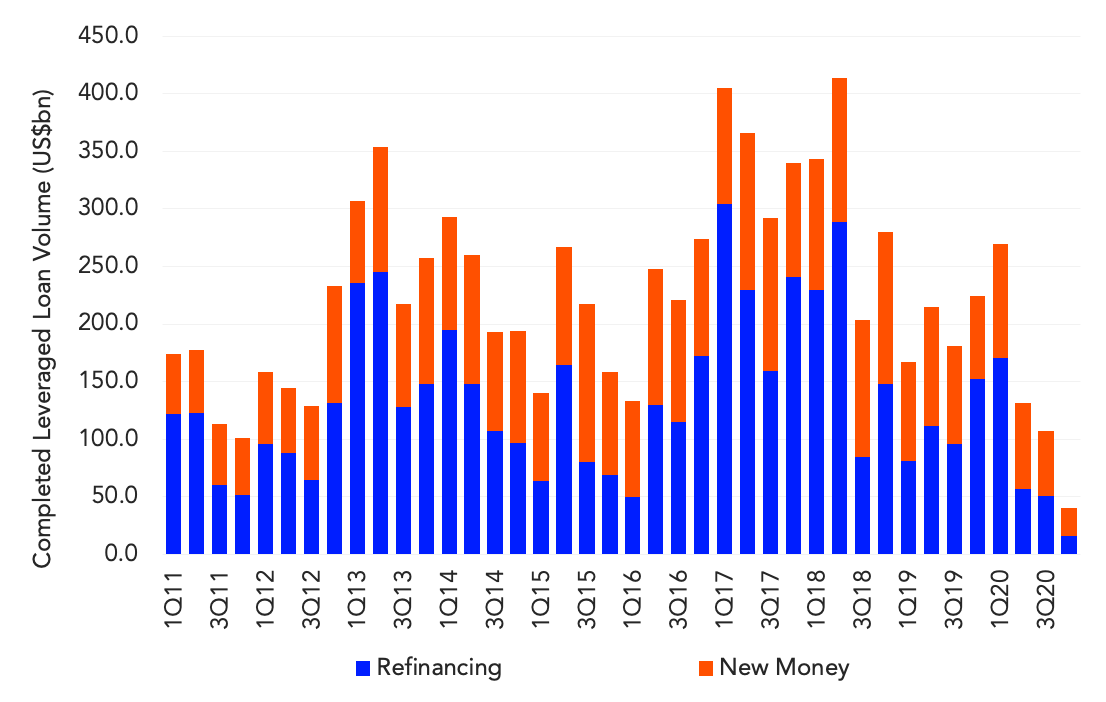
4Q20 US Leveraged loan volume was tracked at $39.8bn through October 22nd, up 8% compared to the $36.9bn raised during the same time last year. Of this total, $24bn or 60% of quarterly issuance thus far represents new loan assets while the balance has been a series of refinancings.
New money deals including M&A and buyout financings have garnered strong demand among institutional investors who have struck a balance between intense credit scrutiny and the need to put money to work in a highly liquid market. Lender appetite remains bifurcated between higher quality credits and tougher, storied names. In what is still a limited pipeline of deals, stronger credits can secure reverse flexes on deal terms. Parts Authority’s $600m buyout term loan saw its margin tightened to 400bp from the 425bp originally proposed.
Similarly, Les Schwab Tire Centers on Monday tightened the OID on its US$1.575bn buyout loan to 99.5 from 99 while out of the box margins settled at 350bps, the tight end of discussion which ranged from 350bps-375bps. The seven-year loan will finance the company’s buyout by private investment firm the Meritage Group.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.