



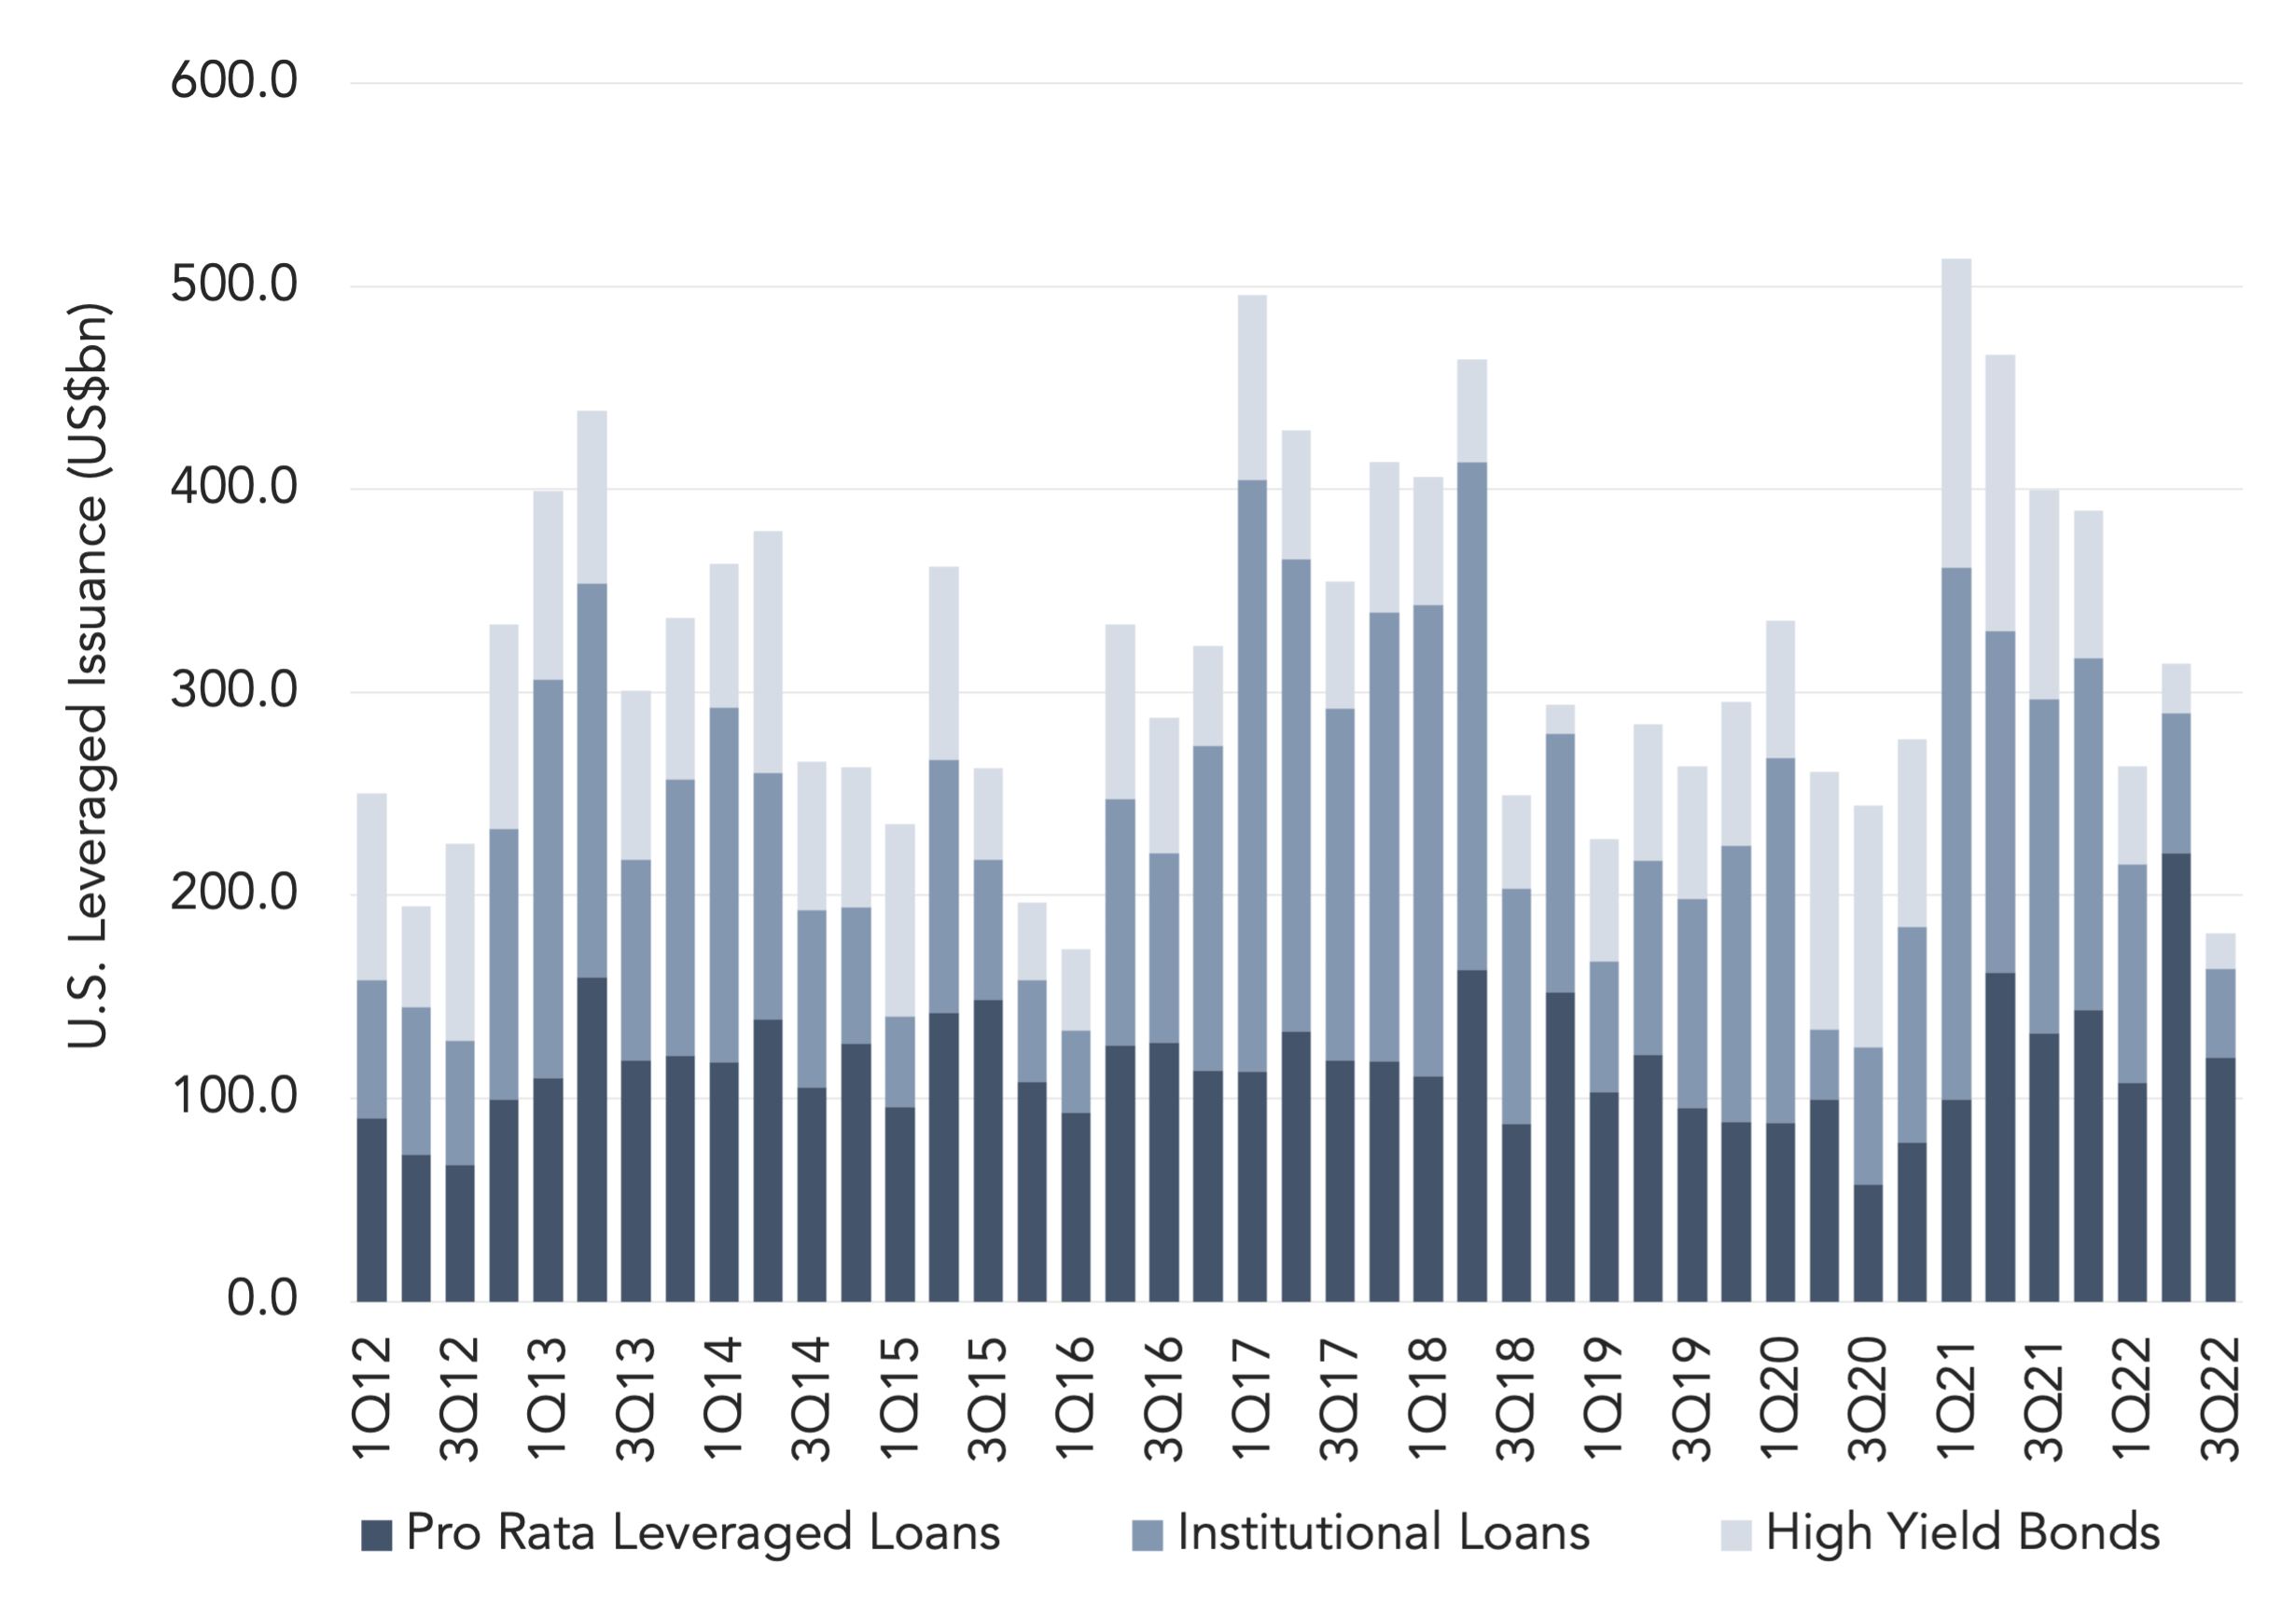
Less than US$182bn of leveraged loans and HY bond issuance was completed in 3Q22, the weakest quarterly results in over six years and a55% drop compared to the same time last year. At US$759bn, 1-3Q22 totals were down almost 45% compared to the year ago period. Market listlessness was largely the result of growing market uncertainty in the context of higher inflation numbers and prospects for economic growth into the fourth quarter. Less than US$165bn of leveraged loan volume was sold down in the broadly syndicated loan market in the third quarter, down 45% compared to the same time last year. At US$669bn, leveraged loan issuance through the end of September marked the weakest nine-month total since 2020. The most crushing impact from the economic headlines was felt in high yield bond market. Just over US$17bn in new issues cleared the market in 3Q22, the lowest quarterly total since 4Q18, and an 83% year over year drop. At US$90bn 1-3Q22 HY bond volume was 77% lower than year ago totals and the lowest since 1-3Q08 during the height of the credit crisis.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
