


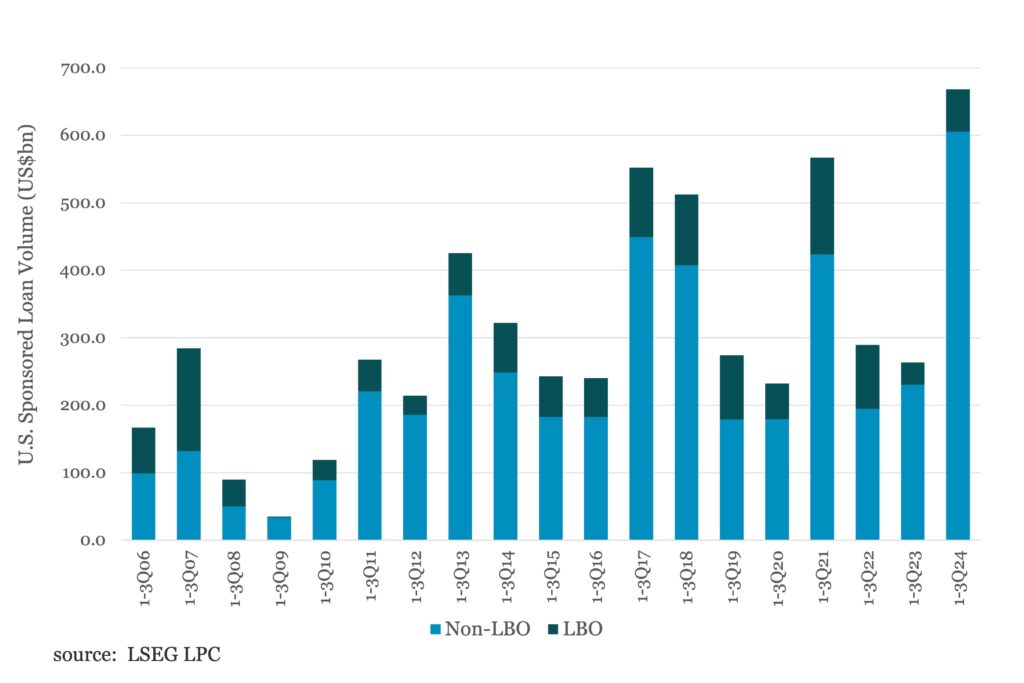
US sponsor tapped lenders for nearly US$186bn in loan financing in 3Q24, pushing 1-3Q24 issuance levels to a record setting high of US$668bn. There were caveats to the strong results however. At US$154bn, 1-3Q24 new sponsored loan volume was up 50% year over year, but represented only 23% of total sponsored lending for the first nine months of the year, down from 39% in the year ago period. At over US$62bn, 1-3Q24 LBO volume marked the strongest results since 2022, as improving market technicals favored renewed focus on broadly syndicated executions among large corporate issuers. At nearly US$606bn, non-LBO sponsored lending activity set a new record, up over three times year ago results, and 35% greater than the prior high of US$449bn raised in 1-3Q17. The vast majority of this represented refinancing activity as issuers trimmed spreads and pushed out maturities.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.