


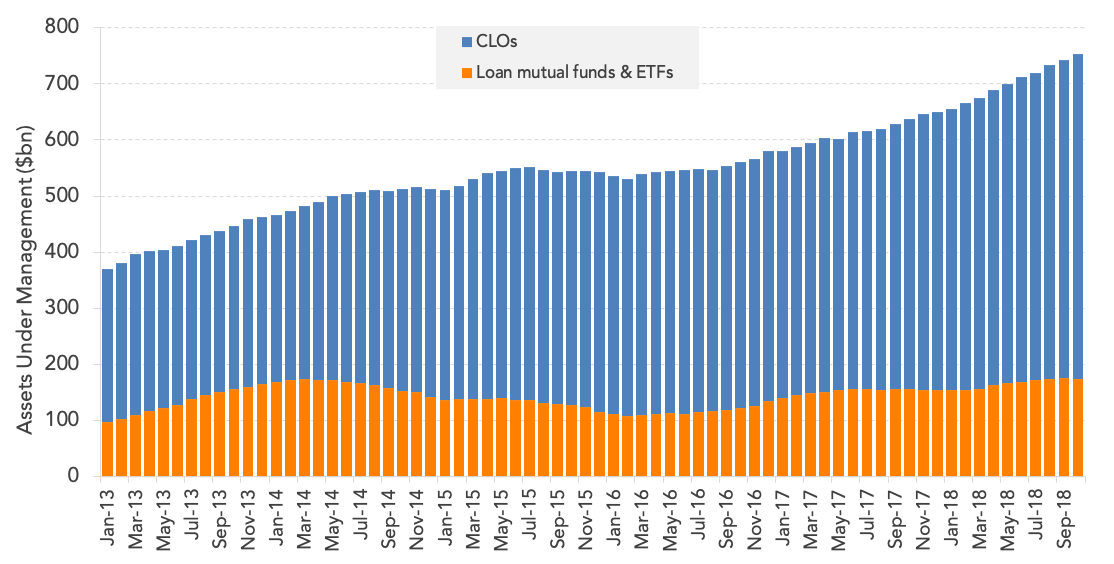
CLOs manage roughly half of current institutional loan outstandings with retail loan funds managing an additional 14%. Their respective shares have been steady, hovering around these levels since mid-2015 when CLOs first reached a 50% share of outstandings. Meanwhile, the pie has certainly grown larger. Institutional outstandings ended October at a new high-point of US$1.119trn, increasing 17% so far this year and up 35% since mid-2015. In that same period, CLO AUM have climbed 40% to US$579.45bn while loan fund AUM climbed 27% to US$173.61bn. While the rise in CLO AUM has been more linear, loan retail funds are subject to wilder swings in flows based on changing rate expectations among other variables. Loan fund AUM peaked in March of 2014 at US$174.04bn and due to slow and steady outflows, dropped to a low of US$107.52bn in February 2016, a period during which investor confidence was shot, equities plunged and asset prices across credit dropped more dramatically based on expectations of slowing global growth, the downgrade of U.S. credit in the fall and plunging oil prices. With few exceptions, AUM has grown steadily since, finally surpassing March 2014’s peak this September, reaching US$175.48bn by month-end. Conversely, CLO AUM has grown steadily, with few exceptions in the trend occurring as CLOs running off outpaced new issue or new issue slowed to a crawl especially in the fall of 2015 and early 2016 during the market freeze.
Contact: Ioana Barza
ioana.barza@refinitiv.com



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.