


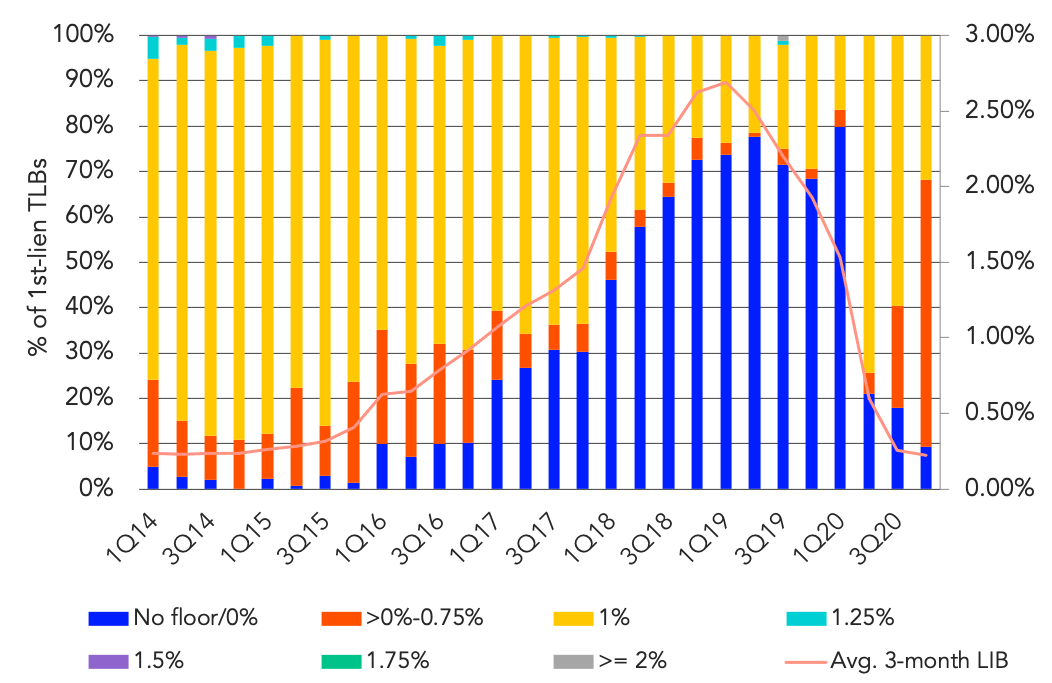
As the Libor rate remains at low levels, investors continue to demand Libor floors in the institutional market. The average 3-month Libor rate is at an average of 0.22% so far in 4Q20, this is down from 0.25% in 3Q20 and is roughly 130bp below 1Q20’s average. The precipitous drop in Libor rates led to the reappearance of Libor floors in the institutional market.
And while a whopping 91% of first-lien institutional term loans carry a floor so far this quarter, the shift towards lower floors that took place in 3Q20 has intensified this quarter. In the last two quarters, most deals (74% in 2Q20 and 60% in 3Q20) carried a 1% floor. This quarter, a much lower 32% of deals carry a 1% floor.
Instead, so far in 4Q20, the majority or 59% of first-lien institutional term loans carry a floor of 0.5% or 0.75%. This is up from 22% in 3Q20 and 5% in 2Q20. In the syndicated middle market, 59% of the deals have been done with a 0.75% floor. However, in the direct lending market, lenders say that 1% floors are sticking in this market so far.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
