The secondary market continues to come under pressure, with increased differentiation between the so called haves and have-nots. Flow names fell by roughly 100 bps in November and are off another 55 bps so far this month. At a broader market level, multi-quote institutional term loans also fell by around 100 bps in November and have given up another 75 bps in early December. 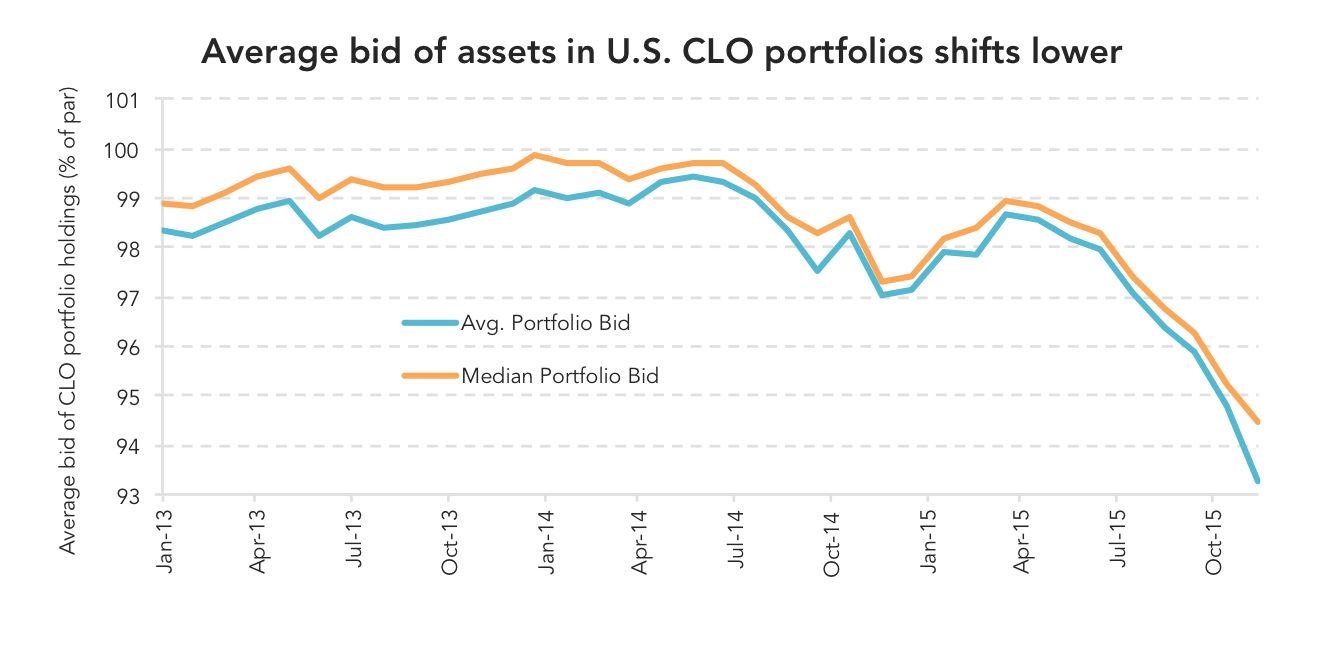 Sectors like oil & gas and mining have been hardest hit, though the good news is that they represent a small share of the loan market. In turn, the weakness in the secondary market has not surprisingly translated through to CLO portfolios. The average bid of U.S. CLO portfolio holdings has fallen to 93.26, while the median bid is down to 94.46. This represents over a five point drop from the high of 98.65 seen in April. Some other stresses have become a bit more visible with CCC holdings creeping up in some deals. Still, loan defaults remain low with over half (54%) of CLO 2.0s currently holding no defaulted assets in their portfolio, while an additional 31% of CLOs have sub-1 percent of their assets in default.




Latest news

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…