


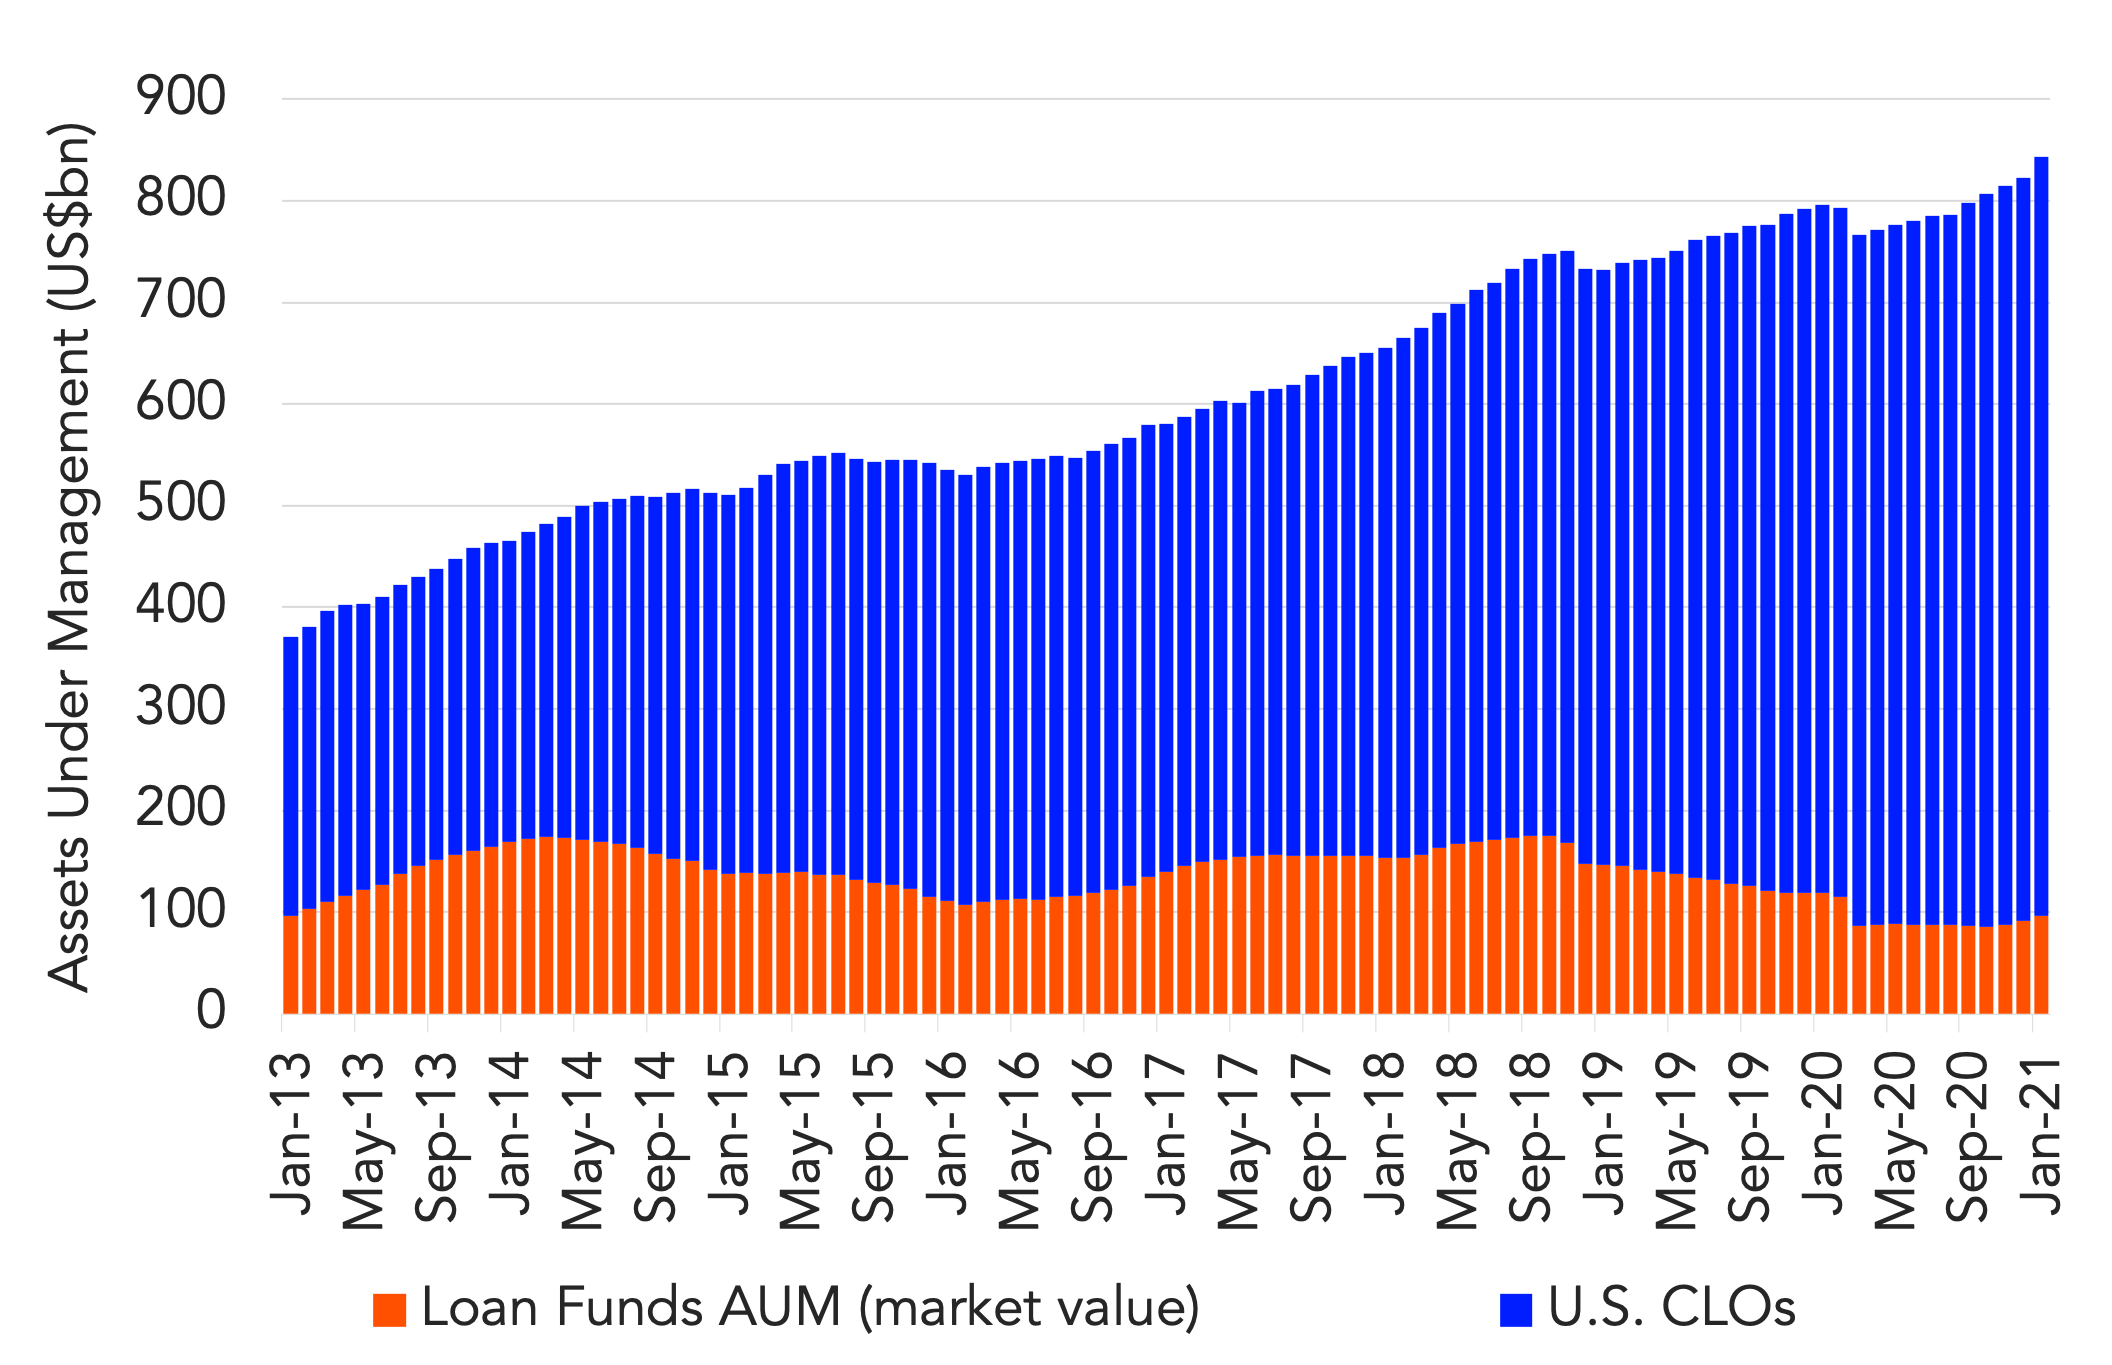
U.S. CLO AUM ended January at $747bn, up 10.3% YoY, with 17 new U.S. CLOs totaling $8.5bn pricing last month. It was the highest January volume since 2013 and included 4 deals with a total size over $600m. Despite the pandemic, CLO AUM has steadily risen throughout 2020 and into 2021, averaging $7.9bn of monthly new issue in the last 12 months.
Meanwhile, loan funds’ AUM was $96.5bn in January, its highest level since February 2020 before the pandemic sent loan funds’ AUM down 24% in a single month, from $114.8bn to $86.7bn, over Feb-March 2020. Still, AUM is well below peak levels, with January AUM down 19% YoY, and 45% lower than its September 2018’s peak of $175.5bn.
Loan fund inflows were behind the rise in AUM, posting $3.216bn last month, the highest volume since March 2017 ($4.208bn), and up from $397m in December. It was also the first consecutive months of positive fund flows since August-September 2018. CLOs now comprise 62.8% of the institutional loan market, up from 60% in December, while loan funds have a 7.5% share, up from 7% in December.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.