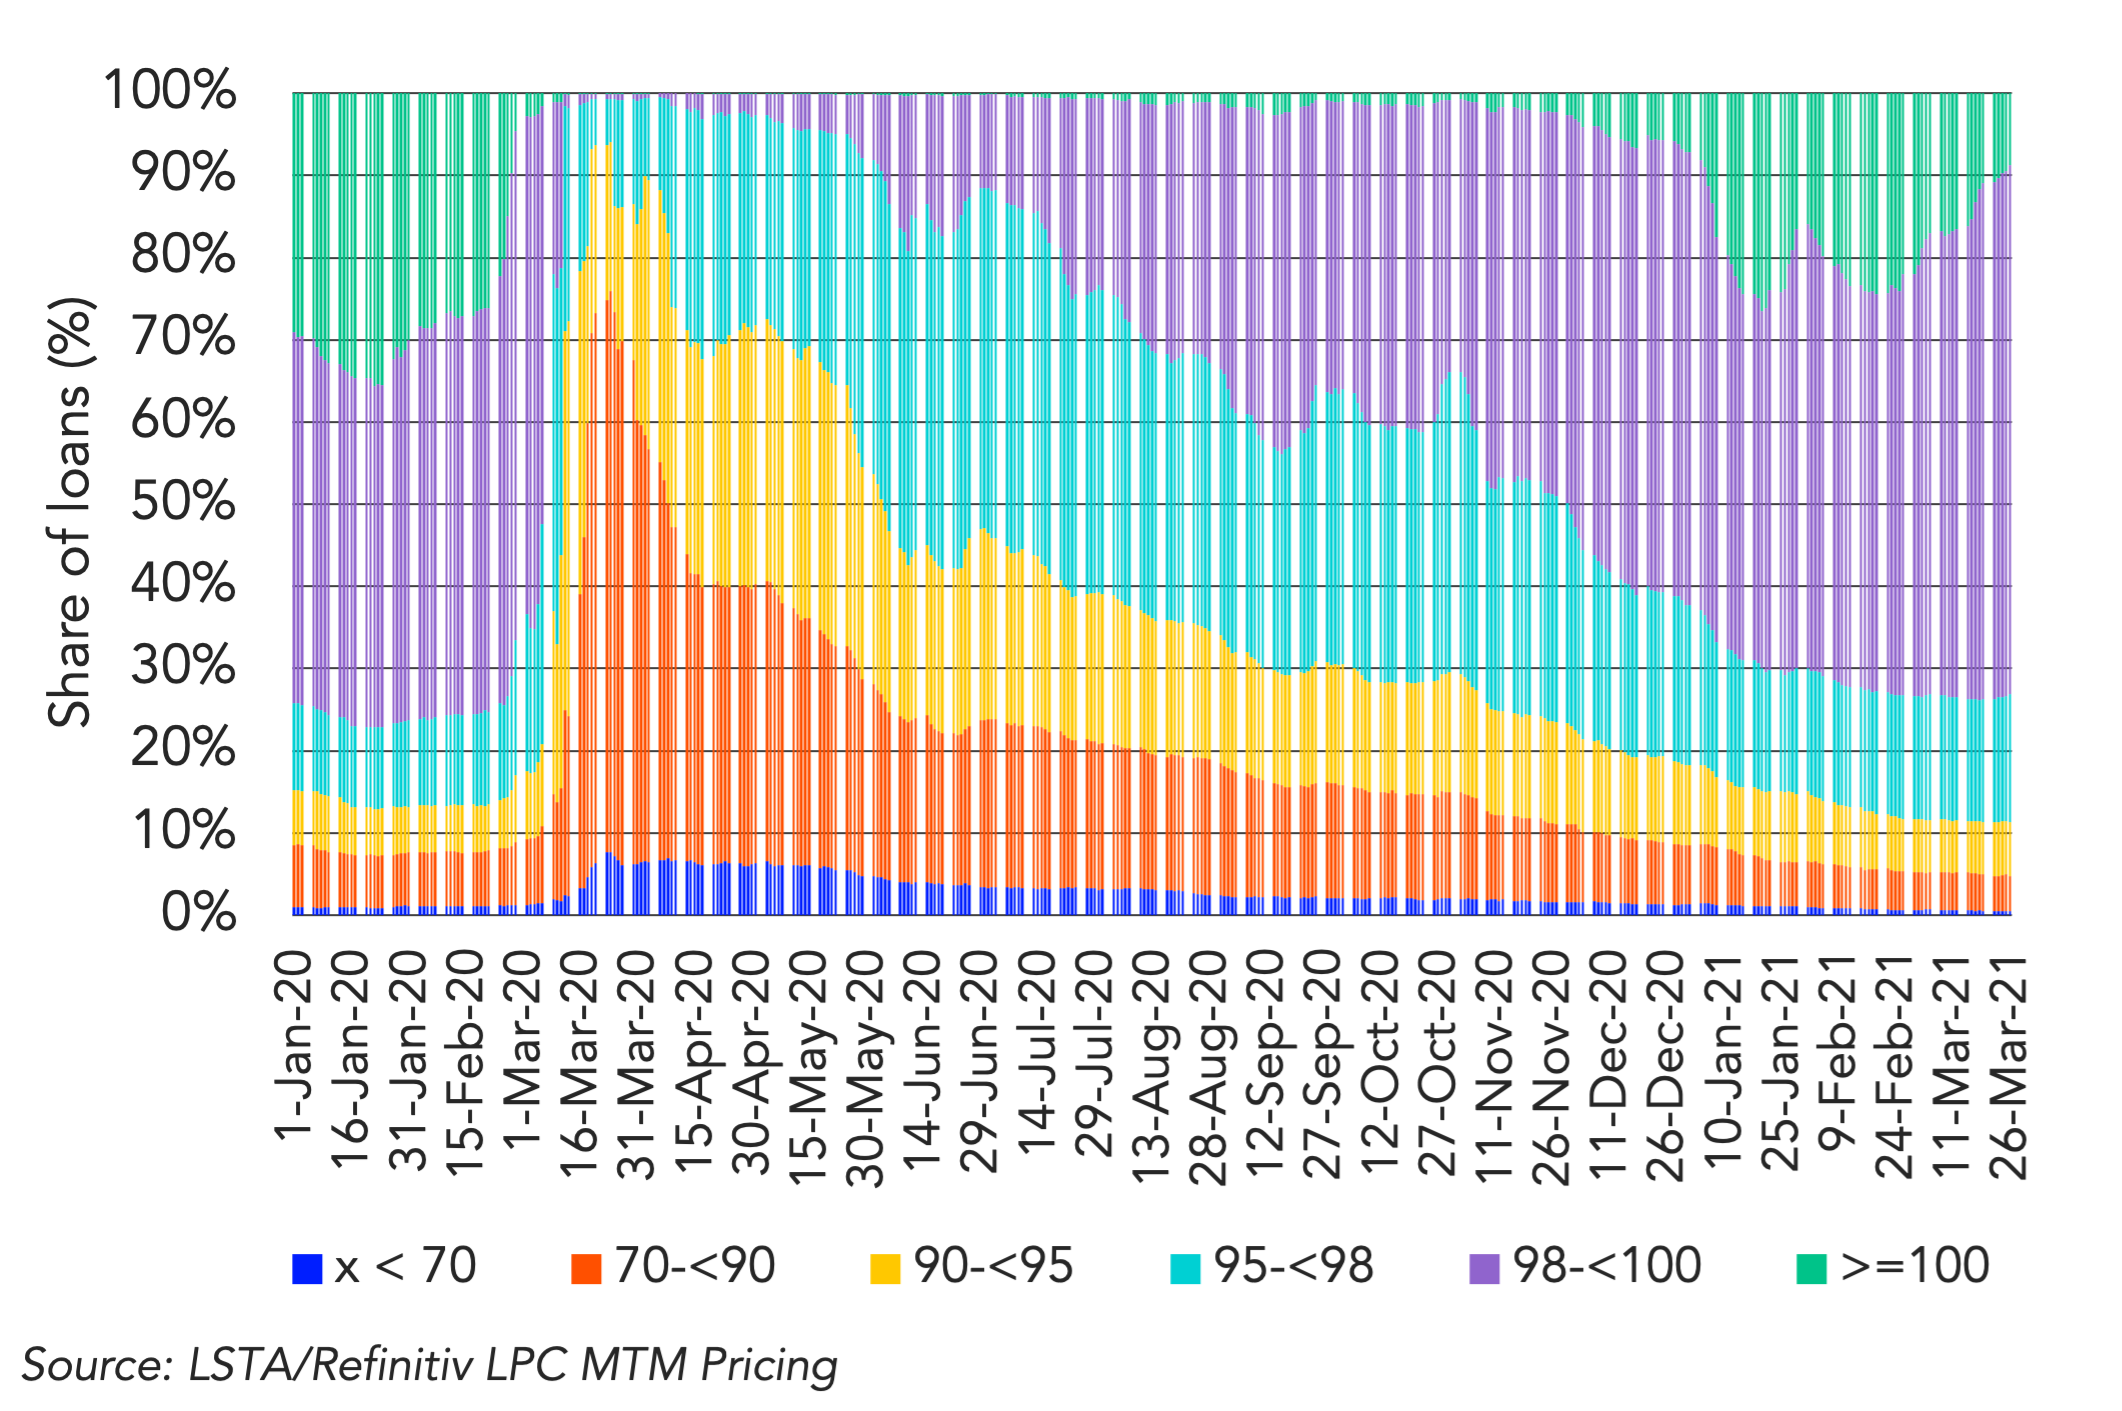
Prior to the pandemic, the average bid on the North America Overall-Market cohort of loans was in the 97.5 context, with half of loans bid between the 98-<100 level, bids above par made up a 35% share. At its lowest point last year, March 24, the Overall-Market average had collapsed to the 82 range, sending the share of bids marked between the 98-<100 to under 1%.
The secondary market has since rebounded swiftly and steadily, with the Overall-Market average increasing to the 97.7 context, as of last Friday, sending the share of loans marked between 98-<100 higher to 64%. On January 20, the par plus share reached 27% share of the market, its highest level post-Covid, but has since declined to 9% share of the market.
Bids priced above par declined 18% in the last two months. On January 20, bids between 95-<98 comprised 15% of the market. That number is up to 16%. Meanwhile, the share of loans in distressed territory (bid less than 80) has declined to 2%.
(Past performance is no guarantee of future results.)




Latest news

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…