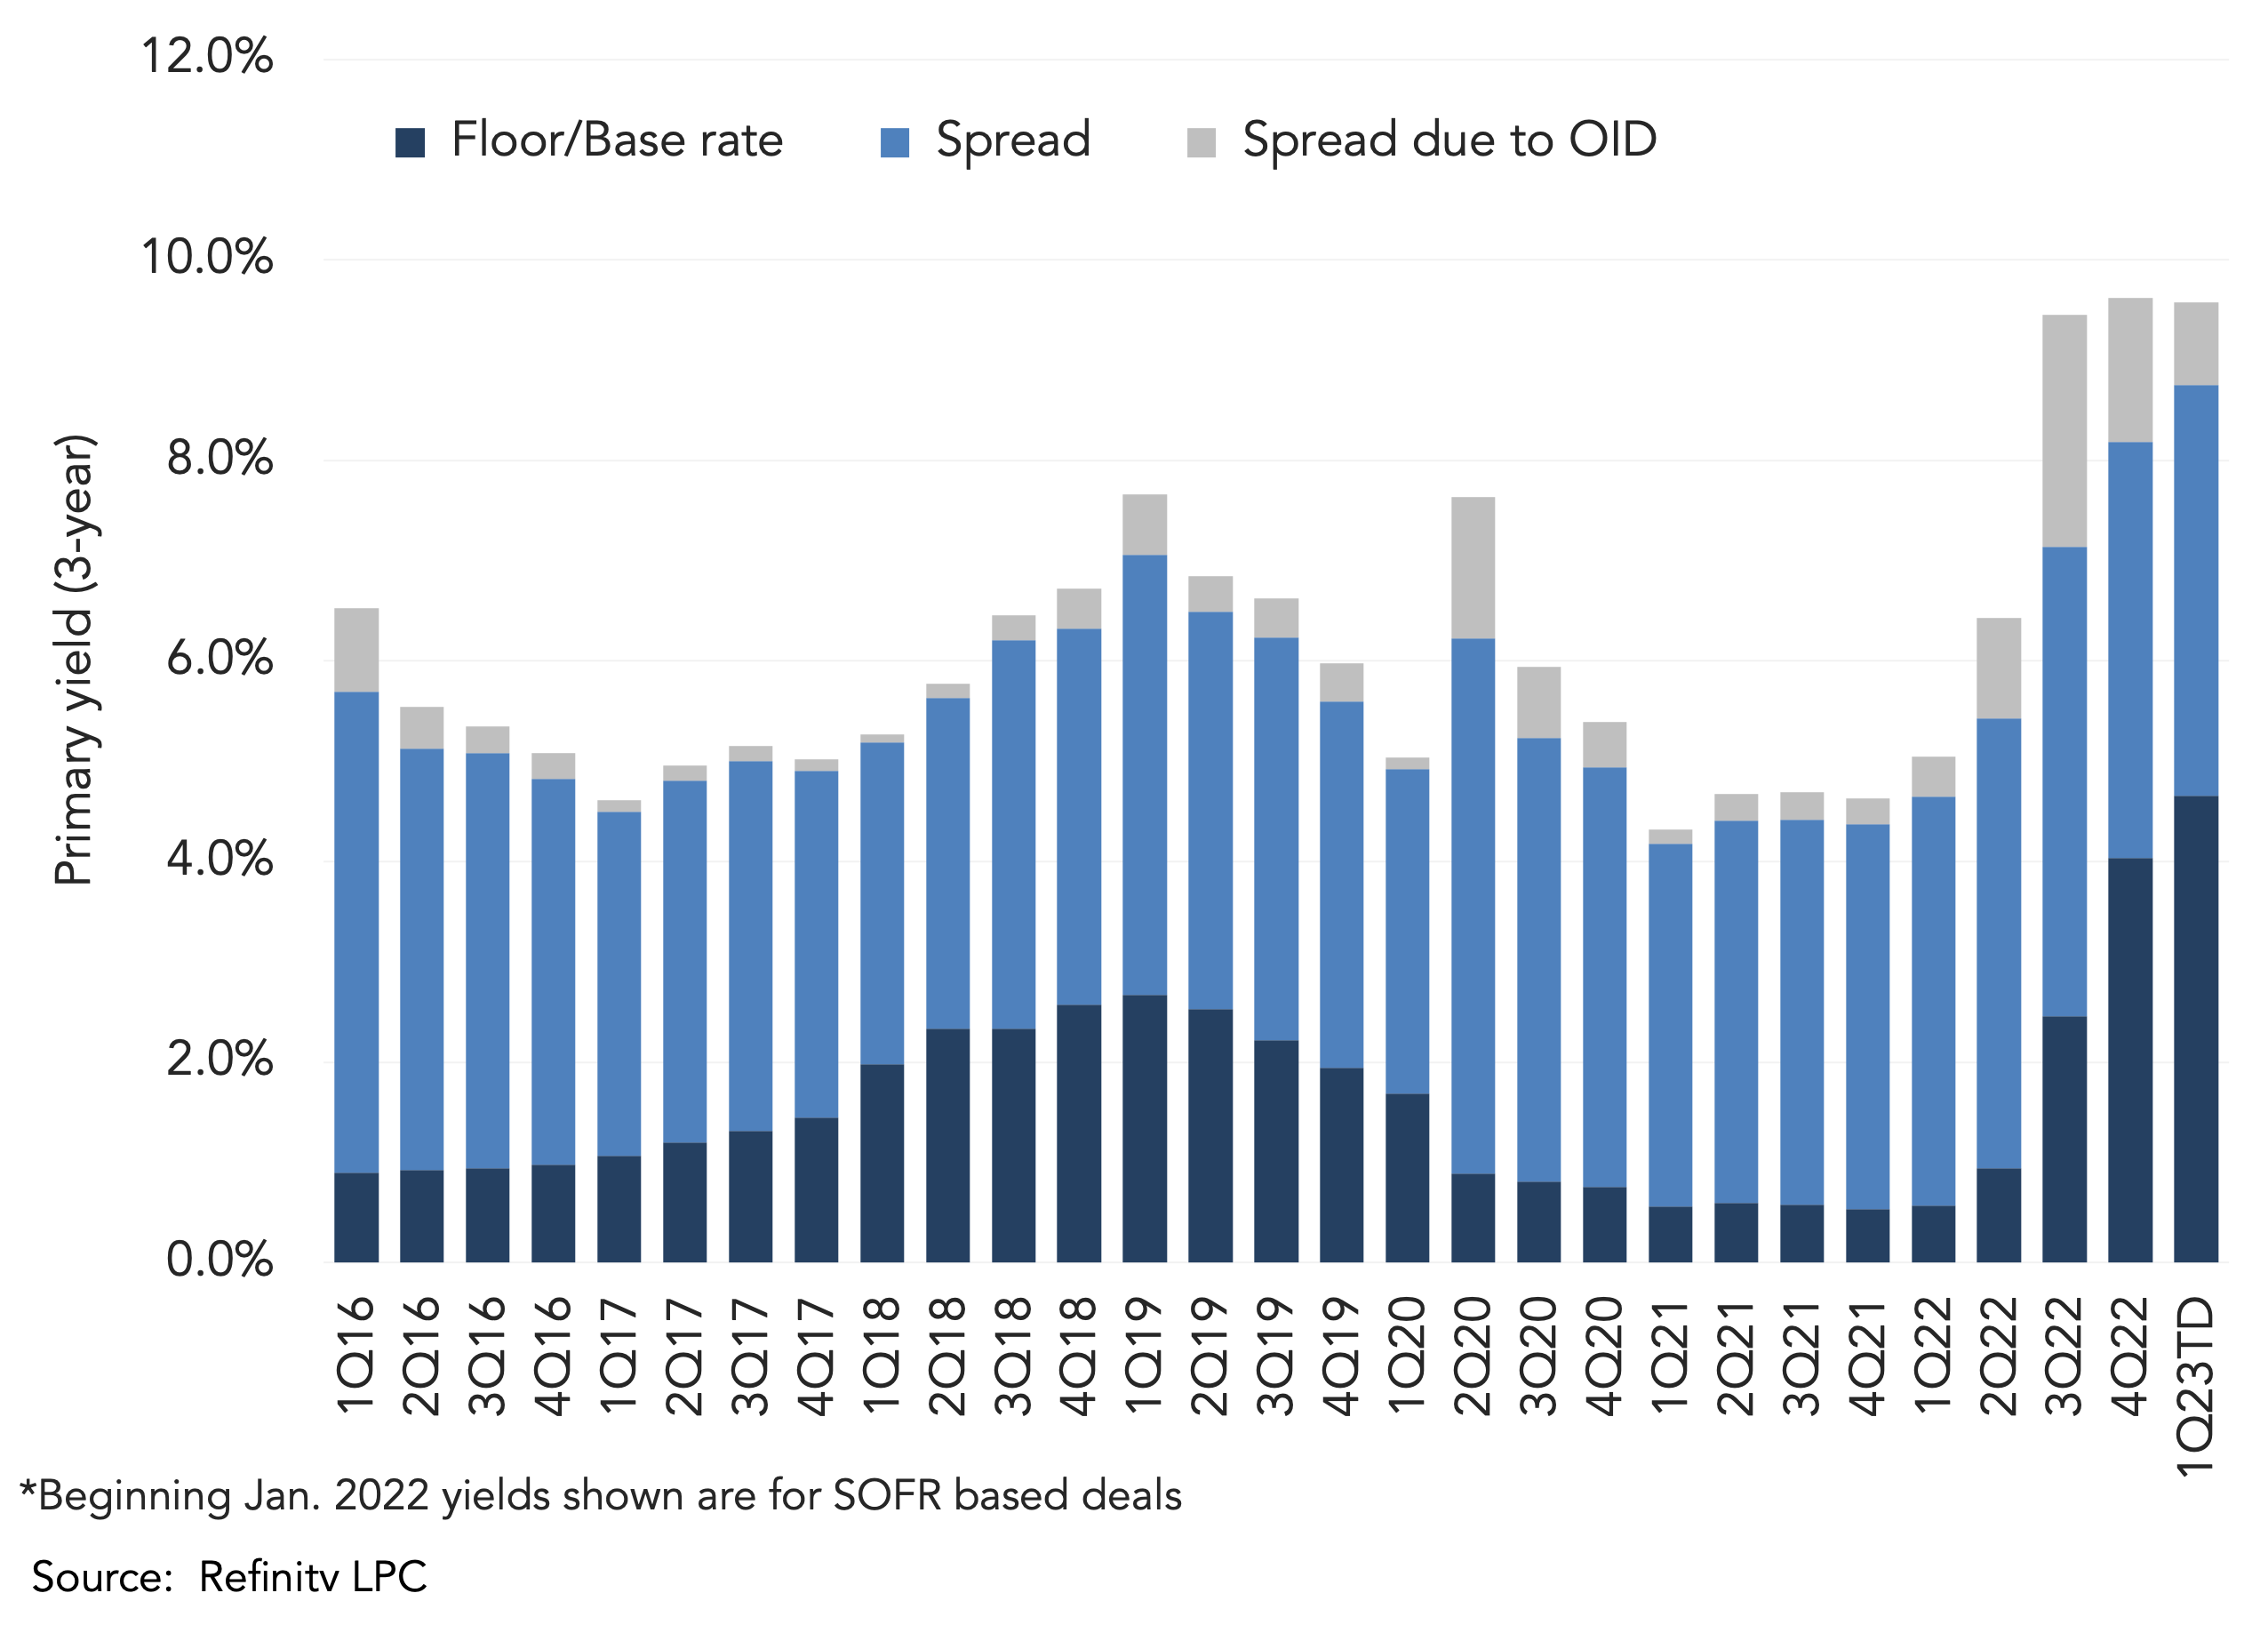
Average primary institutional yields have flattened in the last two quarters after soaring in 3Q22. At 9.57% so far in 1Q23, the average first-lien institutional yield, assuming a three-year term to repayment, is slightly below 4Q22’s 9.62%. While SOFR rates continue to rise, tighter discounts and spreads have compensated for the increase in base rates. The average OID is 97.91 so far in 1Q23, tighter than the 96.39 logged in 4Q22. Meanwhile, the average spread is 409bp so far this quarter, slightly down from 415bp in 4Q22. Most of the activity in the institutional market in 1Q23 has been from refinancings, as issuers are taking advantage of more receptive investors to address upcoming maturities. For the most part, deals have been well received allowing some issuers to cut costs, via lower OIDs or tighter spreads during syndication. So far this quarter, 32 downward price flexes have been reported, five more than the total logged last quarter, making it the highest quarterly level of price cuts since 4Q21.
(Past performance is no guarantee of future results.)




Latest news

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…