



Just shy of three months into 2016, CLO issuance remains stalled, logging less than US$3 billion in new vehicles through the end of February. This represents an 80% drop compared to the same time last year. More notably, only a few days into March, a single CLO has come to market via a US$406.75 million vehicle for Highbridge Principal Strategies – substantially off from the US$2.1 billion via 4 CLOs which were completed at the same time last year.
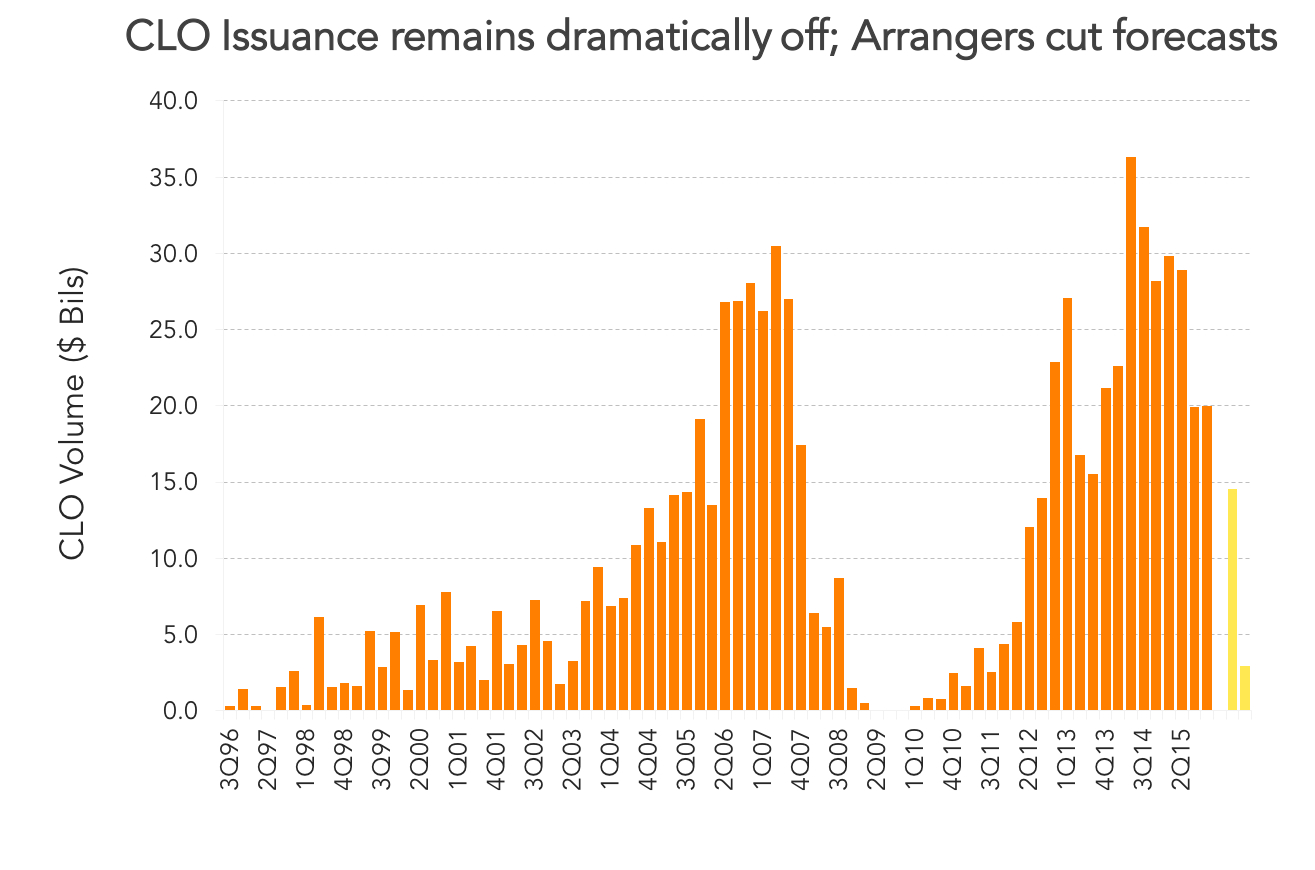 Although volatility across the capital markets and concerns around risk retention have factored into the slow down, issuance has also been hampered by higher yielding assets offered in the secondary market via older funds. None of this bodes well for CLOs, the largest and most natural buyer of leveraged loan assets. Arrangers including JPMorgan, Wells Fargo and most recently Deutsche Bank have reduced their projections for 2016 CLO volume, to expectations ranging from a low of US$35 billion to a high of US$60 billion, a 20-40% from forecasts set at the end of last year.
Register now! TR LPC’s 4th Annual Middle Market Loans Conference on April 27, 2016.
Contact: Maria Dikeos
maria.dikeos@thomsonreuters.com



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…