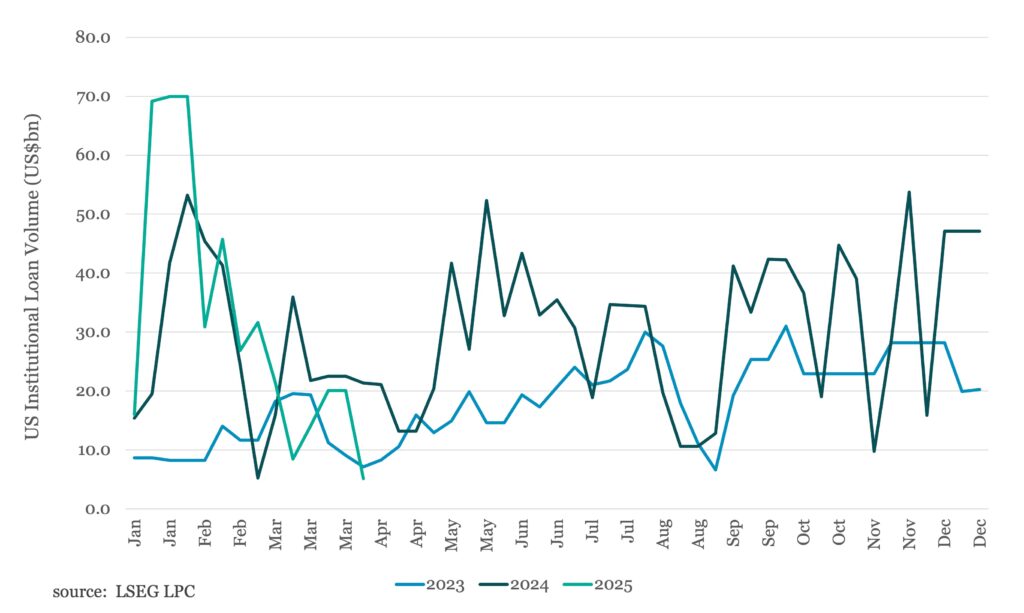
Early in the second quarter, the institutional loan calendar stands at just over US$5bn, the lowest level in 5 years. Currently there are known 7 deals in market only two of which are M&A related and north of US$1bn in size. The balance represent refinancings and a small dividend recap. More noteworthy than the size of the pipeline, is the pace at which they are lining up to move/clear the retail syndicated loan market. Amid headlines spotlighting tariff wars and market uncertainty, a number of arrangers are slow walking deals in an effort to manage growing lender concerns around credit risk. A US$1.1bn term loan B backing HIG Capital’s acquisition of Converge Technology Solutions (one of the two M&A credits in the pipeline) has been postponed. So too has the US$525m TLB backing a dividend recap for ITG Communications. The near term postponement of these two deals alone brings the pipeline down even further to less than US$3.5bn.



Latest news
Number of smaller funds dwindles
Analysis of fund-close data found that vehicles valued at under $250m have seen a rapid decline since 2024.While PEI Private…

US Private Credit Transparency Highlights Uneven BDC Performance
Credit performance across business development company (BDC) portfolios remains uneven, although reported losses and non-accruals were broadly stable quarter over quarter, according to Fitch Ratings’ Private Credit Transparency Monitor for 2Q26.