



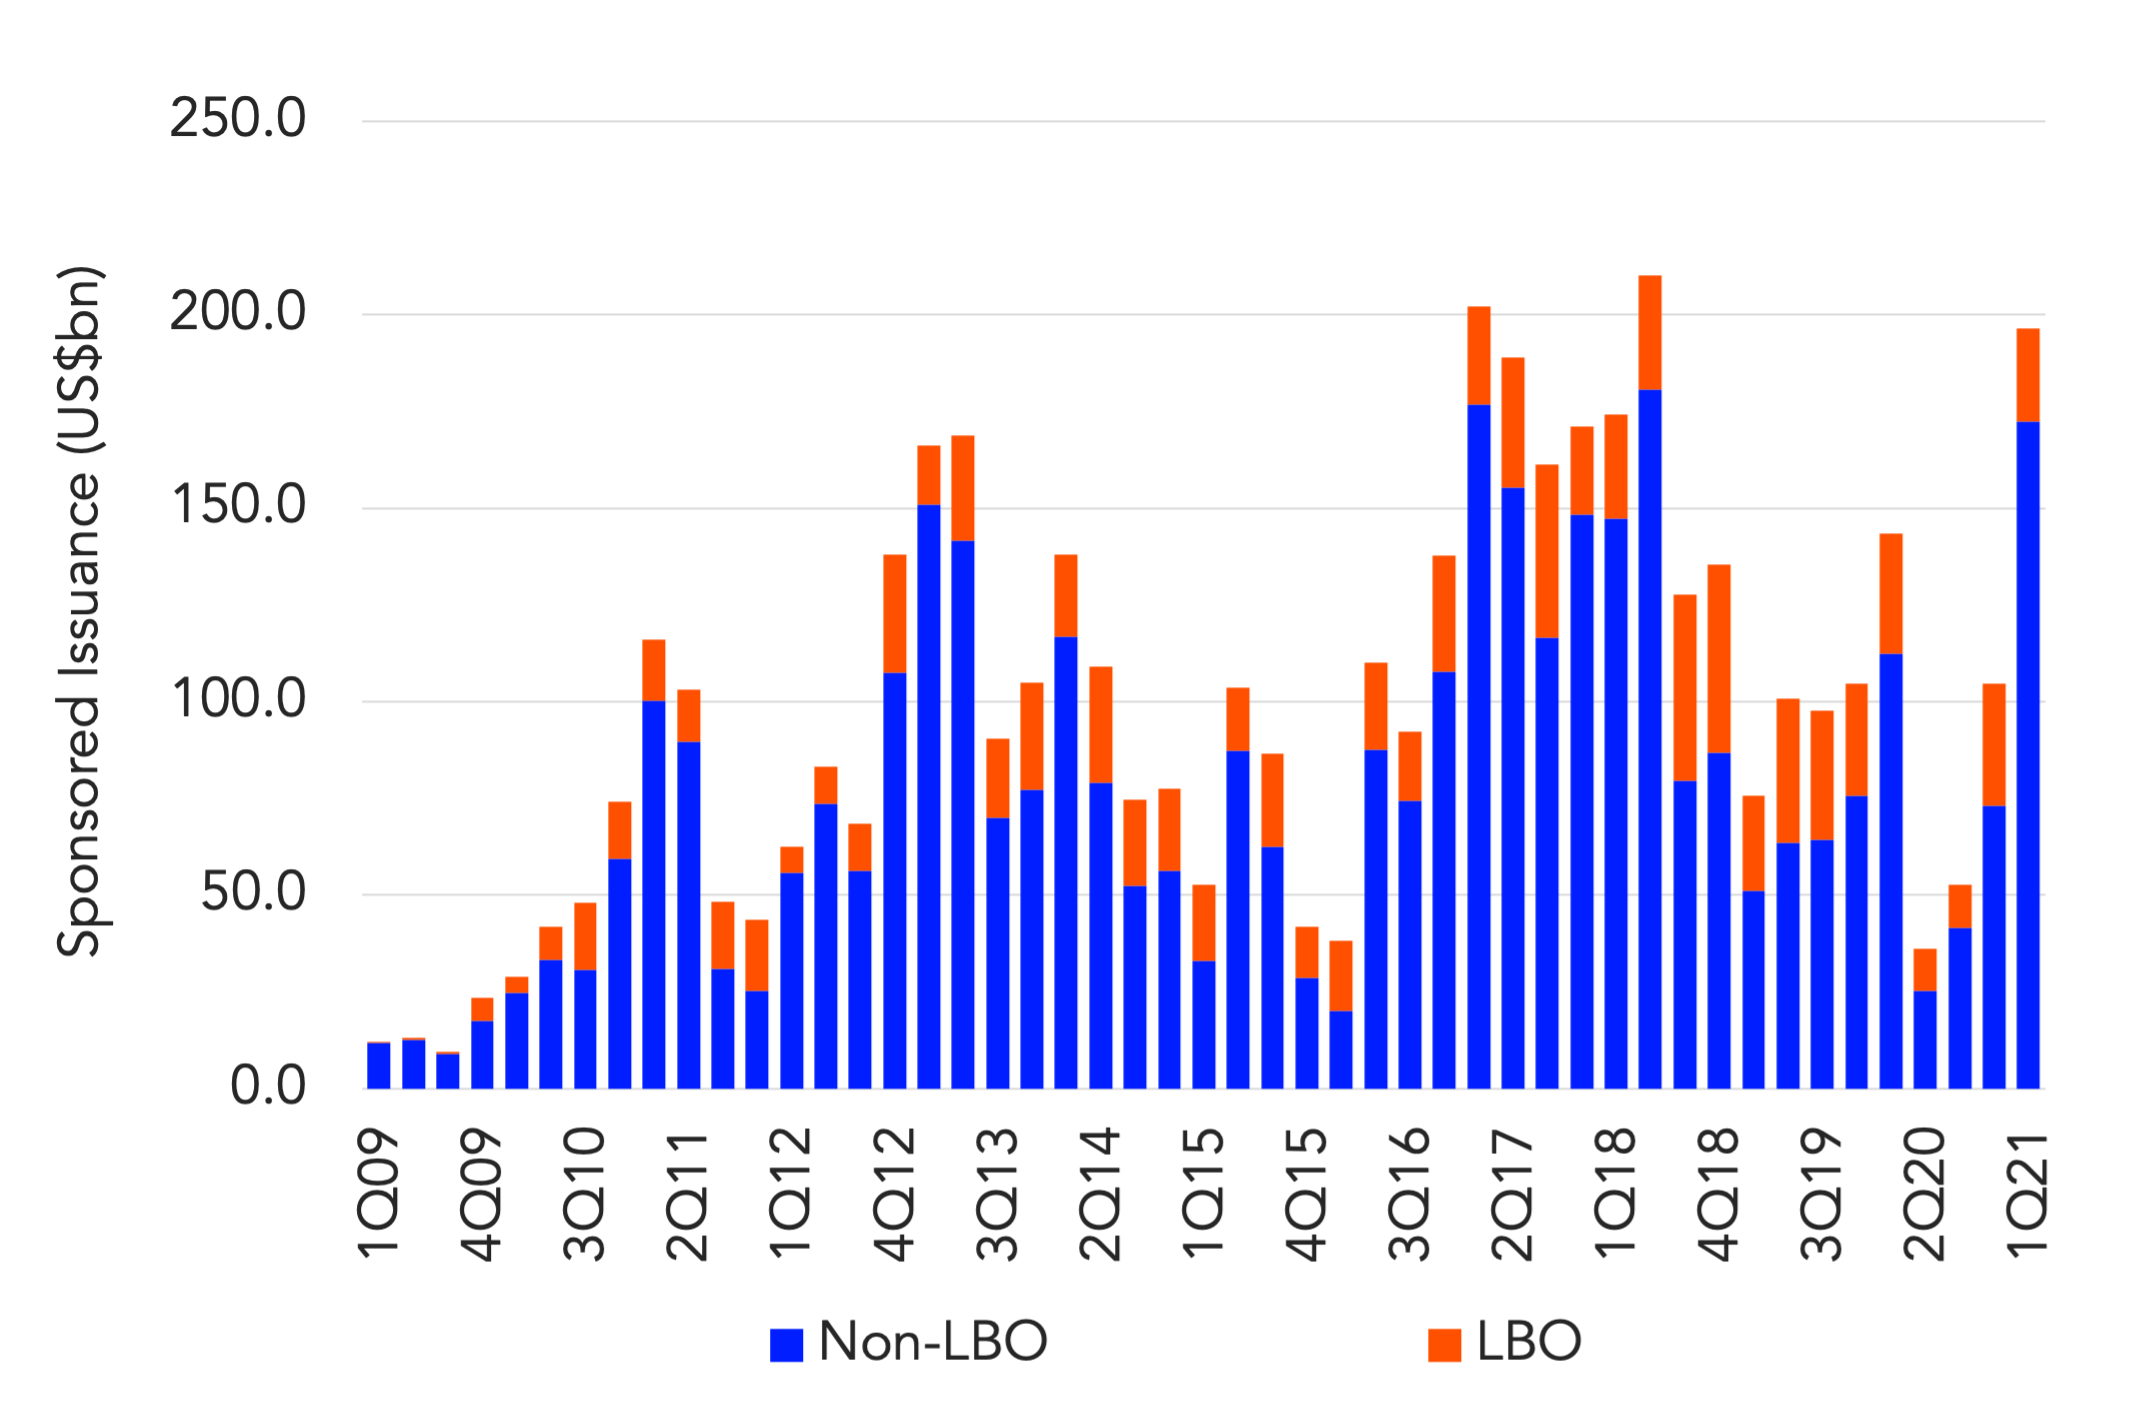
Private equity sponsors returned to the loan market in 1Q21 to clear US$196.5bn through retail syndication, the highest quarterly total since 2Q18 and the third highest on record.
At US$128bn refinancings represented 65% of the 1Q21 sponsored loan calendar as issuers tapped lenders for repricings and covenant loosening. A flurry of opportunistic divided recaps also made their way into the market in January and February amid a thiner than anticipated supply of new loan assets. By March however, market tone shifted somewhat.
While liquidity remained firmly in place, refinancing fatigue and the thinner spreads that came with it set in. With a slow but steady return of new loan assets, refinancings which reached a high of US$57.2bn in February (up from US$32bn in January) closed out the month at less than US$39bn. By quarter end, LBOloan volume totalled US$24.4bn – over US$10bn of which was raised in March alone – down slightly compared to year ago levels.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
