


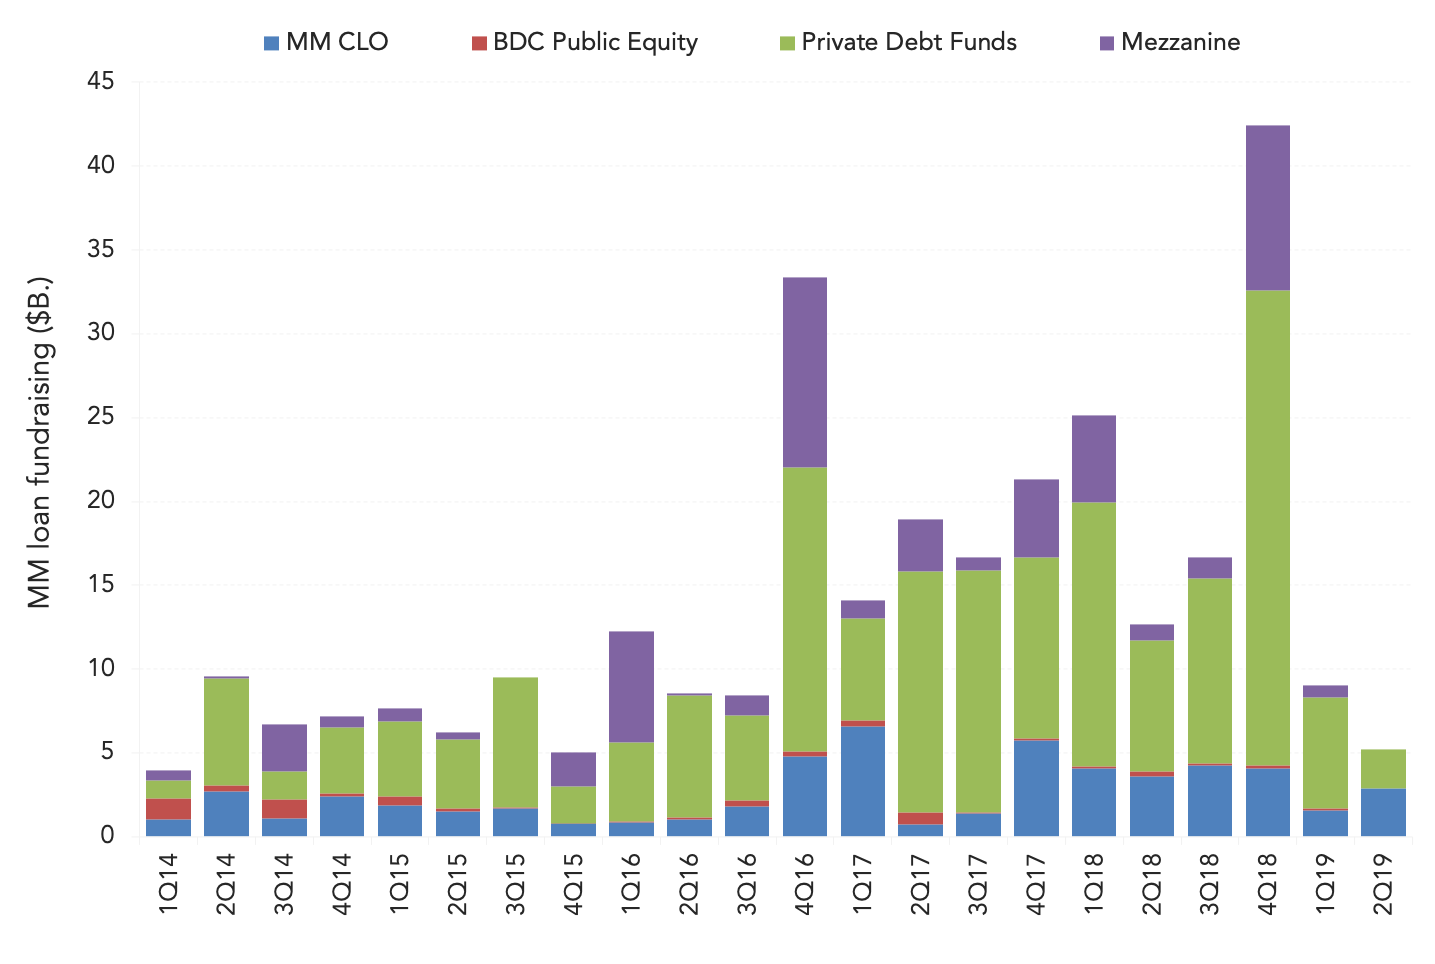
After a record US$97bn in inflows into middle market direct lending in 2018, the fundraising environment is off to a slower start in 2019 with US$14bn tracked year to date. In 1Q19, LPC only tracked about US$9.0bn in inflows following a record $42.4bn tracked in 4Q18. But announcements and activity is starting to pick back up after a sluggish first quarter. For starters the CLO market is showing much better momentum. After only $1.5bn in MM CLOs priced in 1Q19, almost $3.0bn has already priced in April alone. Antares, GSO, Golub, Carlyle and Owl Rock hit the market in April with MM CLOs. Owl Rock’s $597M CLO represents the latest first time middle market manager to hit the market following Deerpath in December 2018. And Barings BDC also announced this week its first term debt securitization, but it is static with no reinvestment period. After hitting very elevated levels in 1Q19, MM CLO AAA liability spreads are mildly tightening back to more reasonable levels. Spreads averaged about 175bps in 1Q19, but in April, that has fallen to about 165bps. Also, on the private debt fund front, things are picking up. On their most recent earnings call, Blackstone indicated that $7.7B has already been raised for GSO’s new private direct lending fund. The platform is expecting to reach $10-$12bn by year end. Meanwhile, Neuberger Berman announced a final close on its latest private debt fund at US$1.7bn, surpassing its goal of US$1.5bn. This is more than double the amount that their prior fund raised. In April, Adams Street filed for its Adams Street Private Credit BDC, and sources indicate there are several more private BDCs brewing which will be announced as the year progresses.
Contact: Fran Beyers
frances.beyers@thomsonreuters.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
