



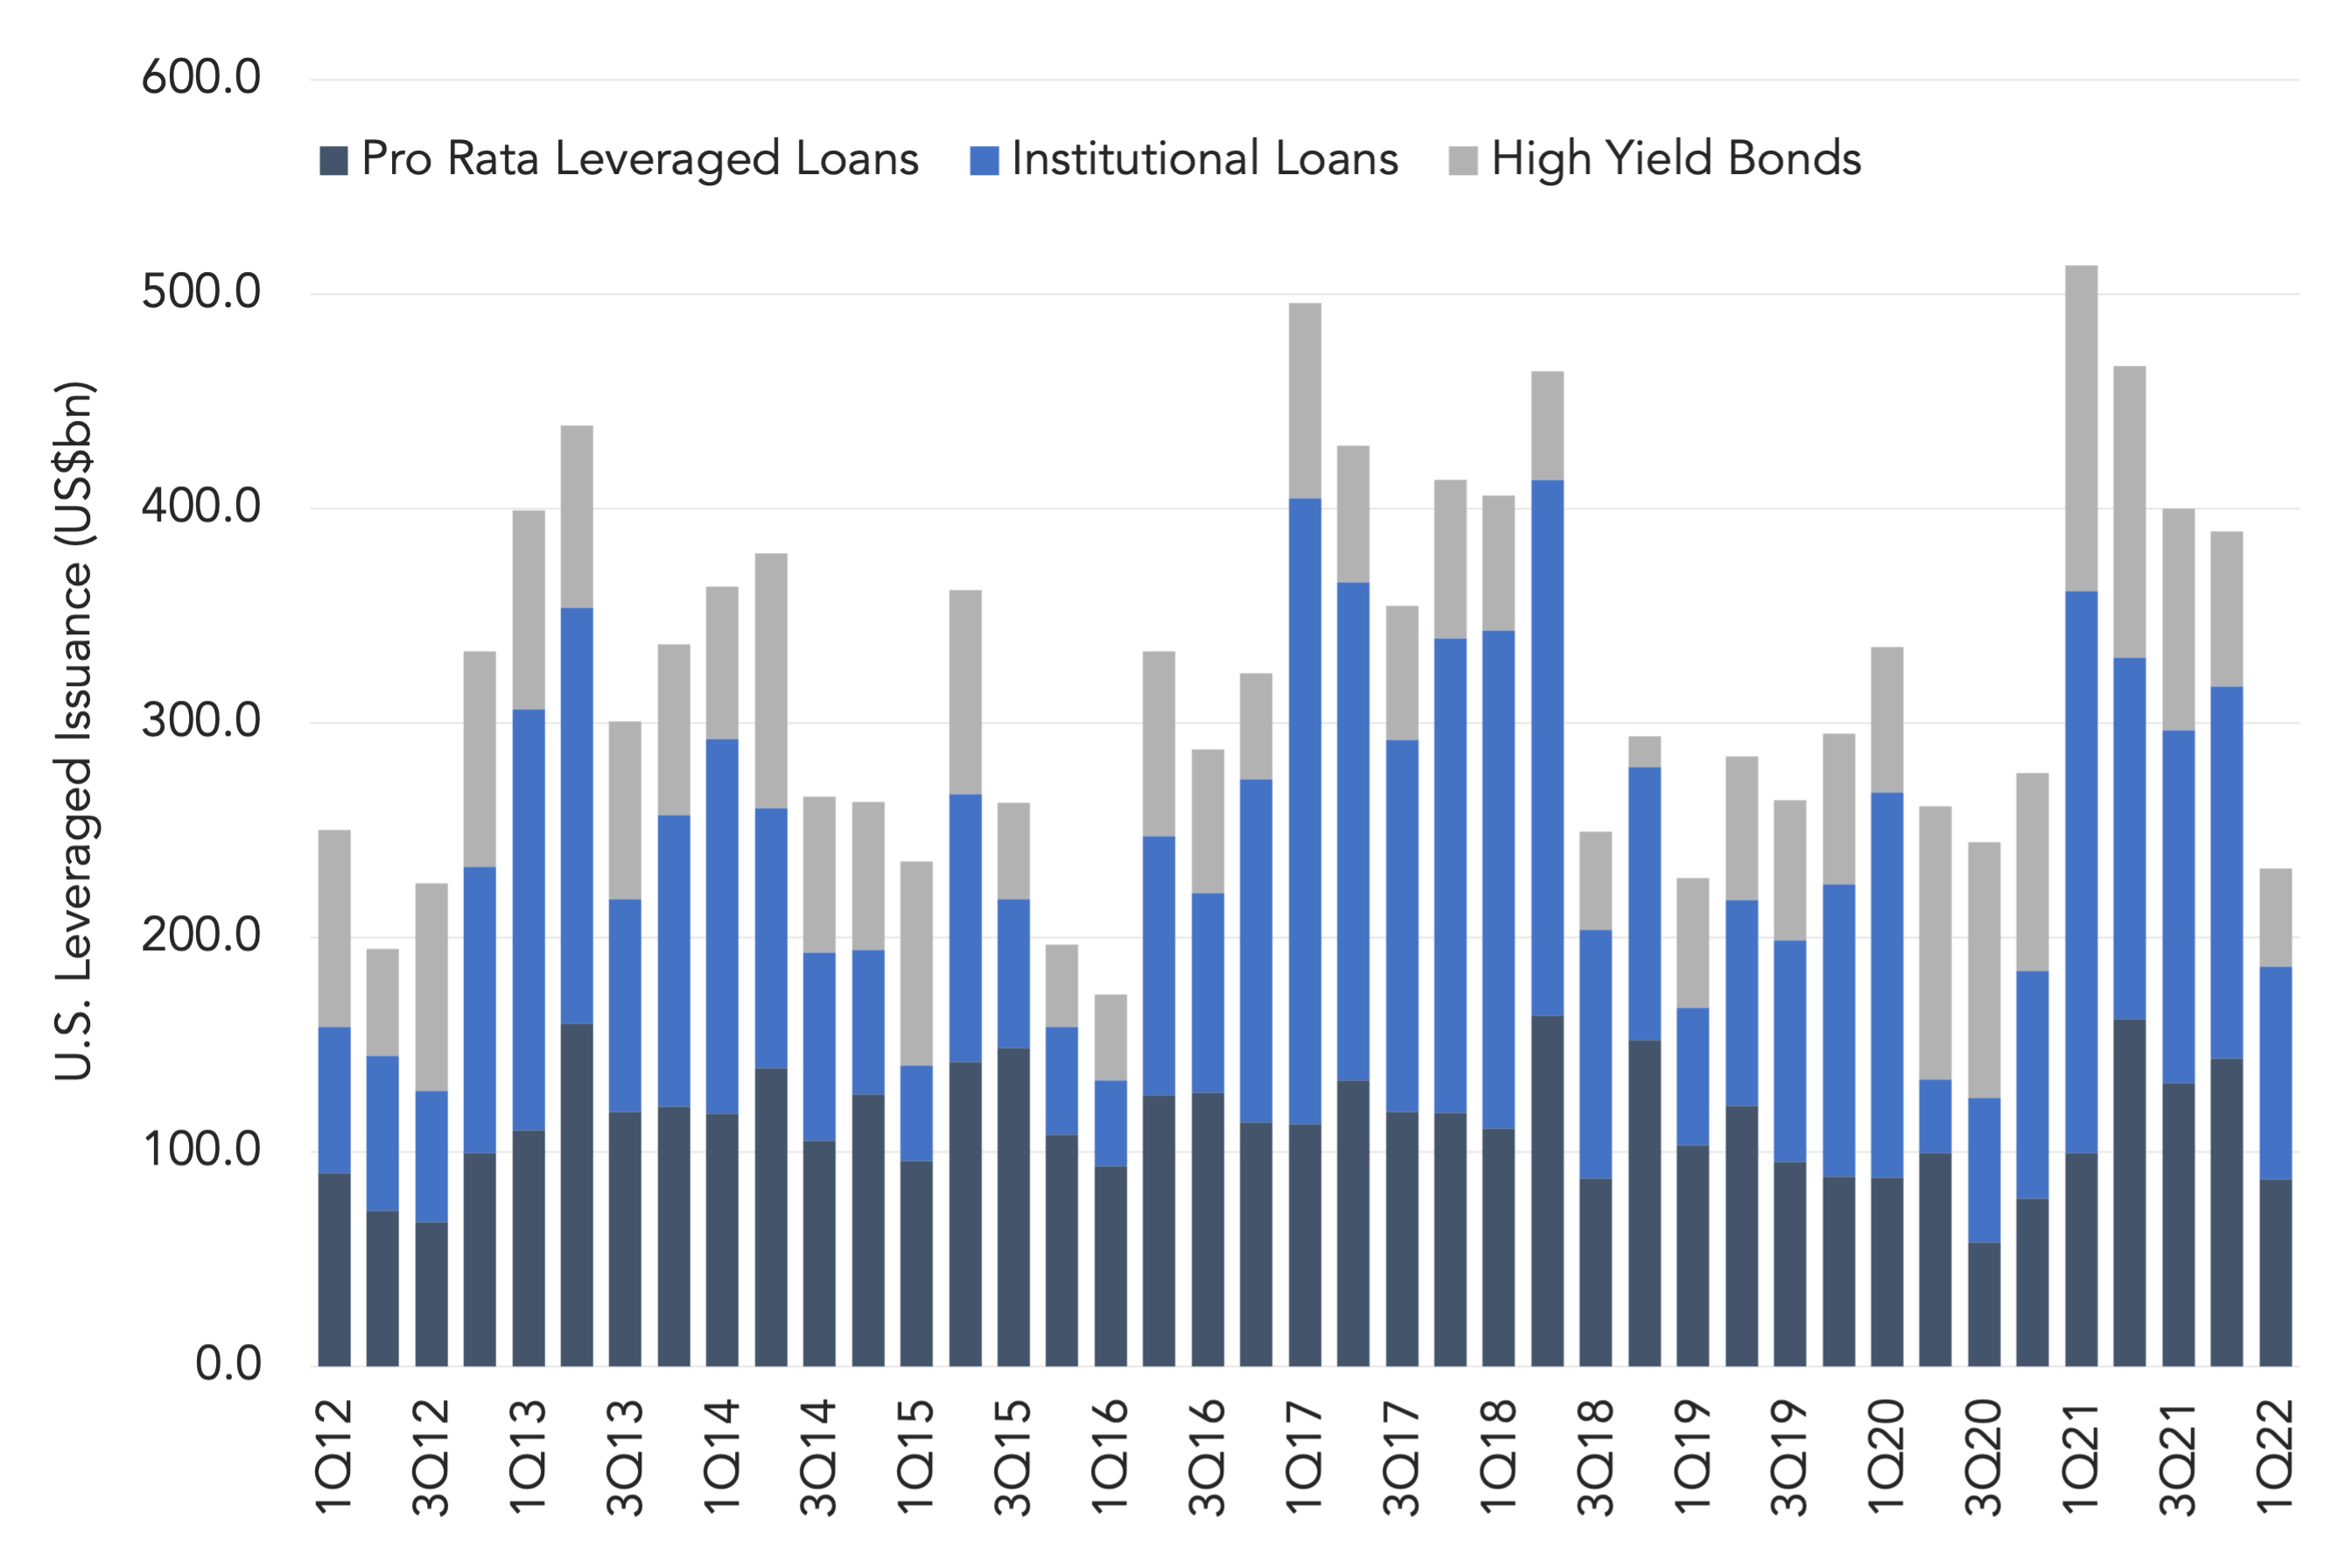
The combination of SOFR rollout, inflationary pressures, labor and supply chain issues and the war in Ukraine (as well as its impact on commodities) all tinged the US leveraged loan market in 1Q22, contributing to lower volumes and increasing spreads. At US$186.3bn, 1Q22 leveraged loan volume was down 48% compared to year ago levels.
At US$98.92bn, leveraged institutional issuance was down a more substantial 62% year over year, while the HY bond market plummeted almost 70% year over year. What was less clear was whether the increased market volatility was rooted in the need for price discovery or more troubling market technicals. The slow down of CLOs printing did not help matters.
Nor did the flurry of loan and bond retail fund outflows. The pro rata market was more sanguine. Arrangers noted that it all came down to what borrowers were trying to get done and where they were trying to get it done. Lenders say that there are still a number of opportunities – including underwrites – but these are likely to come with wider flex provisions.
(Past performance is no guarantee of future results.)




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Reading the Board
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Different Numbers, Different Stories
In Season 2 of Billions, Bobby Axelrod takes his lawyer Orrin Bach to an empty Yonkers racetrack in the dead of night.