


1Q24 US Leveraged volume up 46% year over year; Highest quarterly total in over 2 years
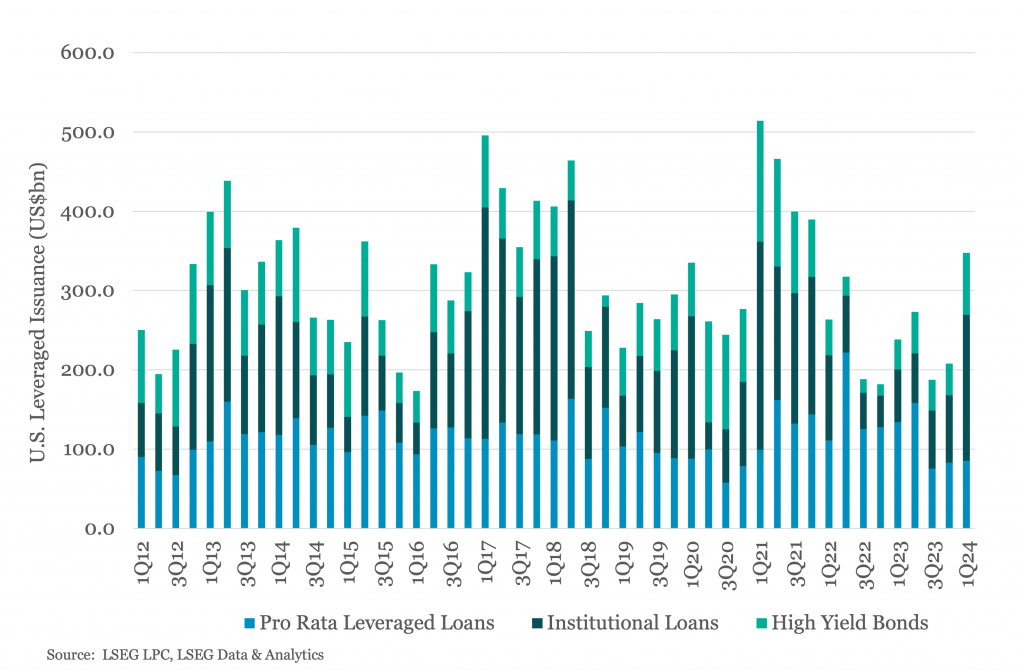
US leveraged lenders completed US$347.5bn of issuance across the high yield bond and leveraged loan markets in 1Q24, a 46% increase compared to the same time last year and the strongest quarterly results since 4Q21. More interesting was the mix of assets which supported borrowers. Having struggled to gain momentum over the last two years, high yield bond issuance took off in 1Q24 to log nearly US$78bn of issuance, nearly two times year ago totals and the highest quarterly total since 3Q21. In turn, amid strengthening appetite among CLO investors and tighter AAA pricing, leveraged institutional loan volume was up nearly three fold year over year at US$184.1bn. The total also marked the strongest quarterly results since 1Q21. Repricings and refinancings fuelled the leveraged pipeline early in the year as lenders and arrangers looked to the M&A market for new lending opportunities (which were limited). Against this backdrop, pro rata lending was down 30% year over year at US$85.4bn.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
