



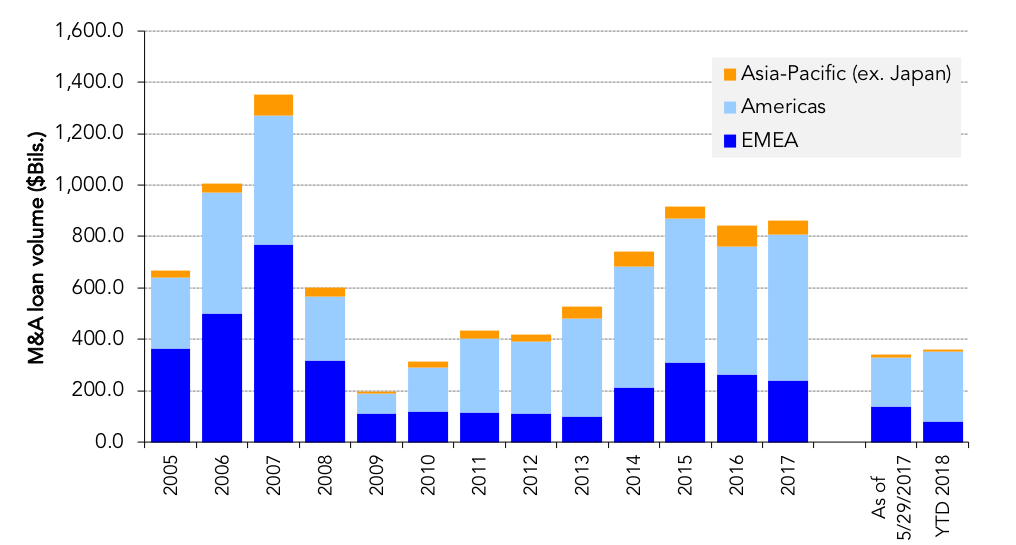
About US$360Bn of global M&A loan has worked its way through the retail markets so far this year, an increase of 5% over the same time last year. Roughly 76% of deal flow has originated in the Americas which have raised over US$273Bn in new M&A loan assets during the first five months of 2018, a 43% jump over the same time last year on the back of a series of jumbo deals. The news was less auspicious in Europe, the Middle East and Africa (EMEA). Less than US$80Bn in M&A loan volume has been completed so far this year, down 44% compared to the year ago period. EMEA regional lenders note that it comes down to a delicate balance between opportunities to put money to work and rising concerns around the timing of any cyclical downturn, eroding deal terms and, more recently, unsettling political headlines. In the leveraged loan market specifically, European lenders have selectively declined opportunities to underwrite buyout financings with what they deem to be egregiously loose terms. In Asia Pacific (ex. Japan) completed M&A loan volume is slightly off from year ago totals at just over US$8.3Bn although the US$30.85Bn bridge loan backing Japan-based Takeda Pharmaceutical’s takeover of Shire Plc marks the largest loanfinancing in Asia on record.
Contact: Maria Dikeos
maria.dikeos@thomsonreuters.com



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
