


Assets under management (AUM) increased in April for both U.S. CLOs and retail loan funds. CLO AUM edged up to $430 billion, while loan mutual funds & ETFs AUM increased to nearly $112 billion. Over the past year, CLOs and retail loan funds have experienced contrasting fortunes. In that time period, U.S. CLO AUM is up roughly $28 billion, while loan fund AUM is down by nearly the same amount ($27 billion). Recently, CLO AUM has been aided by steady though not spectacular issuance, as CLO deal flow trended marginally higher in April, amounting to $5.9 billion (14 deals), up from $4.9 billion in March and $2.5 billion in February. 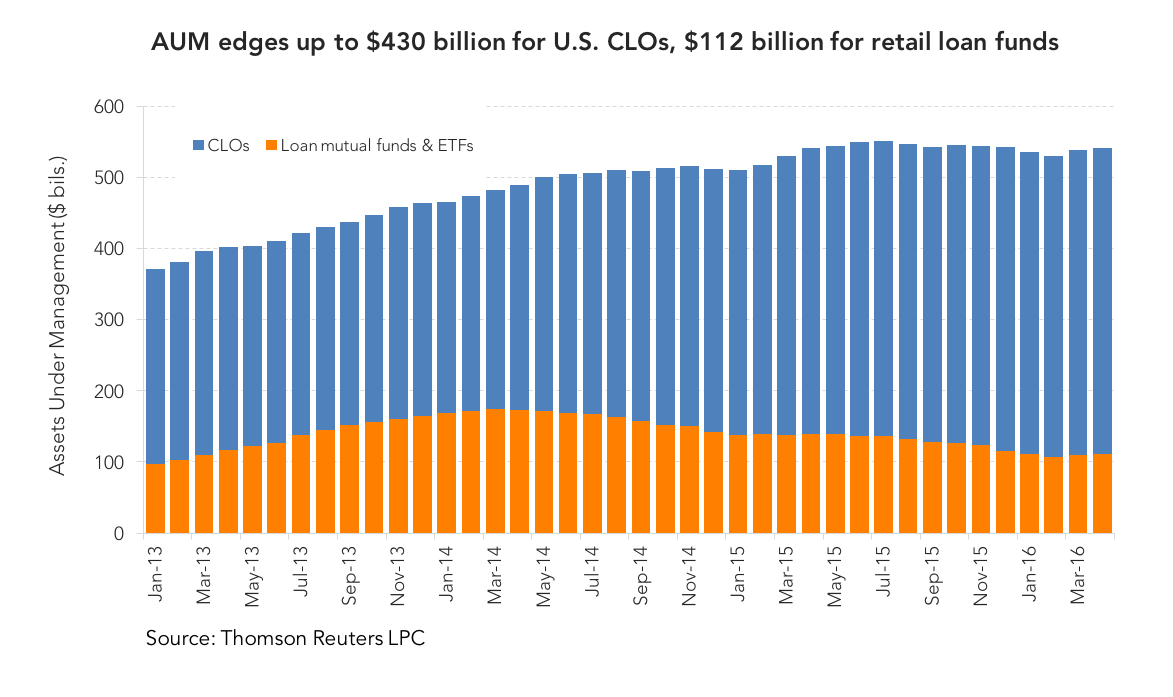 This brought year to date issuance to $14.1 billion (34 deals), down sharply from $41.2 billion (76 deals) in the same period last year. More recently, there have been an additional $1.7 billion of issuance (4 deals) so far this month through May 13. For retail loan funds, though outflows have been the dominant trend in recent times, early May has seen modest inflows of $387 million (based on funds which report flows on a weekly basis).



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
