


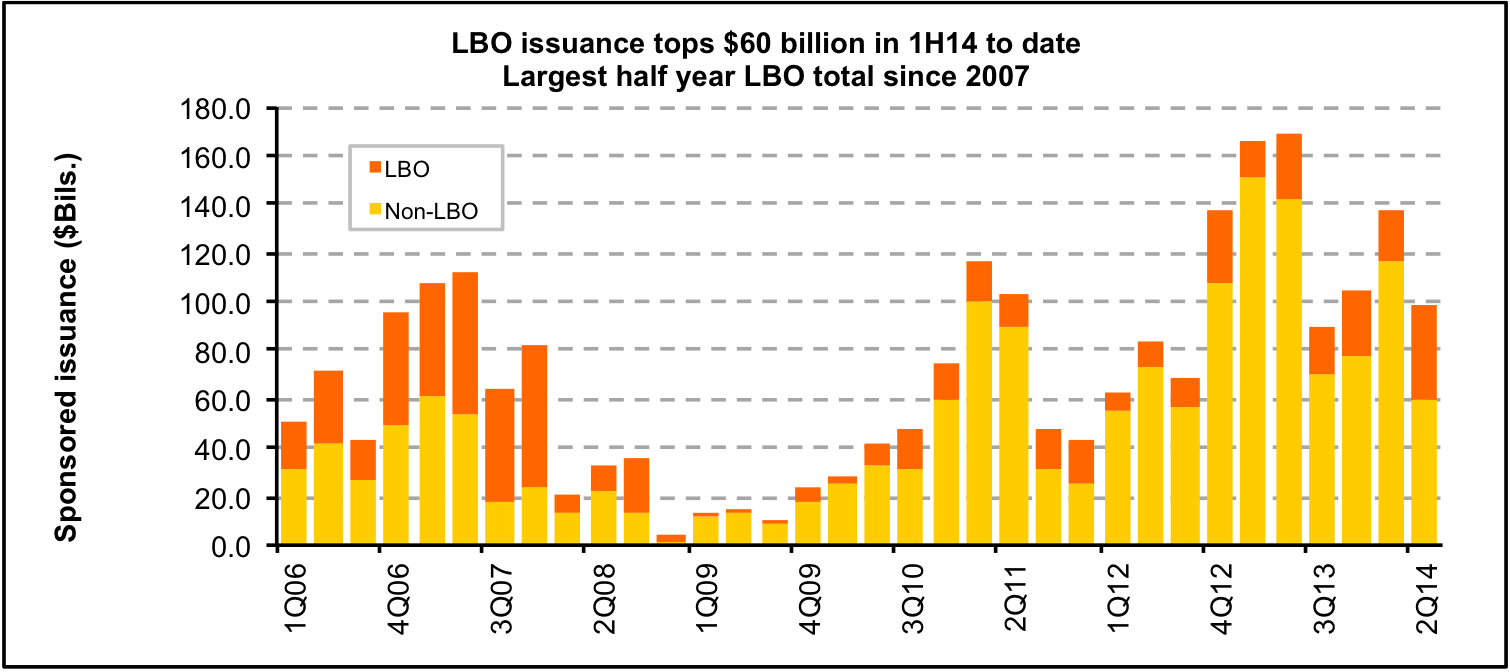
At nearly $240 billion, 1H14 sponsored loan volume to date is on a steady upward trajectory, with a 21percent increase over 2H13 issuance (although still shy of 1H13 totals of $335 billion) with almost two weeks left in the quarter. An additional $15 billion in sponsored loan volume is currently in market. More notably however, nearly $105 billion of total completed issuance (and roughly $12 billion of issuance currently in market) or about 50 percent of year to date lending represents new loan assets. LBO activity which has been anemic since the credit crisis, has fueled over $61 billion in closed sponsored volume so far in 2014, the highest half year total since the second half of 2007 ($104 billion). At nearly $40 billion, 2Q14 LBO volume is nearly twice that of 1Q14 and the highest level since 4Q07.
Source: Thomson Reuters LPC



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
