


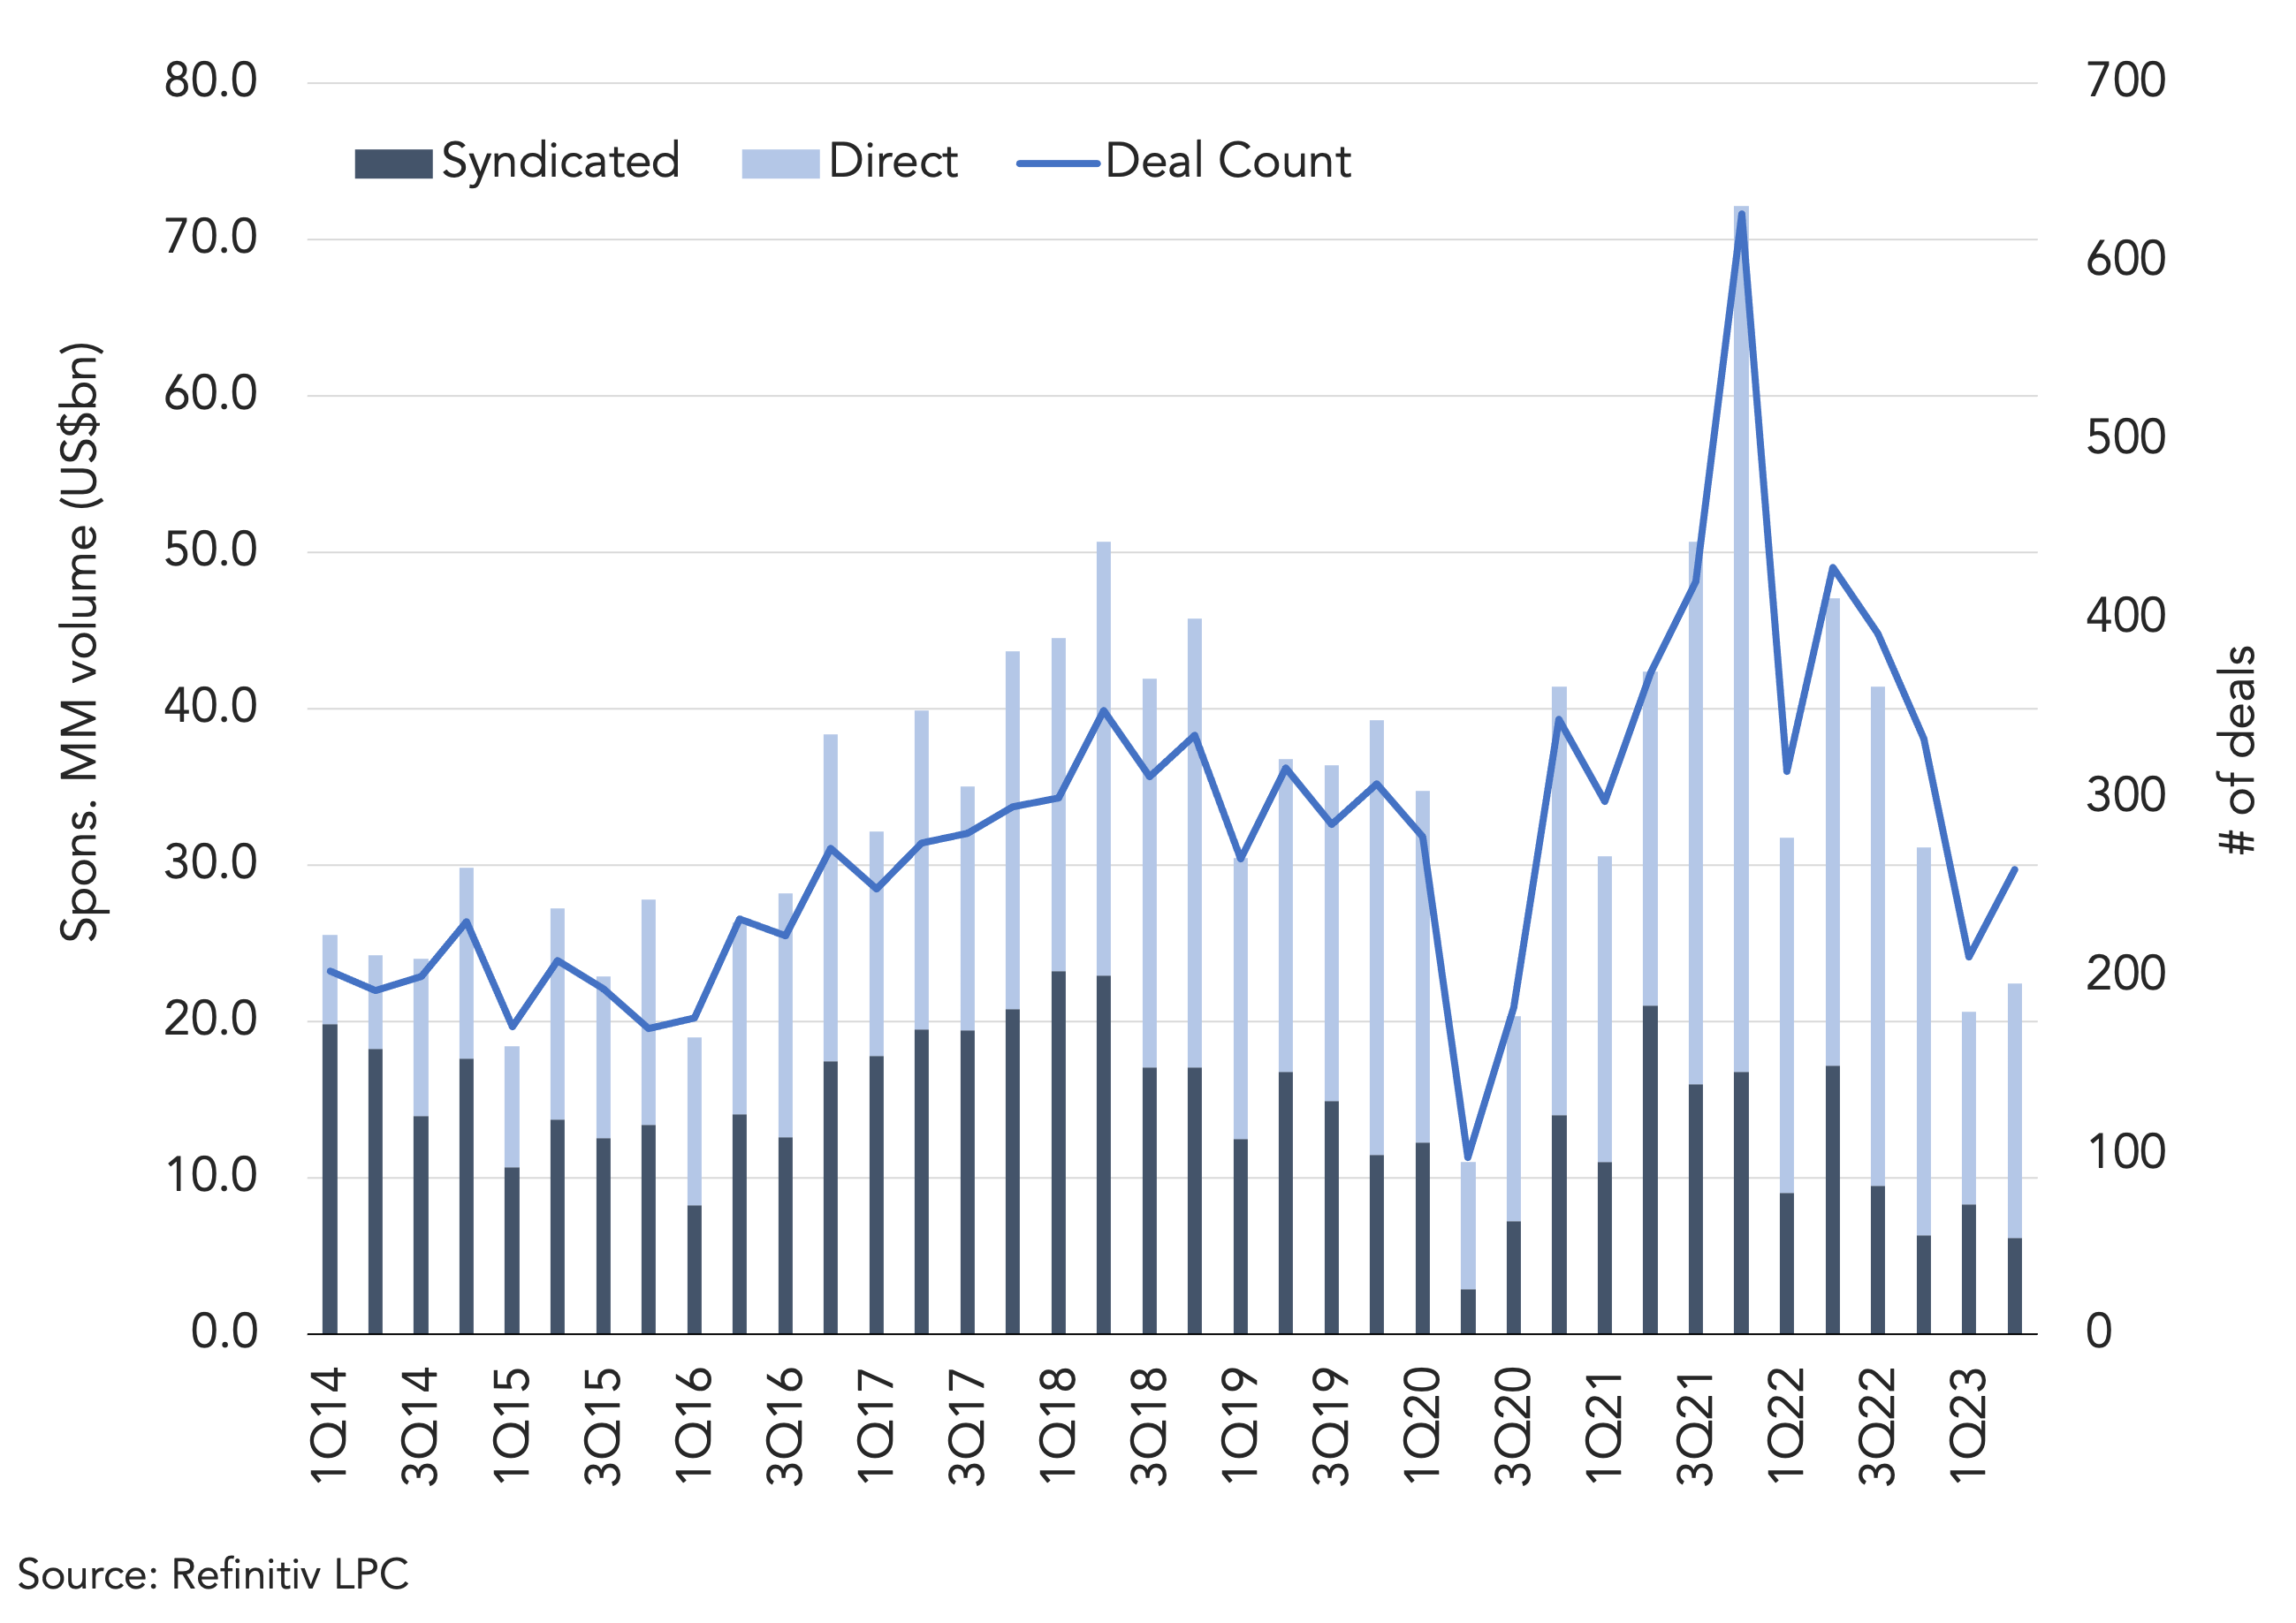
Activity picked up in the US middle market direct lending space in 2Q23 but remained at lower levels. At US$16.3bn, sponsored middle market direct lending volume was up 32% from 1Q23 but was down 46% year-over-year. In contrast, the syndicated sponsored market slowed down relative to 1Q23, with issuance dropping 26% quarter-over-quarter and a whopping 64% from 2Q22. In turn, the ratio of direct lending to syndicated loan volume climbed to 2.6 times after dropping to 1.5 times in 1Q23. Finding quality deals, low M&A activity and more selectivity continue to be the main factors hindering activity in the sponsored market.
(Past performance is no guarantee of future results.)



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.