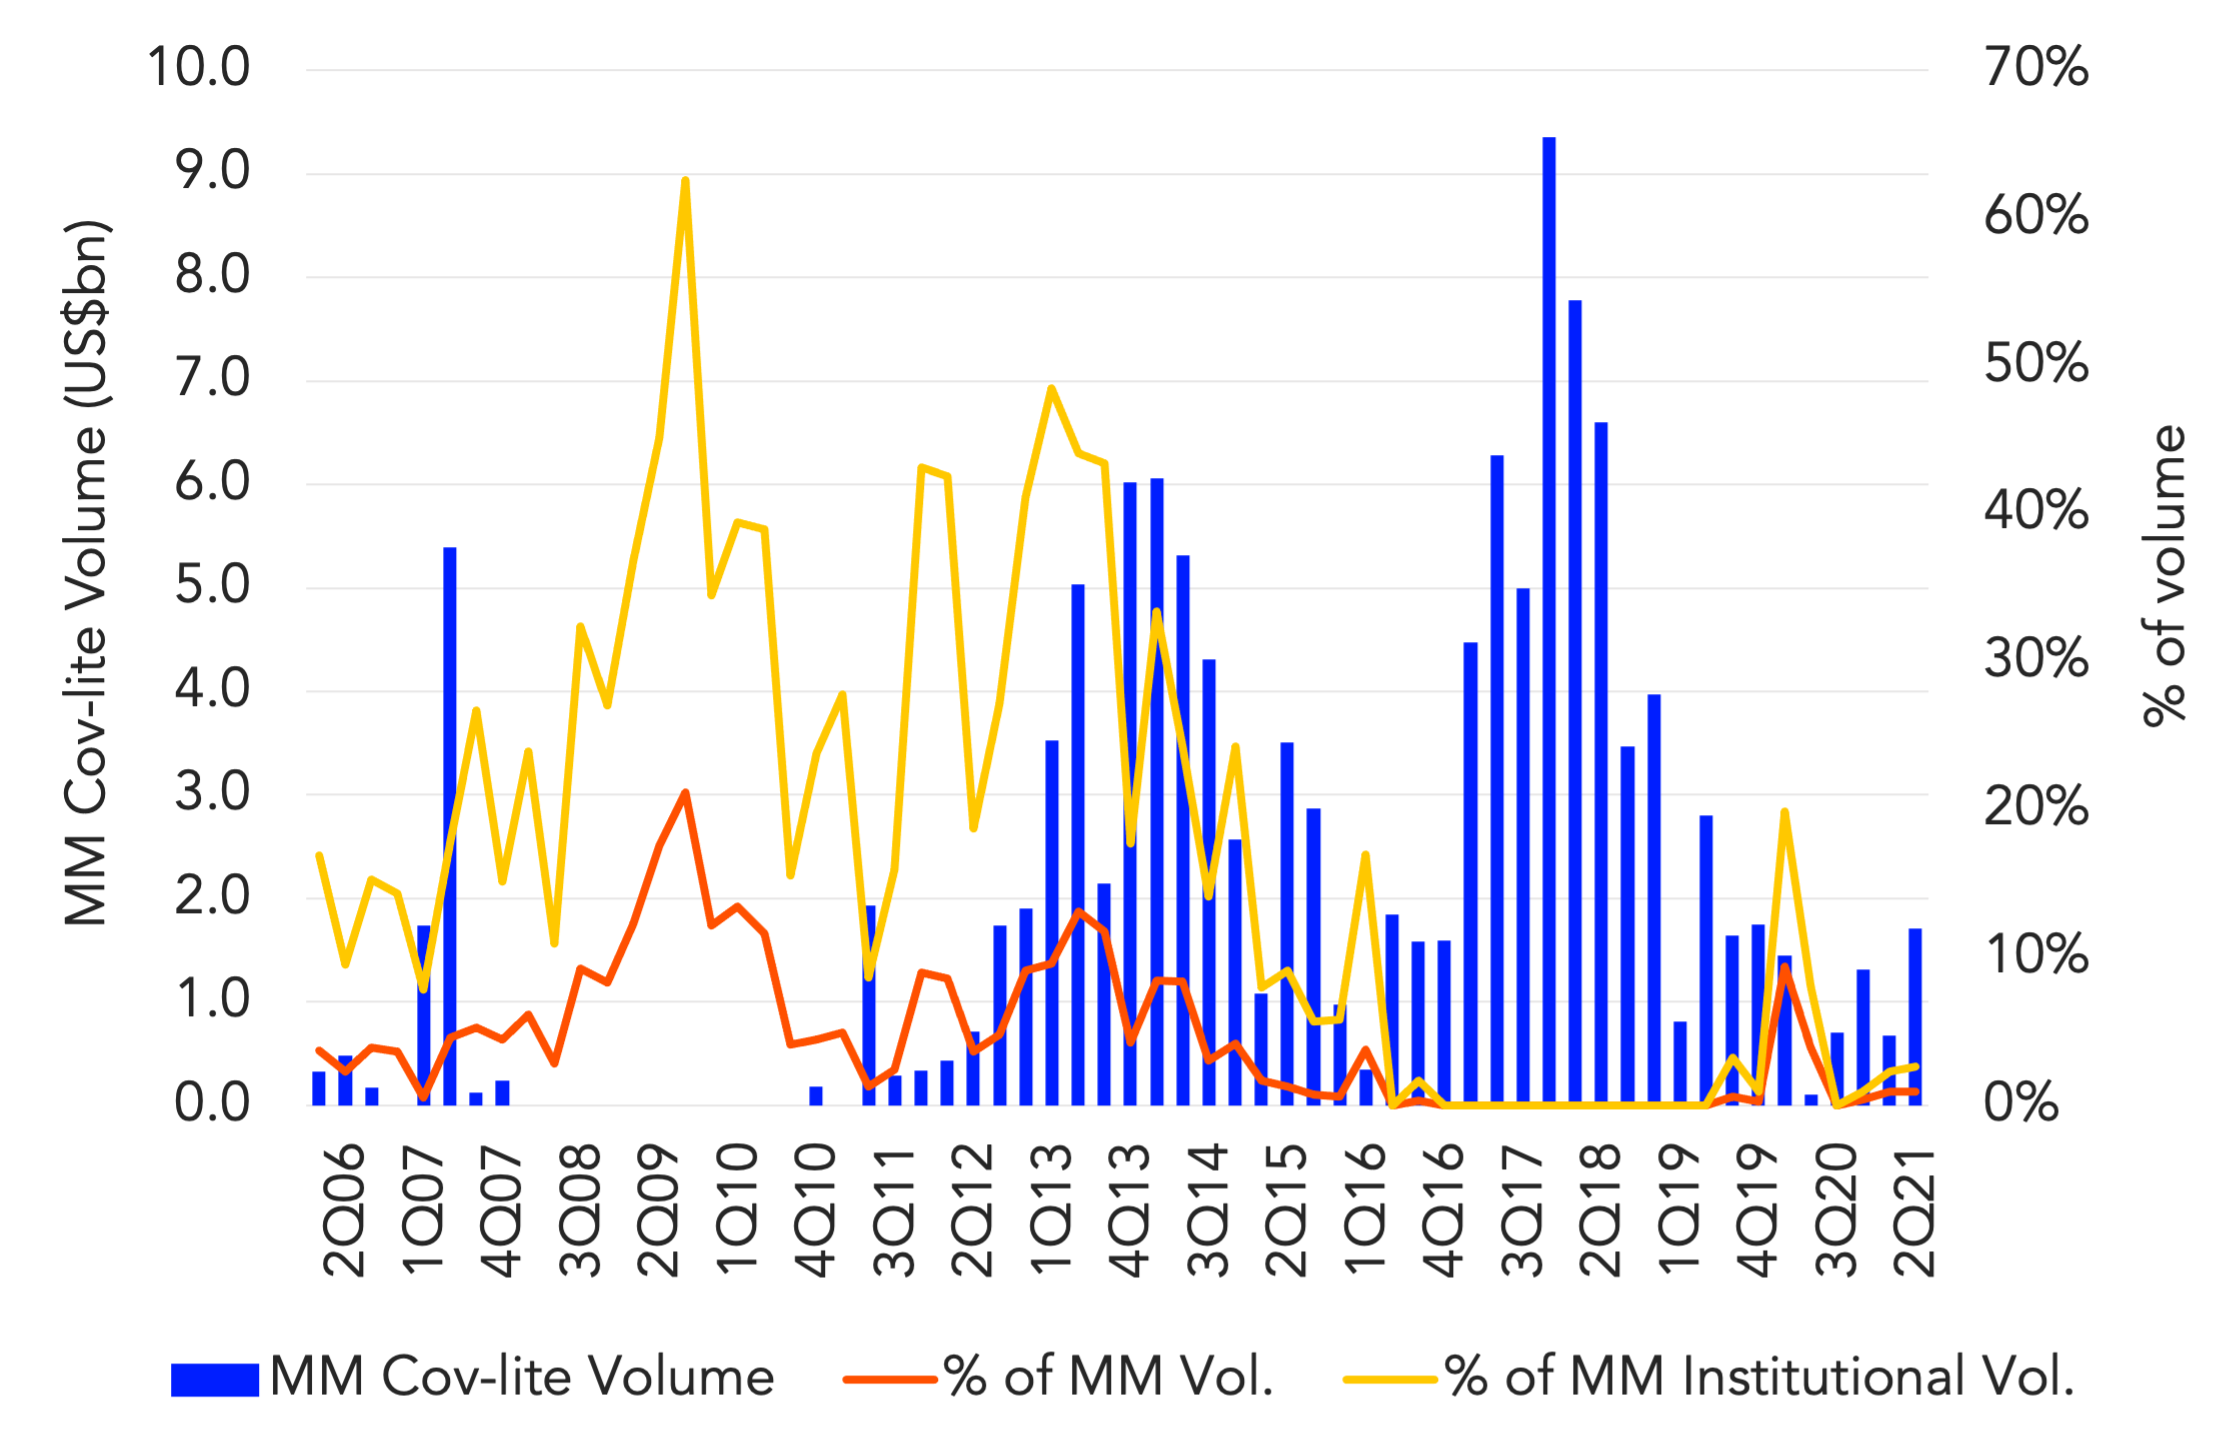
Middle market covenant-lite volume was tracked at US$1.71bn in 2Q21, the highest level since 4Q19’s mark of US$1.75bn. Totals represented a 155% increase over the $670m tracked in 1Q21. The jump comes as the middle market lending arena remains ultra-competitive, characterized by lower pricing, higher leverage thresholds, and looser documentation in 1H21.
MM cov-lite issuance represented 3.7% of overall middle market volume, and 16.87% of institutional middle market volume in 2Q21. Overall, covenant-lite structures have been trending downward after hitting a US$9.35bn high in 4Q17.
According to Refinitiv 3Q21 Lender Outlook Survey, lenders are seeing a meaningful uptick in cov-lite structures among unitranches and smaller deals in the middle market. Survey results indicated that almost a third of MM lenders will provide covenant lite deals to issuers with less than $40m EBITDA, with 11% going below $20m; three years ago, no lenders said they would go below the $40m threshold.




Latest news

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…