



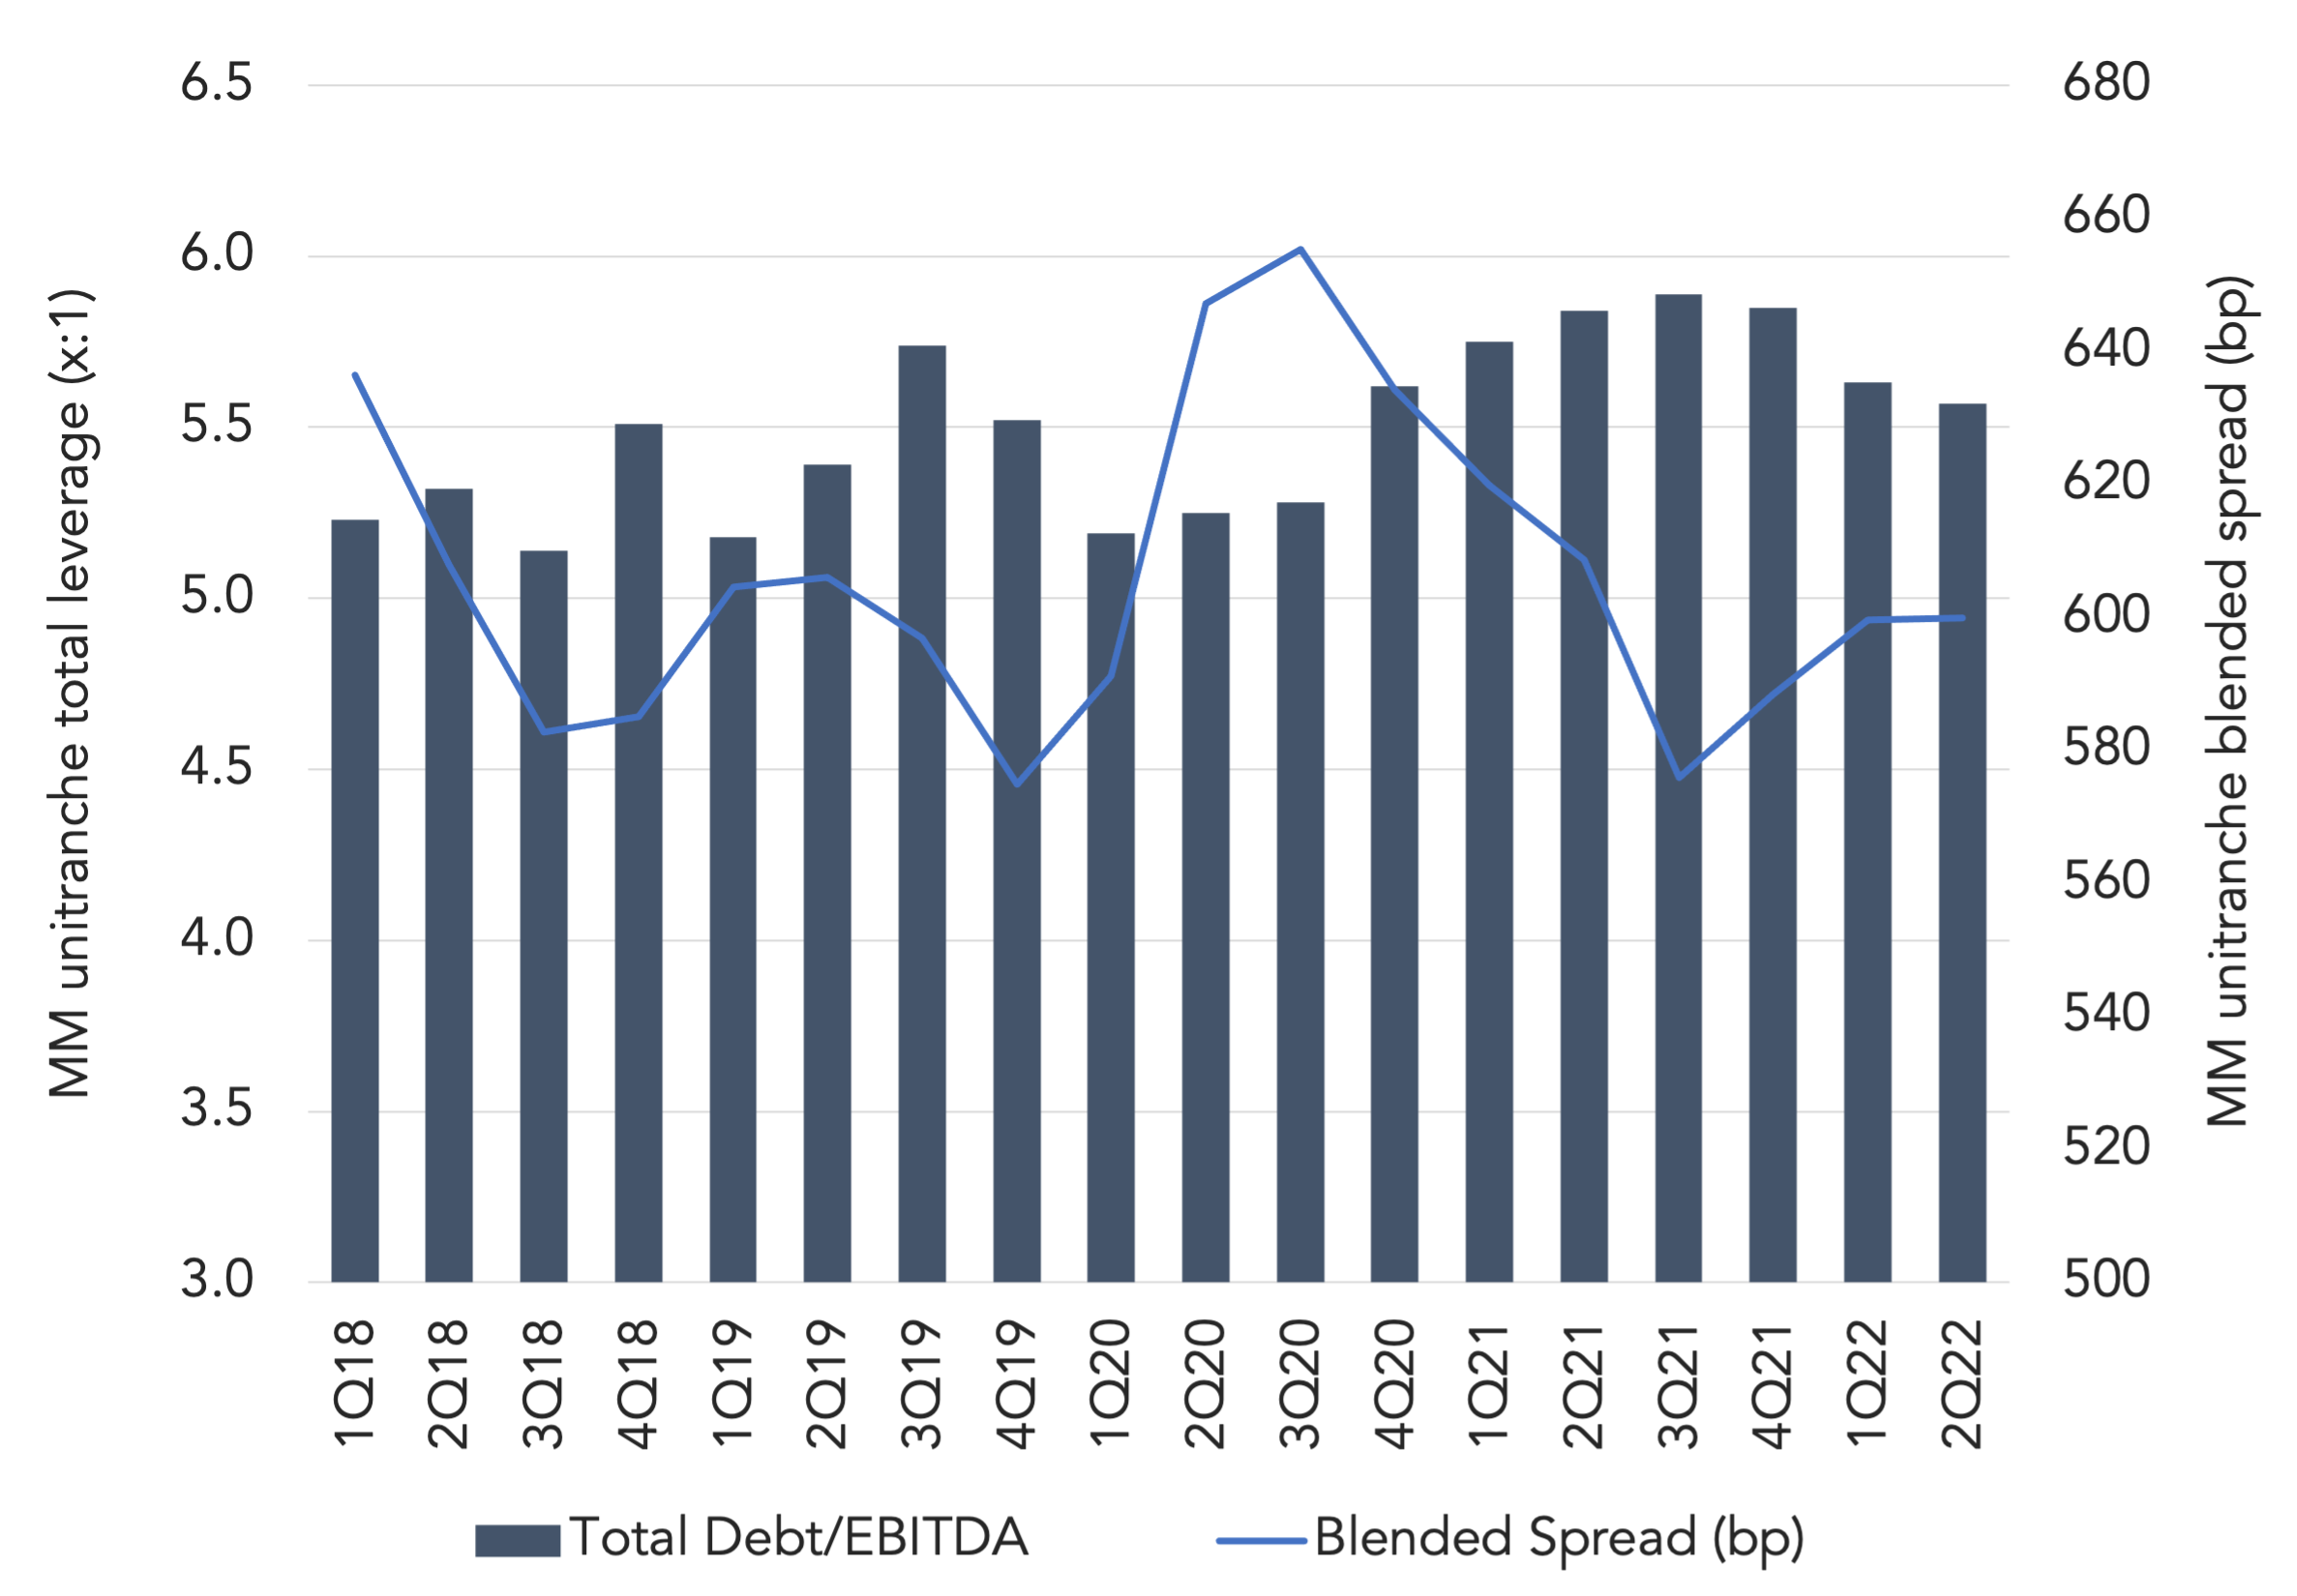
Leverage on middle market unitranche loans tightened to 5.57x in 2Q22, its lowest level since 3Q20, as it continued to retreat from the record highs seen in 2021. From a pricing perspective, blended spreads were flat for middle market unitranches, averaging 600bp in the most recent quarter. In comparison, large corporate unitranches saw spreads widen to 586bp in 2Q22 from 578bp in 1Q22. Looking at volume, overall unitranche loan issuance of US$38.3bn was up 56% from 1Q22, posting the third highest quarter on record. Unitranche deal flow climbed in the middle market and even more so in the large corporate market, as borrowers tapped the direct lending market in response to volatility hitting the broadly syndicated market. Unitranche issuance totaled US$12.7bn in the middle market and US$25.6bn in the large corporate market in 2Q22, up from US$9.8bn and US$14.8bn, respectively, in 1Q22.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
