Middle Market Survey – Were you able to lend as much as you wanted to in 2Q24?

LSEG (1)
Content hub / Article / LSEG / Middle Market Survey – Were you able to lend as much as you wanted to in 2Q24?

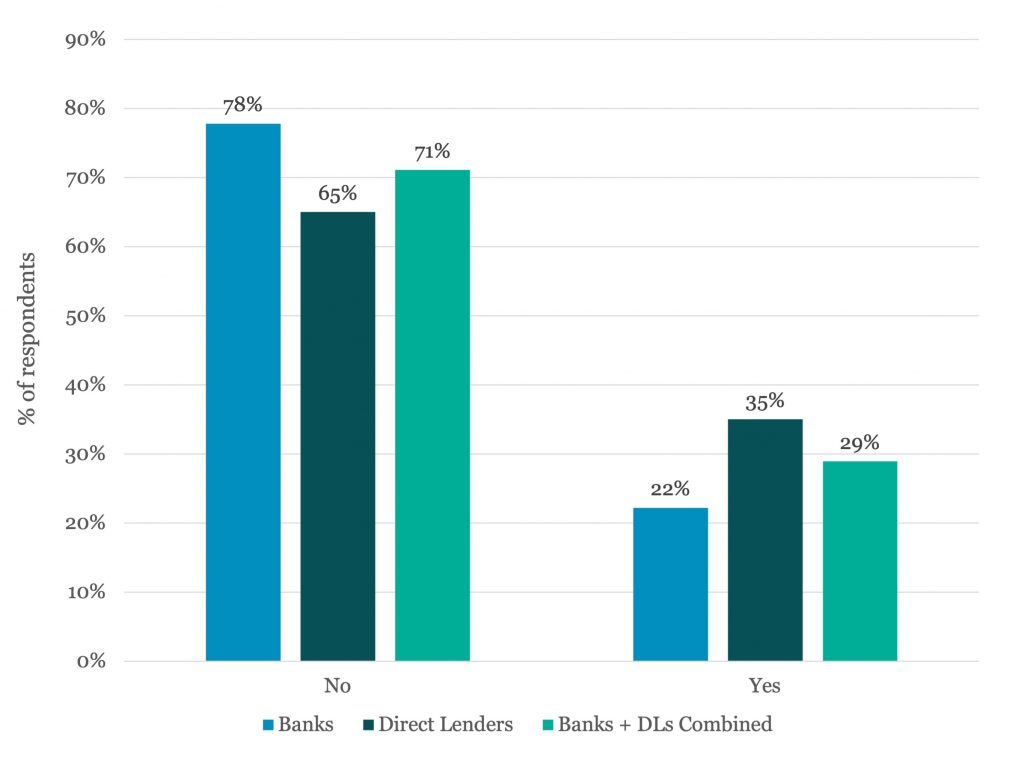
Even though middle market loan volume increased by 27% to US$67.2bn in 2Q24, many middle market lenders found sufficient opportunities hard to come by in the most recent quarter, according to LSEG LPC’s 3Q24 Middle Market Outlook Survey. A clear majority of respondents (71%) said they were not able to lend as much as they wanted in 2Q24. This was the case for both banks (78%) and direct lenders (65%). Many cited lack of new money deal flow and the competitive landscape as the biggest factors impacting lending opportunities. On a more positive note, lenders said add-ons were a good place to put money to work in the most recent quarter.


Contact CJ Doherty
Private Debt Investor New York Forum

September 15-16, Hudson Yards, New York

Private Debt Investor New York Forum

Bringing together the investors, managers and advisers shaping the next phase of the market — 200+ allocators and $10.6 trillion of LP capital expected. Benchmark strategies, hear from leading LPs, and cut through market noise over two unmissable days.
Learn more
US Private Credit League Tables H1'26

Report

US Private Credit League Tables H1'26

The definitive rankings covering private credit activity in H1'26.
Download
PitchBook's Q2 2026 US PE Breakdown

Report

PitchBook's Q2 2026 US PE Breakdown

Software freezes and energy powers on as US PE deal value falls 38% in Q2 2026.
Download
Making sense of private credit defaults

Webinar

Making sense of private credit defaults

What does private credit default data really tell us? Join our exclusive webinar featuring experts from KBRA, Moody's, Fitch Ratings, and S&P Global to find out.
Register

Latest news

    KBRA DLD Default Indices

    Read More

    Fitch Ratings’ U.S. Private Credit Default Rate Rose to 6.3% in August 2026

    Fitch Ratings recorded a U.S. Private Credit Default Rate (PCDR) of 6.3% for the trailing 12 months (TTM) ended August 2026, up from 6.1% in July 2026 and a record high.
    Read More

    High-Yield Bond Statistics

    Read More