



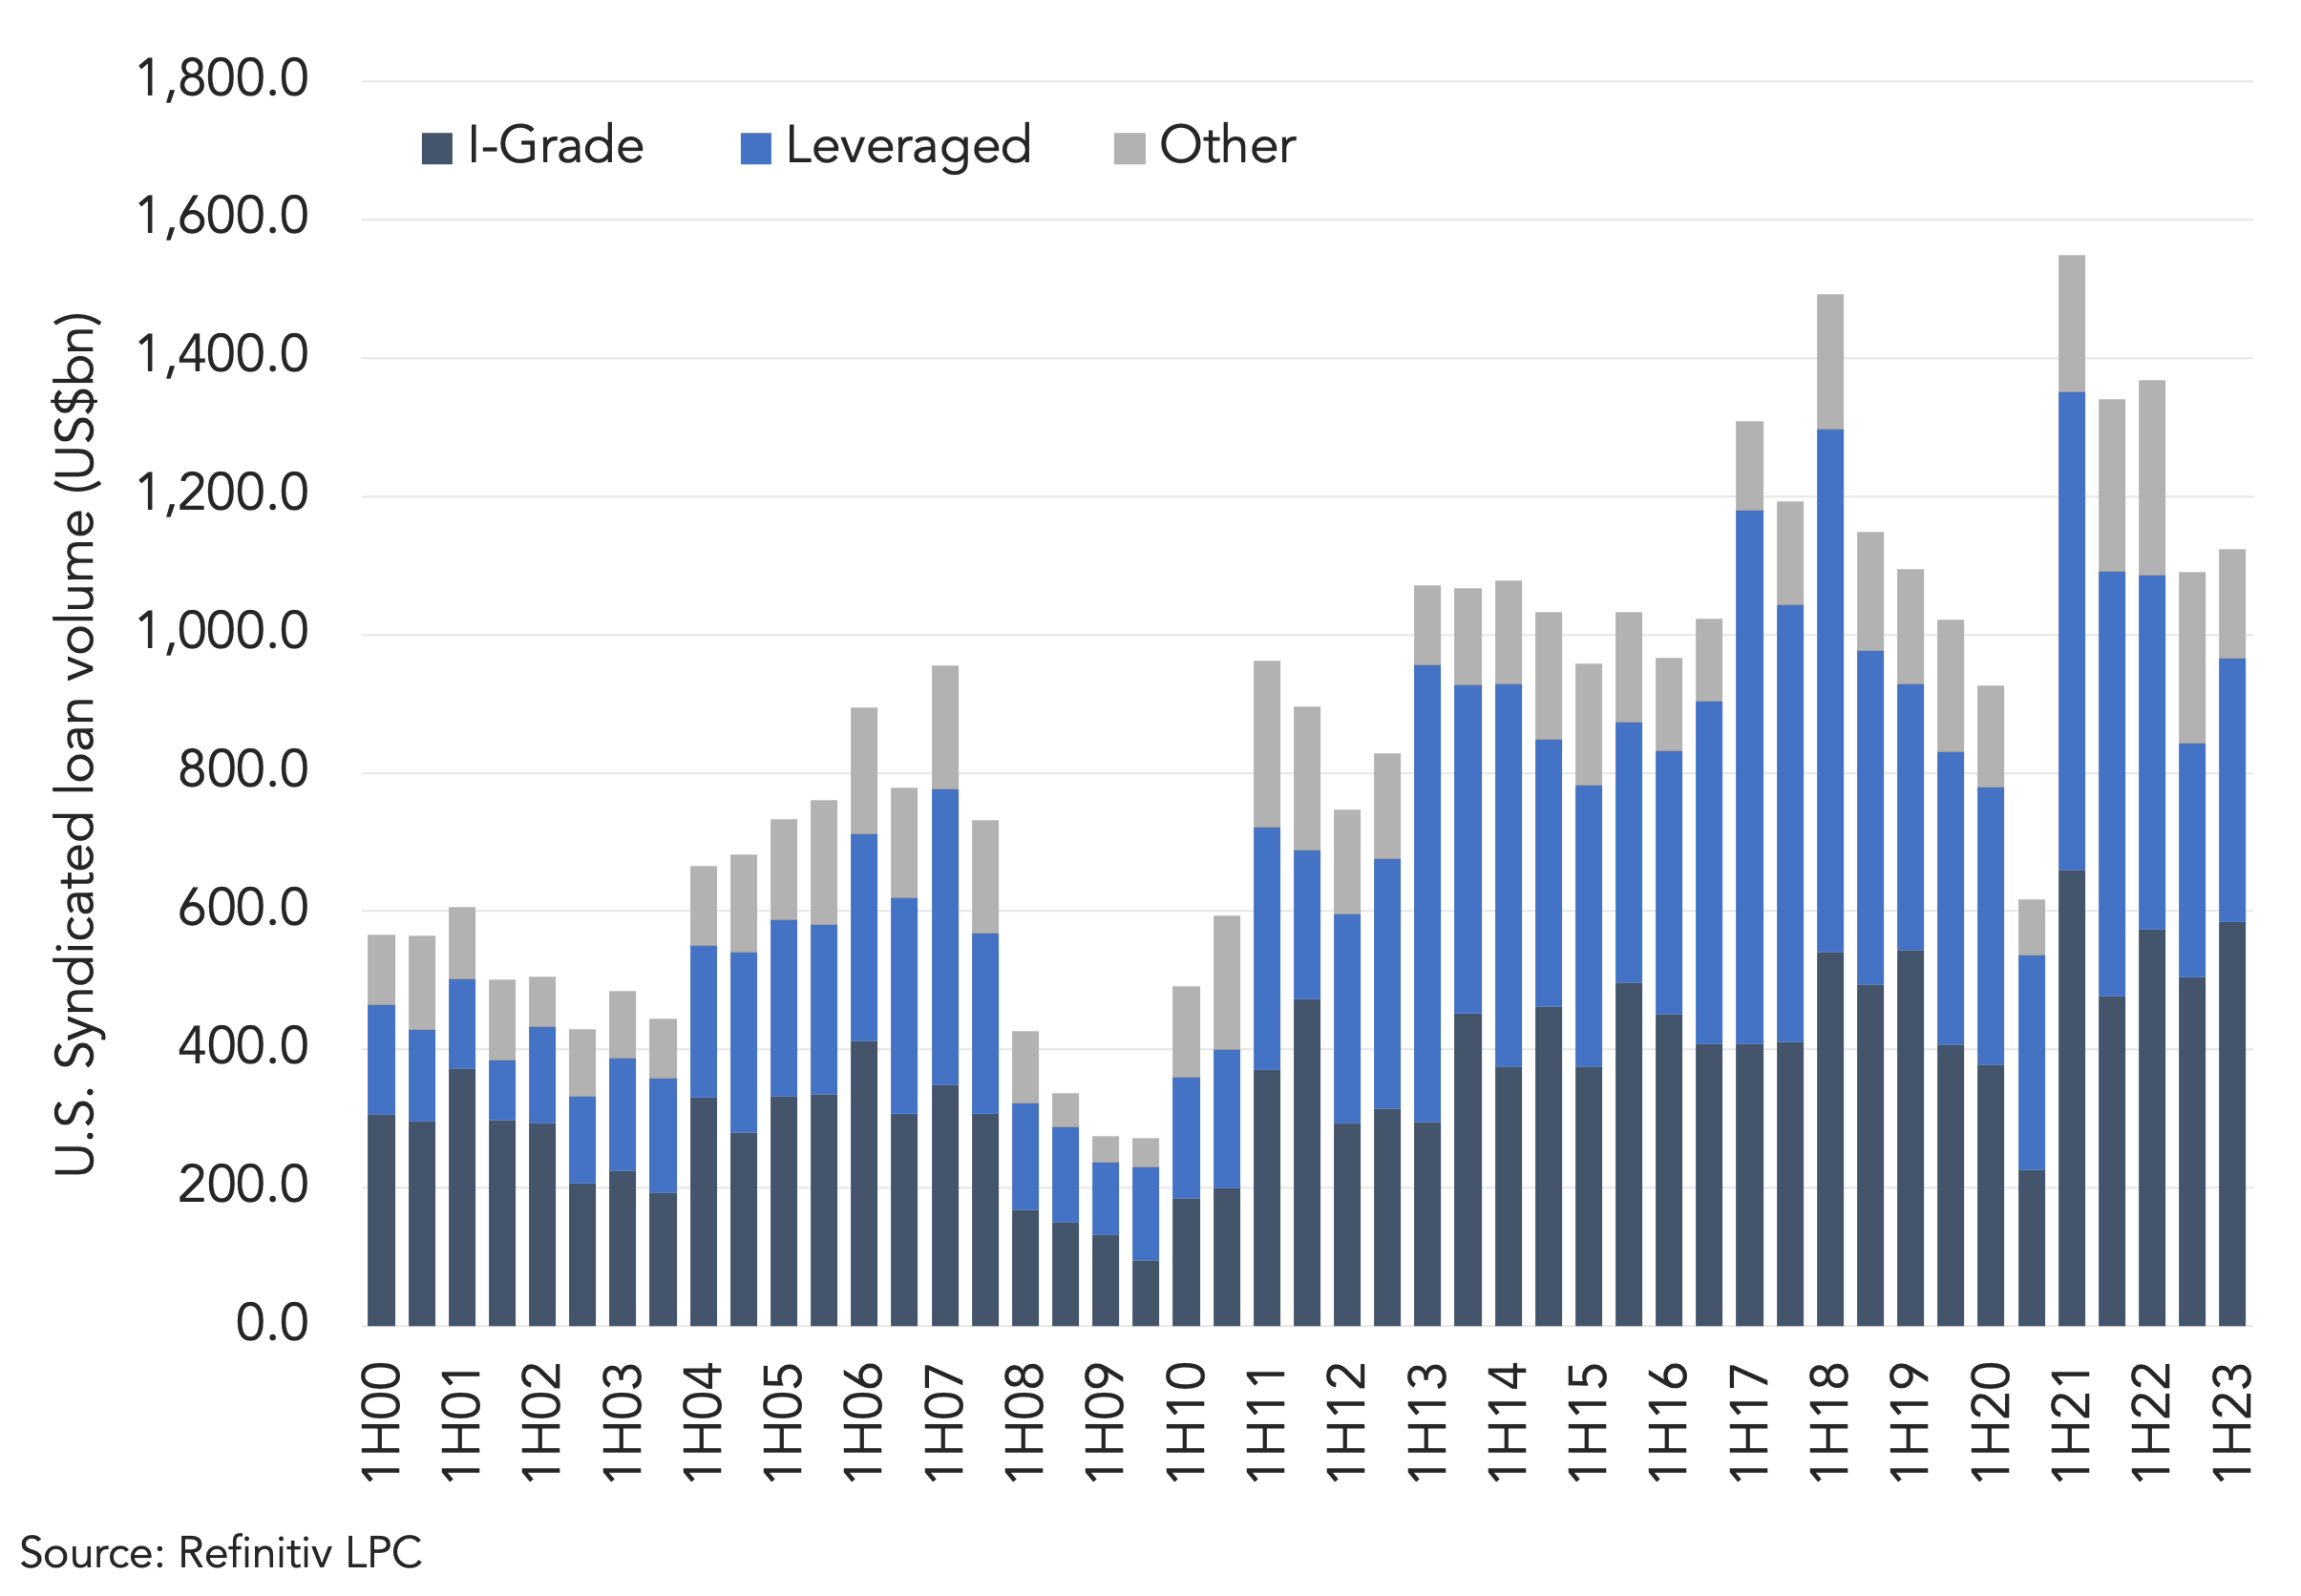
Bruising market volatility marked by higher interest rates, increased regulatory scrutiny of large corporate M&A deals and lender expectations of greater regulatory oversight among reigonal banks contributed to a significant slow down in the 1H23 US BSL market. Roughly US$571bn of issuance was completed in 2Q23 to push totals for the first six months of the year to US$1.12tr. Quarterly volume represented a 32% drop year over year while 1H23 results were off nearly 18% to mark the weakest 1H results since 2020. Just over US$312bn of investment grade volume cleared the market during the quarter as acquisition deals of size remained limited. Lenders did note however that market steadiness remained in place. At US$585bn, 1H23 investment grade volume was up 1.8% compared to the same time last year. Results in the leveraged loan market were more muted amid a very thin calendar of M&A deals. Instead, refinancing activity fuelled the pipeline. Just over US$ 189bn of leveraged loan volume cleared retail syndication during the quarter to bring 1H23 totals to nearly US$381bn, down 25.6% year over year.
(Past performance is no guarantee of future results.)



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…