


Middle market dominates for LBO activity with direct lenders stealing share from syndicated market
New Co/New Traditions! Join us for a half day on September 12th for our 24th Annual Loans Conference.
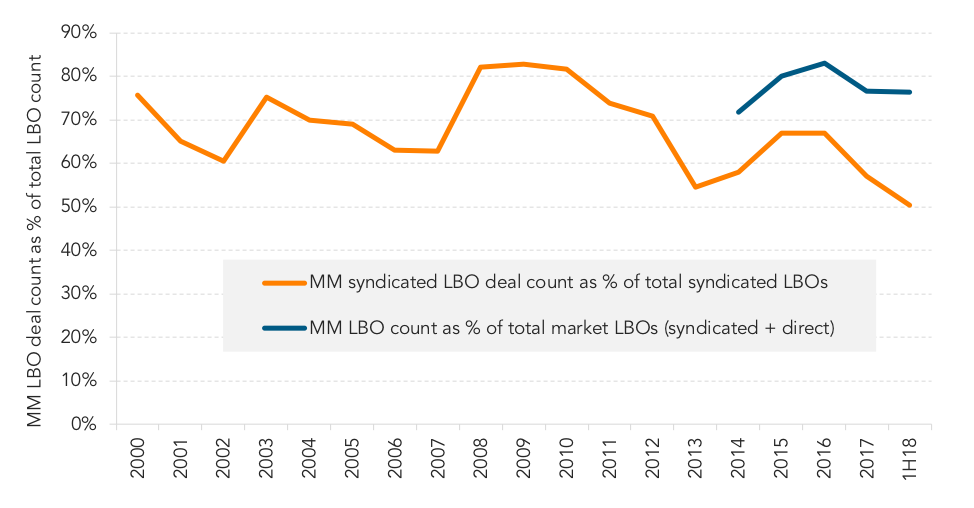
The middle market continues to remain a hot spot for LBO activity – however the numbers don’t always show it. Pre credit crisis (2004-2008), roughly 65-80% of syndicated LBOs financed were for middle market issuers as opposed to large corporate issuers. When looking at 2018, that figure has dropped to just 50% – a meaningful decline. However, the reason for the drop is not because middle market LBOs are out of favor relative to large corporate deals, it’s because the direct lending market has won a significant share of middle market buyout activity. As the chart shows, when direct lending deals are included in the mix, roughly 75-80% of buyout deals getting done are in fact for middle market issuers rather than large corporates – a similar level to what we saw during the last buyout boom. LPC’s private database shows that in 2018 middle market LBOs financed in the direct lending market are outpacing middle market LBOs financed in the syndicated market by nearly 2 to 1. That is because sponsors who are paying lofty amounts for business really value ease of execution, swiftness and privacy. Syndicated MM LBO issuance only reached $9.9B in 1H18 but LPC tracked another $18.7B closed behind the scenes by direct lending platforms. In just a few short years, the direct lending market has grown dramatically with middle market platforms amassing significant amounts of capital and growing their hold sizes to levels never seen before. So far in 2018 over US$33.4B in U.S. direct lending capital has been raised on the heels of a record $69B just last year. And the money coming in does not seem to be slowing.
Contact: Fran Beyers
frances.beyers@thomsonreuters.com



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.