



The spectacular turnaround in sentiment in the leveraged market resulted in a 137% jump in refinancing activity in the second quarter, reaching US$112bn, up from US$47bn in the first quarter and the highest since 2Q15’s US$165bn. With cash build-up from repayments, investors who had been sitting on the sidelines in the early part of the year amid broader market volatility and heightened risk aversion sought assets at a discount in the oversold secondary. In the primary, pent-up demand was met with an absence of new money supply, setting the stage for opportunistic repricings.
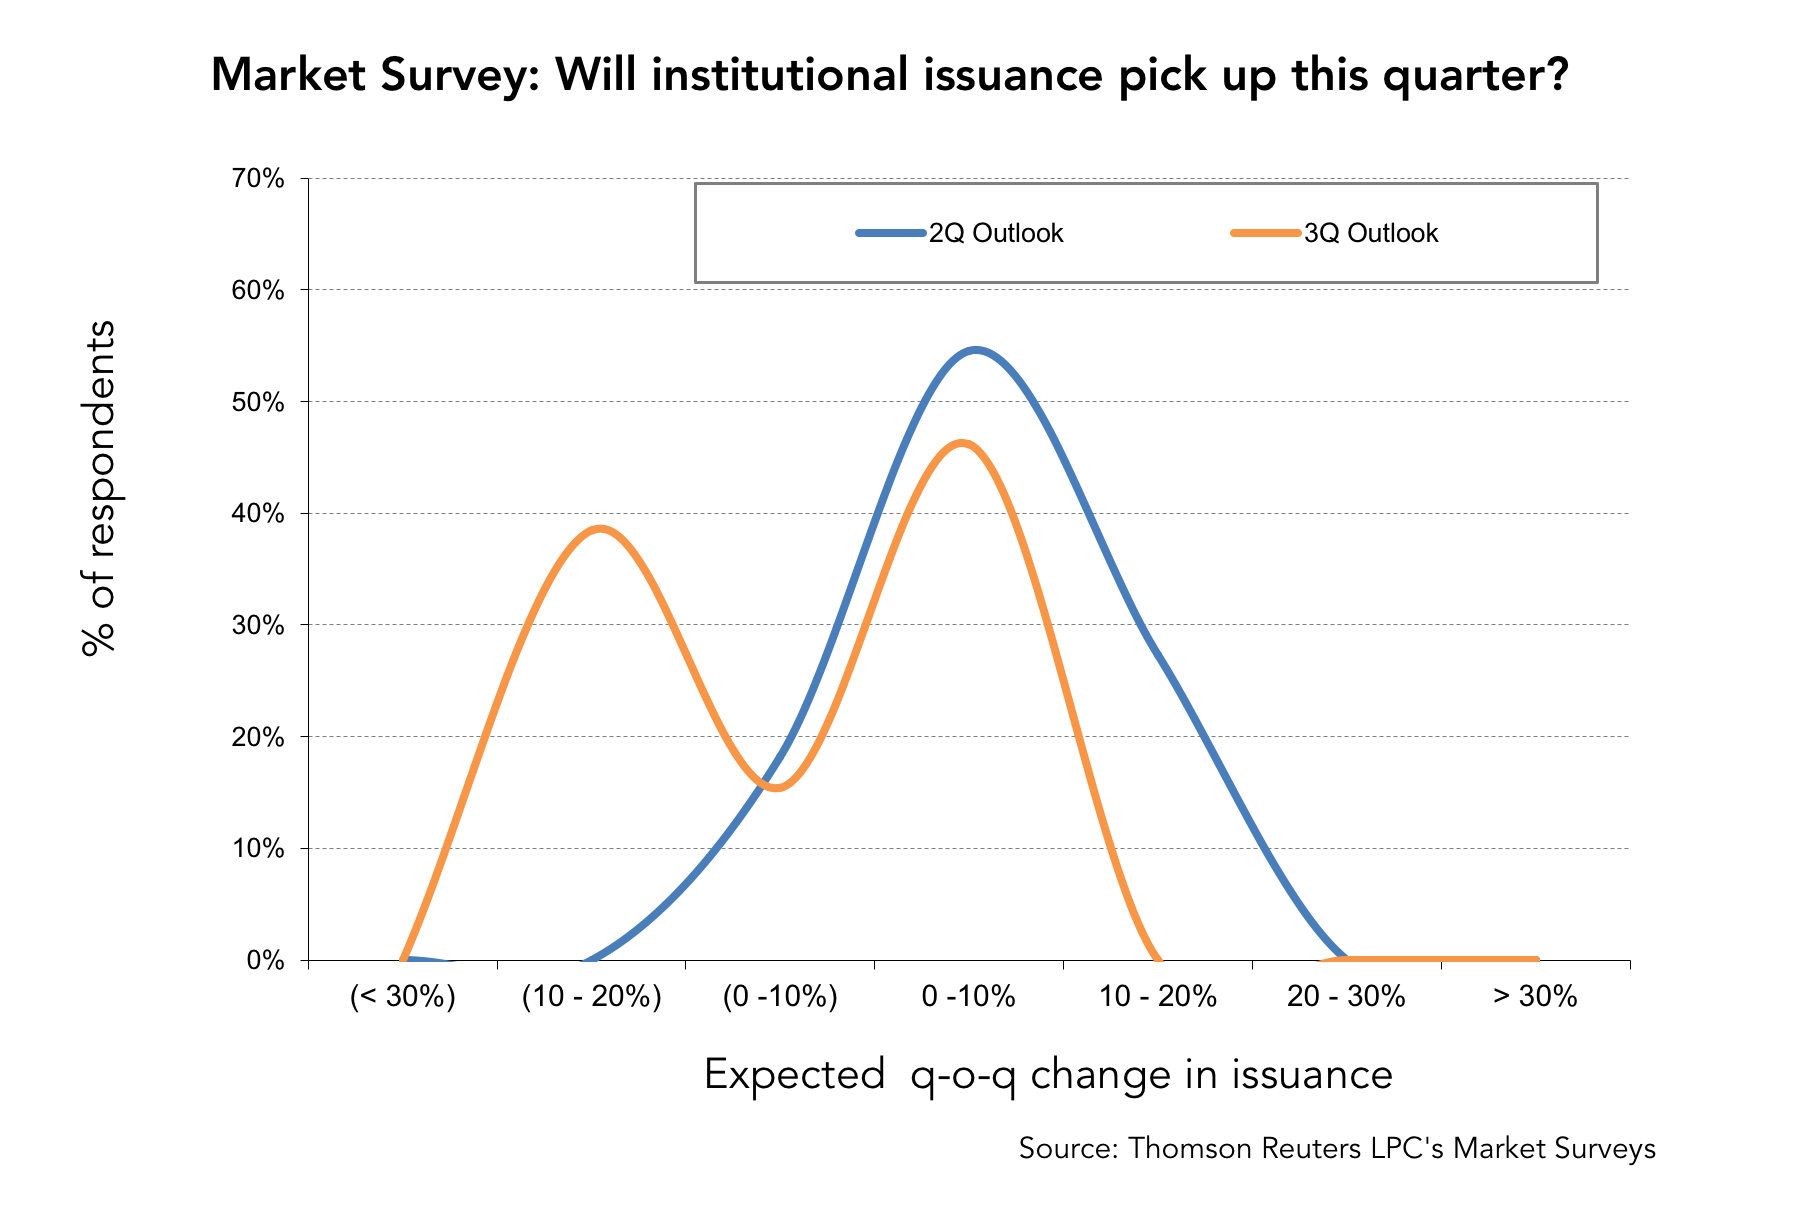 Institutional refinancing activity jumped to US$52bn in 2Q16, up from just US$3bn in 1Q16 and US$18bn and US$13bn in 3Q15 and 4Q15 respectively. “The market turned around very hard from winter,” said one lender. “Aside from commodities looking better, there wasn’t a lot to hang your hat on so the rally is not fully explicable except there was a lot of cash and all it took was a little spark to get it in motion. We sprinted hard since then.” However, as the quarter wound down and in the aftermath of the UK vote to leave the EU, momentum began to slow and 54% buyside and sellside sources surveyed by Thomson Reuters LPC expect issuance to drop in 3Q16 especially as markets digest Brexit. As summer malaise sets in, arrangers and investors alike are seeking new issue supply and issuers are again looking for windows to refinance in the absence of a pick-up in new deals.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
