



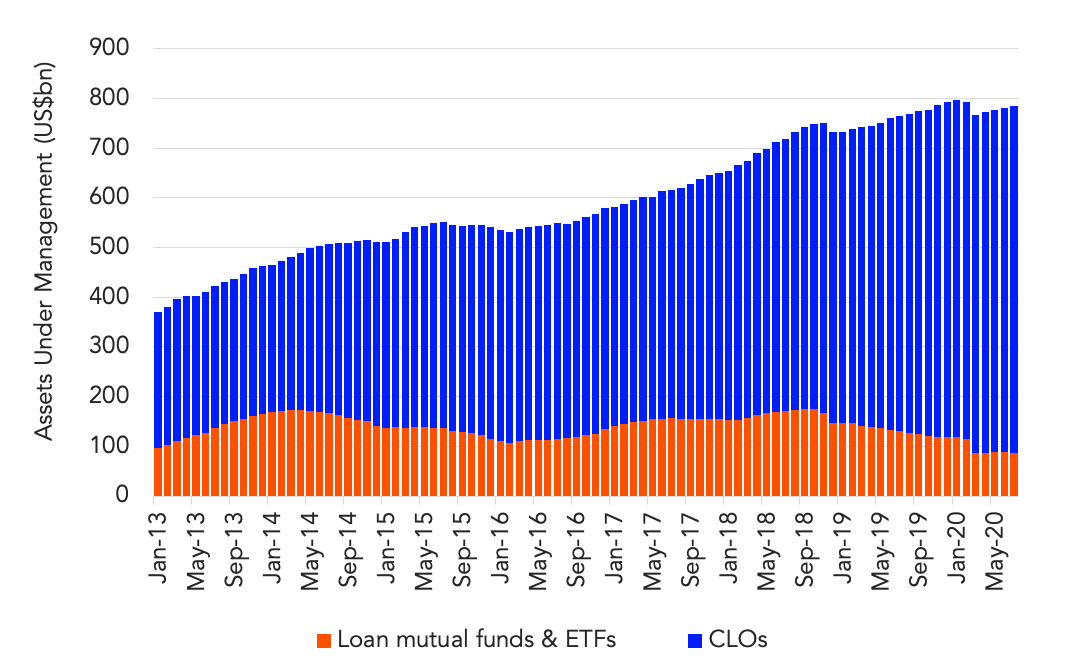
US CLO assets under management along with loan mutual fund assets under management, inched up in July for a combined total of US$784.4bn, which remains down 1.5% from January’s US$796bn peak. Loan market outstandings ticked lower to end July at US$1.180trn, driven by muted institutional volume post-COVID. CLOs’ share of the institutional market stands at 58% while loan funds make up a 7.3% share of the market. Loan fund assets under management ticked down to US$87.4bn at the end of July, from June’s US$88.2bn. As a result, loan funds saw AUM shrink by nearly one third from January’s US$119bn high. Meanwhile, US CLO assets under management inched up to US$697bn in July from US$693.4bn in June and May’s US$687.9bn. They are up 4% this year while European CLOs were managing €136bn in assets by the end of July, which is up 9% this year. European CLO market issuance continues to rebound and recorded in July its busiest month since February, with 8 deals pricing for a total of €2.6bn contributing to €12.7bn for the year, which remains 37% lower than the same time last year.



Latest news

Summer recovery stalls as secondary loan pricing retreats from September peak
The summer recovery in US leveraged loan secondary market pricing has recently lost momentum, with average prices declining to 95.54…
Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.8% as of…