After a record-breaking 2Q14, there was a sharp pull-back in the HY bond market in July. In fact, a number of deals remain on the calendar because they didn’t make it into the market the last week of July due to adverse market conditions. Investors have been wary of frothy market conditions, and according to the BAML HY Master II Index, high yield bonds declined 1.322% in July and HY spreads widened from 350bp on the first of July to 425bp last Friday.
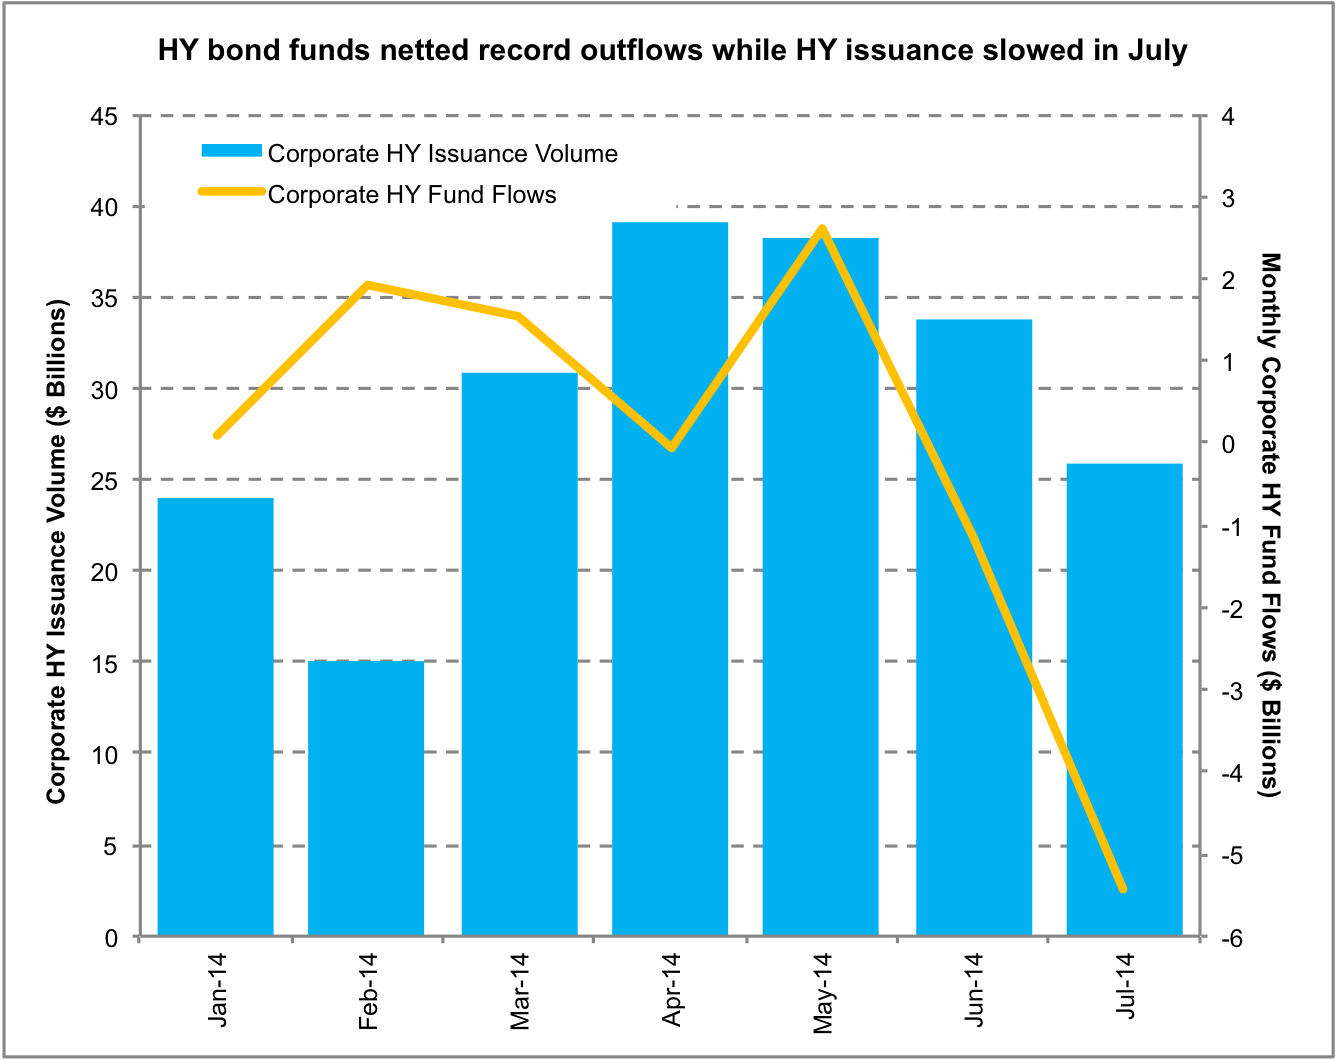
July was challenging. After nearly $5 billion of inflows into corporate HY funds in the first half of the year, July netted outflows of $5.43 billion. The week ending July 16th netted outflows of $1.68 billion, the week ending July 23rd netted outflows of $2.38 billion, the ninth largest weekly outflow on Lipper records going back to 1992, and the week ending July 30th netted outflows of $1.48 billion. In the primary market, after pricing $6.79 billion of HY bonds the week of July 7th, the week of July 14th priced $5.22 billion, and issuance the week of July 21st slowed to just $4.56 billion over eight deals.
Issuers had to pay up to get deals done, giving pause to other potential opportunistic issuers. Aston Escrow Corp, Citgo Petroleum, and Micron Technology all had to widen out pricing from price talk the week of July 21st. In the week that followed, Unifrax and Harland Clarke downsized their offering sizes and along with Mallinckrodt International Finance, NRG Yield Operating LLC, and William Lyon Homes, priced at the wide end of guidance.
Now, this week, it was announced that price talk for Warren Resources’ 8yr senior notes, which had been pushed back from last week, widened to 9.25% yield for pricing later today, up from original price talk of 8.25%.
While there haven’t been timing updates for the other deals still in the pipeline, Jupiter Resources, another deal pushed back from last week, increased whisper levels to 8.5% from 7.5% for its 8yr senior note offering and was heard to be considering pushing its deal to September if it is not able to price this week. Milestone Aviation was also heard to have widened out whispers to 4.75 – 4.875% from 4.25% for its 3yr trade, and NCSG Crane & Heavy Haul Corporation widened out price whispers to 9% from an initial 7.5 – 8% for its 5yr deal.
What were you doing in 1995? Join us for our 20th Annual Loan Conference on Sept. 18th




Latest news

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…