


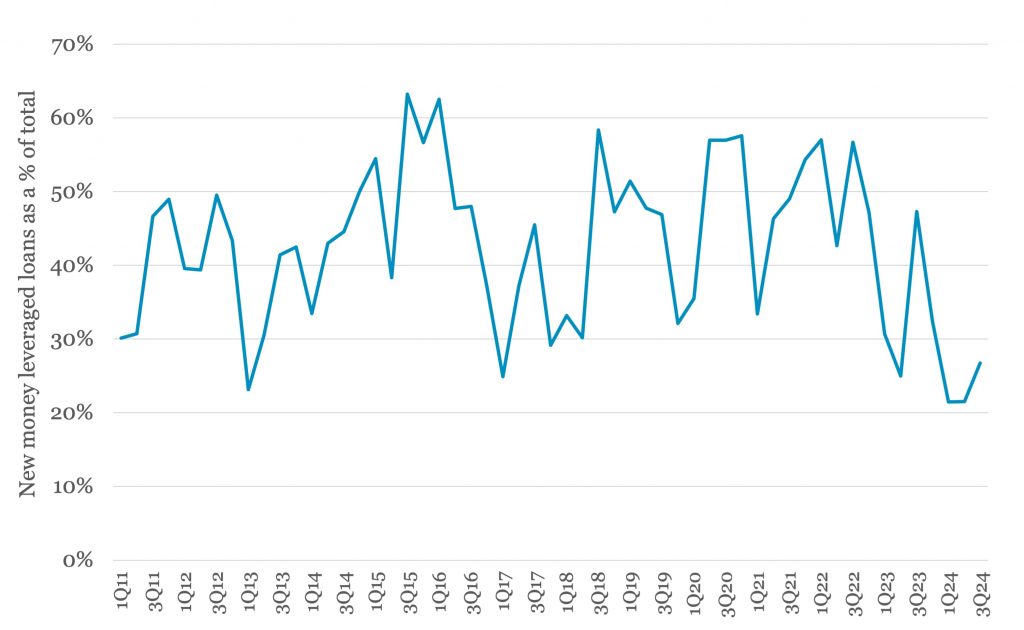
After a slow start to the year, leveraged issuers are increasingly tapping lenders for new and/or incremental loan capacity. In 3Q24 to date, 27% of total leveraged loan volume came in the form of new assets, up from 21% and 22% during each of the first two quarters respectively. Of this, over US$10bn represents completed 3Q24 LBO loan volume (an additional US$16bn is in process). Lenders expect the launch of a US$2.05bn financing backing KKR’s purchase of Infrastructure to come to market before year end. More immediate is the scheduled launch of US$1.55bn in loans to support KKR’s acquisition of Janney Montgomery Scott, a wealth management firm, this week.




Latest news

Spread per turn of leverage tightened 5% for lower middle market
Lenders benefited from better risk-adjusted pricing for larger middle-market and large-cap deals in the third quarter.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line shows BIZD’s dividend yield rising 130bps in a month to 12.9% as of 22 October, although most…

Single-B loan pricing faces renewed pressure in October; 150 bps gap to double-Bs
We noted in our monthly leveraged loan coverage how average new-issue institutional loan yields moved somewhat counterintuitively: single-Bs tightened 14bp…